Jobs report in line; December tightening a go 12/4/15

Stocks are lower after the jobs report came in as expected, which puts the Fed on track for their first tightening in 9 years in a couple of weeks. Bonds and MBS are up small.

Jobs report data dump:

  • Nonfarm payrolls + 211k vs. 200k expected
  • Unemployment rate 5%, in line with expectations
  • Average Hourly Earnings +0.2% MOM / +2.3% YOY in line
  • Underemployment rate 9.9% vs 9.7% expectations
  • Labor Force Participation rate 62.5% vs. 62.4% expected

The general take on the jobs report is that it is good enough to give the Fed comfort to raise rates in two weeks. Digging in deeper, the increase in jobs were in construction (+46k), professional services (+28k), health care (+24k), restaurants (+23k) and retail (+31k). Mining and IT lost jobs.

Homebuilder Hovnanian reported numbers this morning, Revenues were flat compared to last year, while margins fell as deliveries fell 2% in units. The dollar value of net contracts increased 29%, which bodes well for next year. Backlog is up 30%.

Uber is now valued at $65 billion, which makes it about the 80th biggest company in the S&P 500, and gives it about the same market cap as Danaher. The bubble of the day is in these pre-IPO companies. By the time they actually go public, they are typically overvalued.

Negative equity fell from 16.9% a year ago to 13.4% last quarter, according to Zillow. A normal number is closer to 5%. They have a cool interactive map where you can search by county to see what percentage is underwater.

We are beginning to see some softness at the super-high end of the US residential real estate market. Some of this is undoubtedly driven by foreign demand.

Morning Report: ECB disappoints, sending bond yields higher 12/3/15

Stocks are flat after the ECB cut rates again and promised more stimulus. Bonds and MBS are down.

ECB President Mario Draghi announced more quantitative easing and a cut in rates. They maintained their main rate at 0.05% and cut the deposit rate to -.3%. Apparently it wasn’t enough as bond yields are up worldwide.

Janet Yellen will be speaking in front of Congress starting at 10:00 am.

The ISM Non-Manufacturing Index fell from 59.1 to 55.9 in November, coming in well below expectations. Note the ISM Manufacturing Index also missed estimates and came in below 50, which indicates deceleration in the manufacturing sector. The employment sub-index fell, and some business owners are blaming Obamacare for higher costs.

Factory Orders rose 1.5%, a bit better than expectations, while durable goods orders were revised downward to 2.9%. Capital Goods Orders ex-defense and aircraft (a proxy for business capital expenditures) rose 1.3%.

Job cut announcements fell 13.9% to 31,000, according to outplacement firm Challenger, Gray and Christmas. This is the lowest level in over a year.

Initial Jobless Claims rose 9k to 269k. Initial Jobless Claims are still at multi-decade lows, which is amazing when you take into account population growth.

The Bloomberg Consumer Comfort index fell again last week to the lowest level in a year. Consumers are becoming more pessimistic about the economy, with 31% having a positive view and 69% having a negative view. FWIW, November same store sales are coming in this morning from the retailers, and they look to be disappointing.

Bill Gross’s latest investment outlook is out. He is advising clients to gradually de-risk their portfolios during 2016. His thesis is that years of QE have essentially hollowed out real economies as it allows zombie corporations to continue to exist and it punishes savers and insurance companies / pension funds. Of course he is talking his own book to some extent. There is no doubt that the fear of the unintended long-term consequences of ZIRP and QE are coming into play with the Fed’s plan to raise interest rates in the US.

Morning Report: ADP jobs report comes in stronger than expected 12/2/15

Markets are flat this morning as labor costs rise. Bonds and MBS are down.

Janet Yellen will be speaking at noon today.

Mortgage applications fell 0.2% last week as purchases rose 7.7% and refis fell 6%. Not bad considering last week had the Thanksgiving holiday.

The ADP employment change came in at 217k, beating Street expectations of 190k. The prior month was revised upward. The forecast for Friday’s payroll number is 200k. If we get a similar payroll number on Friday, a rate hike in two weeks will be looking like a sure thing.

Productivity increased 2.2% in the third quarter and unit labor costs rose to 1.8%. Productivity growth has been slow, and employers are having to add people. We saw something similar in the ISM report yesterday. Employment was the bright spot in an otherwise disappointing report.

The ISM New York Index fell to 60.7 from 65.8.

While auto sales didn’t meet their lofty targets yesterday, they were the best in 14 years. Volkswagen’s US sales dropped 25% however in the wake of the emissions scandal. It looked like sales accelerated through the month as well.

Home prices rose 1.0% month-over-month in October and are up 6.8% year-over-year, according to CoreLogic. They are forecasting prices to rise 5.2% next year.

Morning Report: Construction rises, manufacturing contracts 12/1/15

Stocks are higher this morning on economic strength out of Asia. Bonds and MBS are down.
Construction spending rose 1.0% in October. This is up 13% year over year. Residential construction rose 16.8% year over year, however the growth appears to be in multi-family construction, not SFR.
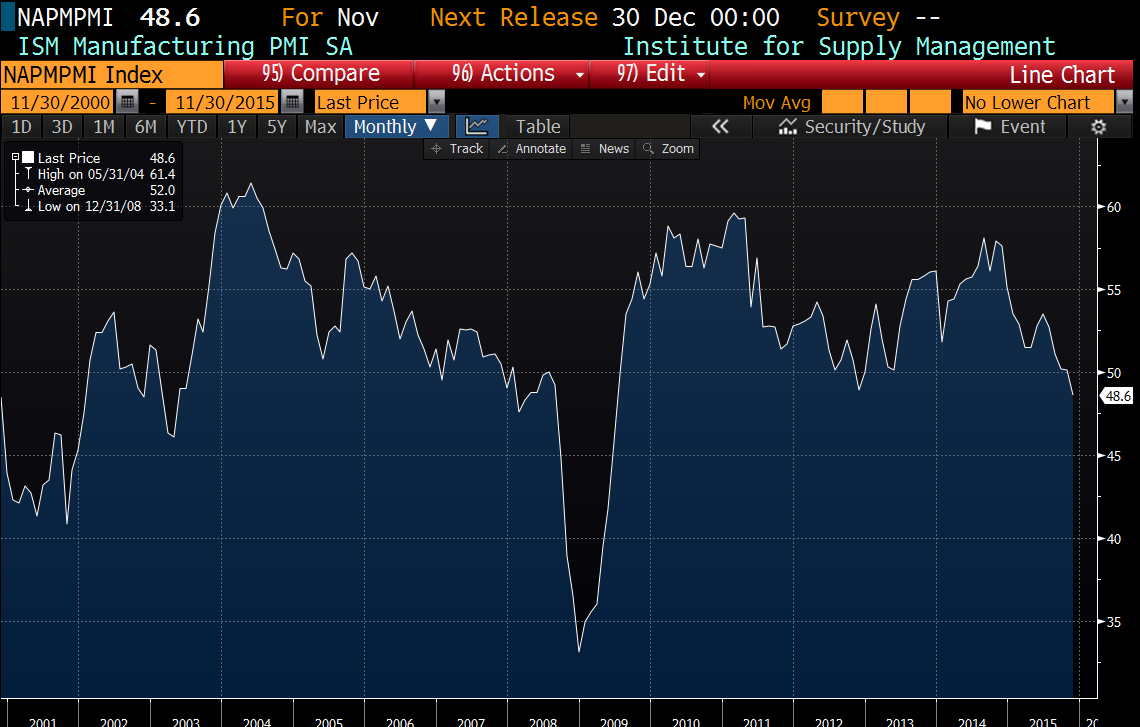
The ISM Manufacturing Index fell to 48.6 from 50.1 last month. A reading below 50 indicates that the manufacturing economy is generally contracting. This is the biggest decline since June of 2009. Inventory build is a problem, which has also been confirmed in the inventory to sales ratio. In fact, third quarter GDP was revised upward based on inventory build, however that inventory build essentially “borrows” growth from the following quarter. A reading of 48.6 would generally correspond to a GDP growth rate of about 1.7%.
Chart: ISM Manufacturing:

The weakness in manufacturing is a dollar issue, as commodity based companies and exporters are feeling the pinch. Since the US is the only economy contemplating tightening (while everyone else is deciding how much additional stimulus to put out), the dollar strength looks to continue.
Chart: US dollar index:

Vehicle sales are coming in this morning, and it looks like GM, Fiat-Chrysler, and Ford have missed their market forecasts. Most were reporting growth of about 3%. Auto loans are the new subprime.
Loews CEO and famed investor James Tisch said the Fed is “woefully behind the curve in waiting to raise rates. It should have been done years ago.” He is one of the people that is making the argument that raising rates could be positive for the economy as it will eliminate some of the misallocated capital (especially in the energy patch) and remove the penalty on savers.
Silicon Valley is attempting to disrupt the mortgage industry with a new model of non-QM, stated income loans where human interaction with the borrower is kept to a minimum. The Millennial generation generally prefers to interact with technology instead of a human. These firms are making huge investments in technology (in fact at one firm 7 or the 12 employees are IT people). They are also taking regulatory risks that many in the industry are unwilling to take. One CEO said: “There isn’t a banker out there that doesn’t look at me and shake his head and say, ‘You don’t know what you’re doing…But we’re doing it.”  They are also making a bet that the private label market will return at some point early next year. Interestingly, LOs are compensated on “customer satisfaction” and not commission.
Speaking of disruption, Morgan Stanley is laying off about a quarter of its fixed income trading team. Last year was a lousy year for fixed income trading in general, and the fee income just hasn’t been there. While the Fed has basically spoon fed rate expectations to the market, the exit of market makers will probably make the markets more volatile. Don’t forget, traders are generally young, and the majority of the ones who are left have never seen a tightening cycle before.
While Black Friday looks to have been a disappointment, initial indications suggest Cyber Monday went a little better.

Morning Report: Pending Home Sales edge up 11/30/15

Stocks are higher as market participants return from the Thanksgiving holiday. Bonds and MBS are flat.

The highlight of this week will be the jobs report on Friday. This will be the last jobs report before the December FOMC meeting. The Fed Funds futures are pricing in a 75% chance of a tightening.

The European Central Bank meets this week, which should add even more noise to interest rates later this week.

Pending Home Sales rose 0.2% in October and are up 2.1% year-over-year. Tight inventory and rising prices are crimping sales. Pending Home Sales rose the most in the Northeast, where we haven’t been seeing the torrid price appreciation we have been seeing on the West Coast.

The ISM Milwaukee manufacturing index fell to 45.3 from 46.7 last month. The Chicago Purchasing Manager index fell from 56.2 to 48.7. Again, we are seeing the stronger dollar affect manufacturing. Inventory build is a problem, and was the driver of the upward revision in Q3 GDP. We could be setting ourselves up for a letdown in Q4.

Technical issues could keep a lid on long-term yields, which should be good for mortgage rates. Due to a shrinking budget deficit, funding needs for the government are falling, and regulatory requirements have increased demand for shorter-term Treasury bills instead of longer-term bonds. Treasury bond issuance is expected to fall 33% next year to $400 billion. Some analysts are forecasting a 50% drop. This means we could be looking at a scenario where short term rates increase and longer term rates go nowhere.

As home prices rise, affordability is declining. The median house price to median income ratio is around 4.6x, which is closing in on its bubble high of almost 5x, and well above its historical range of 3.2x – 3.6x. What is driving the increase in house prices? Restricted supply has been an issue, as housing starts have been anemic since the bust. Another issue has been foreign demand, especially from China. There are a couple of things going on here. First, Chinese demand is partially driven by a desire to have dollar denominated assets, and second US policy regarding immigration. If a Chinese investor funds a development which creates US jobs, they get a green card. Chinese money which levitated prices on the West Coast is now moving inland, funding McMansion communities outside suburbs of Dallas and Chicago. Since Chinese buyers are cash-rich, they don’t need a mortgage and are winning bidding wars by offering cash.

Morning Report: GDP revised upward on inventory build 11/24/15

Markets are lower this morning after Turkey shot down a Russian plane in Syria and Brussels stays on lockdown. Bonds and MBS are up small.

The second revision to third quarter GDP came in at 2.1%, in line with estimates, and up from the initial 1.5% estimate. Personal consumption rose 3.0%, a little below expectations, while inflation was slightly higher. Inventory build accounted for a lot of the growth, which means the third quarter may have “borrowed” some growth from Q4.

Consumer Confidence took a big hit in November, falling from 97.6 to 90.4,

The Richmond Fed Manufacturing Index fall to -3 from -1 in November.

The S&P/Case-Shiller index rose .61% in September and is up 5.45% year-over-year.

The Allergan / Pfizer merger has brought out all the usual suspects jawboning about “corporate patriotism.” It is another inversion trade, where the larger Pfizer is getting bought by smaller Allergan in order for Pfizer to change its domicile to Ireland and lower its effective tax rate from 25% to 17-18%. The companies sure made themselves a target by doing this in an election year, however the reality remains: the US has the highest corporate tax rate in the world, and we double-tax foreign income, which most countries do not. Until corporate tax reform happens, these sorts of things will continue.

Morning Report: Existing Home Sales fall 11/23/15

Markets are flattish on no real news. Bonds and MBS are down.

Existing Home Sales fell to 5.36 million in October, according to the NAR. The median home price increased to 219,600. Inventories remain tight, with the number of homes for sale dropping to 2.14 million, which is about 4.8 month’s worth of inventory. 6 – 6.5 months is considered a balanced market. It doesn’t appear that TRID had much of an effect on home sales, at least so far.

The Chicago Fed National Activity Index increased to -.04 in October. This is the third negative reading in a row, and the 8th  negative month this year. Note we will get the second revision to Q3 GDP this week.

We have another big merger today, with Pfizer buying Allergan in a $160 billion inversion trade. Pfizer will become an Irish corporation for tax purposes, although the headquarters will remain in New York.

The S&P 500 is approaching its highs yet corporate profits have fallen in the second and third quarters. Blame low oil prices and the strong dollar. Of course stocks are forward-looking instruments and investors may be focusing on 2016 and beyond. Still, it is one more reason to be cautious about stocks as the Fed begins a tightening cycle. I would venture to say the majority of the traders on the Street have never witnessed one. Goldman is forecasting a 100 basis point hike in rates in 2016.

The back-to-school shopping season was somewhat disappointing for retailers as consumers remain cautious. Retailers continue to be promotional (retail-speak for “cutting prices”) and WalMart will begin its Cyber Monday sales prices on Sunday night.

Part of the issue with consumption is that homeowners are not tapping their home equity, at least the way they did before. Home equity loans are about 25% of what they were in 2007. While mortgage lenders are being more conservative, auto loans are now the new credit bubble. When you can get an 8 year car loan for about the same prices as a 30 year fixed rate mortgage, you know this has the potential to end very badly.

Morning Report: Americans are re-leveraging 11/20/15

Markets are higher this morning after Mario Draghi said the ECB will do what it must to raise inflation as quickly as possible. Bonds and MBS are rallying.

Fed Heads Bullard and Dudley will be speaking on the economy today.

Weakness in Europe has pushed bond yields down overseas, and the relative value trade should start having an effect here. The German Bund has been incredibly volatile over the past year, trading in a range of 5 basis points to 106 basis points. It currently stands at 47 basis points and looks to be headed lower.

Home sales stalled in October, according to Redfin. Sales increased 0.3%, and the median house price rose about 6% year over year. TRID probably played a role in bumping up September’s numbers and lowering October’s.

Americans are re-leveraging. Household debt reached $12 trillion in the third quarter according to the New York Fed. Mortgage debt, student loan debt and auto loans all increased. The delinquency rate for student loans is an astounding 11.6%.

Credit is loosening somewhat, according to Ellie Mae. Average FICO scored dropped a point to 722. Note that time to close a loan (46 days) did not increase in October, so if TRID is slowing down closings, it isn’t apparent in the numbers, at least not yet.

Morning Report: The Fed sets the table for a Dec rate hike 11/19/15

Stocks are higher this morning on no real news. Bonds and MBS are up.

Slow news day

Initial Jobless Claims fell to 271k last week.

The Index of Leading Economic Indicators rose in October to 0.6% from an upward-revised -0.1% in September.

The Philly Fed Business Outlook rose to 1.9 from -4.5 in October.

The Bloomberg Consumer Comfort Index slipped to 41.2 from 41.6 last week.

France has shot and killed the mastermind of the Paris terrorist attacks. Now the debate turns to Syrian refugees, which has predictably lined up as a partisan issue.

The FOMC minutes were a nonevent as there was no new information and bonds barely moved. They sound like they are going to move in December, especially since some of the economic data has improved since then.

Atlanta Fed Chairman Dennis Lockhart endorsed raising rates yesterday, provided there is no deterioration in the economy.

Morning Report: Cracks appearing in the credit markets 11/18/15

Stocks are higher this morning on no real news. Bonds and MBS are down small.

Housing starts fell from a 1.19 million average pace in September to a 1.06 million pace in October. Building Permits rose from 1.1 million to 1.15 million. Multifam starts (which is notoriously volatile) drove the decline.

Mortgage Applications rose 6.2% last week as purchases rose 11.9% and refis rose 2.3%.

We will get the FOMC minutes from the October meeting around 2:00 pm today. Not expecting any big bond market moves from it, but I wouldn’t rule anything out. Here is a rundown on what the Street is looking for.

Investors are starting to balk at the debt issues. The latest one was the financing for the Veritas / Symantec deal. Interestingly, the first indication we had a problem during the financial crisis was a deal-related bond issue that was unsold. Not predicting another 2008, but just be aware.

We are starting to see an increase in consumer credit defaults. Auto loan financing has gotten absolutely ridiculous, with companies offering 8 year car loans at 30 year fixed rate mortgage interest rates. Yet another unintended consequence of ZIRP. You can’t blame consumers for taking the money – eventually all of this central bank money printing will make its way into the inflation numbers.

FHA is trying to ease rules to financing condos. Affordable housing advocates have been pushing for these changes.. Separately, Obama has threatened to veto legislation that would increase lender protections for non-QM loans. Guess FHA lending is going nowhere as the leader in low – income / low downpayment financing.