What the @$%?! Disney buying ‘Star Wars’ maker Lucasfilm for $4.05 billion from George Lucas

Disney buying ‘Star Wars’ maker Lucasfilm for $4.05 billion from George Lucas
By Associated Press, Updated: Tuesday, October 30, 4:37 PM

LOS ANGELES — Disney is paying $4.05 billion to buy Lucasfilm Ltd., the production company behind “Star Wars,” from its chairman and founder, George Lucas. It’s also making a seventh movie in the “Star Wars” series called “Episode 7,” set for release in 2015, with plans to follow it with Episodes 8 and 9 and then one new movie every two or three years.

http://www.washingtonpost.com/business/disney-says-it-is-buying-star-wars-maker-lucasfilm-for-405-billion-from-george-lucas/2012/10/30/dc0ace18-22cc-11e2-92f8-7f9c4daf276a_story.html?hpid=z4

Storm Fallout

Here in Maryland we seem to have escaped the brunt of Hurricane Sandy but with New Jersey and New York taking the greatest damage. I was living in West Palm Beach when Hurricane Andrew sliced through south Dade County, making it twice that I have been on the fringe of major storms.

Whenever I hear of hurricanes heading for New York I always think of the cautionary tale of the Citicorp Building where the structural engineer, through a series of propitious events, discovered that the building was susceptible to collapse under certain wind conditions. The New Yorker has one of the most succinct and lucid accounts of the event.

This resulted in a crash program to remediate the building’s structure which was successfully completed before any major storm struck the building. This one example is a cautionary tale about engineering professionalism. One should always do the right thing regardless of the consequences.

And no discussion of wind and structures is complete without a reference to the Tacoma Narrows Bridge collapse which is shown in about every freshman engineering class ever.

Open post for storm and disaster stories:

Monday Open Thread 10/29/2012

On the off chance that Brent can’t do the morning report today due to the hurricane, here’s an open thread. Also, for those who haven’t seen it, I highly recommend the PBS Frontline episode on the 2012 election:

http://www.pbs.org/wgbh/pages/frontline/choice-2012/

YouTube:

[A Woefully Inadequate] Saturday Football Thread (Week 9)

Ah, apparently Michi is not posting a football thread, and apparently I did not fully credit how much I enjoyed them.  Not sure which teams need to be tracked here, but if everybody would insert their teams into the post it would be appreciated.  For the ones I know about:

Not to play favorites, I think the top game this week is ND at OU.  It should be quite a game, although I don’t really get the spread (OU by 12) unless the perception is that Jones is getting in the groove at qb and the offense finally is gelling for OU.  Boomer Sooner!

UT is at KS.  KS is living by itself in the Big 12 cellar, so have to assume UT was favored but don’t have a spread.  KS was ahead much of the game but UT pulled it out in the last minute 21-17.  Tough year for the Horns.  Mark, any insight on what’s going on here?

MSU is at #25 WI (spread WI by 5.5).  Michi, this could be a big win for your guys.

USF hosts Syracuse this evening (spread USF by 3).  Mike, is this “your” team?

BYU will play soon at GT (spread GT by 2.5).

osu is favored by 1.5 at PSU.  Hope I’m wrong, but I think this one might be a snoozer.

#22 Michigan is at NE (spread NE by 1).  This might be a pretty good game.

Not sure who among us is an MN fan, but they host Purdue which is favored by 2.

In some other Top 25 games, #2 FL at #10 GA (spread FL by 6.5) and #14 Texas Tech at #3 Kansas State (spread KSU by 7.5) might be worth a watch.  And of course unbeatens #11 Miss St at #1 AL (spread Bama by 22.5); don’t think Miss St is the one destined to pull off the upset.

So who did I miss?

And who has a World Series report?

Morning Report 10/26/12

Vital Statistics:

  Last Change Percent
S&P Futures  1403.7 -4.5 -0.32%
Eurostoxx Index 2481.1 -2.3 -0.09%
Oil (WTI) 86.11 0.1 0.07%
LIBOR 0.313 0.000 0.00%
US Dollar Index (DXY) 80.18 0.138 0.17%
10 Year Govt Bond Yield 1.78% -0.04%  
RPX Composite Real Estate Index 193.9 -0.1  

Markets are flat after a better than expected GDP report offset the earnings miss from Apple. Surprisingly, bonds and MBS are rallying on the GDP number. Not sure what to make of that.

3Q GDP came in at +2%, higher than the +1.8% expectation.  This is the “advance estimate,” which means the source data are still incomplete, so the number will be subject to two revisions.  Increases in consumption and government spending were offset by a drop in nonresidential fixed investment. 

The NAR is forecasting that home prices will increase by 3.25% in 2013 based on its survey of 50,000 real estate practitioners.  

If Obama wins re-election, Ed DeMarco’s days at FHFA are probably numbered. To overcome Republican opposition, he will probably be fired and replaced while Congress is in recess. He has continued to butt heads with the Administration over principal reductions for GSE loans.

The MR may be a casualty of Sandy next week.  Hopefully not.


Conservatives Are Easier to Disgust

Or, liberals are hard to disgust. At least, when using things traditionally considered disgusting:

Although I bet you could find that lefties had high levels of disgust towards Rush Limbaugh and Ann Coulter and Ronald Reagan. 😉

Context, context, context.

I’m not that easy to disgust, but it’s not impossible. I guess that makes me a moderate.

Being reminded that you should wash your hands apparently makes people more conservative. There’s a strategy for the GOP moving forward. Forget these commercials about Romney and Obama and whatnot. Just start bankrolling PSAs that remind people to wash their hands!

Morning Report 10/25/12

Vital Statistics:

  Last Change Percent
S&P Futures  1413.5 8.2 0.58%
Eurostoxx Index 2500.1 9.5 0.38%
Oil (WTI) 86.63 0.9 1.05%
LIBOR 0.313 -0.001 -0.32%
US Dollar Index (DXY) 79.82 -0.091 -0.11%
10 Year Govt Bond Yield 1.84% 0.05%  
RPX Composite Real Estate Index 194.1 -0.1  

Markets are stronger this morning after a strong durable goods report and a good UK GDP number. Initial Jobless Claims came in at 369k and last week was revised upward to 392k.  Capital Goods orders were flat. We had a slew of decent earnings reports this morning, and Apple will report after the close. Bonds are getting clocked on the durable goods number, with the 10 year down a point and mortgages down 10 ticks.

The Chicago Fed National Activity Index came in flat, but the 3 month moving average is still negative, indicating the economy is growing below trend.  

The FOMC statement yesterday was more or less a rehash of the prior statement.  Bond Traders who were looking for the Fed to add Treasuries to the QE mix were disappointed. The Fed noted that household spending has been advancing, while growth in fixed business investment has slowed.  Today’s durable goods and capital goods reports bear that out.  

The global slowdown is causing another round of job cuts.  This time, it is more than just Wall Street as Ford, Dow Chemical, Colgate Palmolive, AMD, and HP are all cutting staff.  The number of announced job cuts in the last 2 months is the highest since 2010.

The government is going after Bank of America for the sins of Countrywide. Needless to say, the consumer groups are delighted.  Lenders warn that credit will become even tighter. Certainly the litigation risk will get passed onto borrowers through higher rates and fees. Barney Frank believes the government should lay off JP Morgan for the sins of Bear, and claims that the government asked BOA to buy Merrill, but not Countrywide.

Whatever happened to the San Bernardino eminent domain idea?  This was the plan that involved the county taking performing underwater mortgages from the banks and forgiving principal. It appears the firestorm of criticism has caused the county to quietly table the idea.

Speaking of foreclosures, ABC News has a depressing photo essay of the foreclosure crisis.

Morning Report 10/24/12

Vital Statistics:

Last Change Percent
S&P Futures 1411.8 5.0 0.36%
Eurostoxx Index 2489.5 11.6 0.47%
Oil (WTI) 86.67 0.0 0.00%
LIBOR 0.314 -0.001 -0.32%
US Dollar Index (DXY) 80.02 0.041 0.05%
10 Year Govt Bond Yield 1.77% 0.01%
RPX Composite Real Estate Index 194.1 0.3

Stock index futures are stronger this morning after yesterday’s rout. Dow Chemical reported better than expected earnings in spite of a leaked memo that said the company was considering laying off 5% of its workforce. Facebook surprised to the upside by cracking the code on monetizing mobile. Mortgage aps dropped 12% last week.  The Markit PMI (a predictor of the ISM PMI) came in light, but still improved from Sep. Bonds and MBS are down small.

The FOMC rate decision is scheduled for 2:15 EST.  Historically the Fed has tried to stay out of the way this close to the election – in fact, the last announcement on QE (Infinity) was pushing it.  Which means the smart bet is going to be that this is a non-event.  That said, the Street is expecting some change – where the Fed adds Treasuries to its QE mix – so there is the possibility of market movement, especially MBS versus Treasuries. I wouldn’t want to be floating going into that announcement.

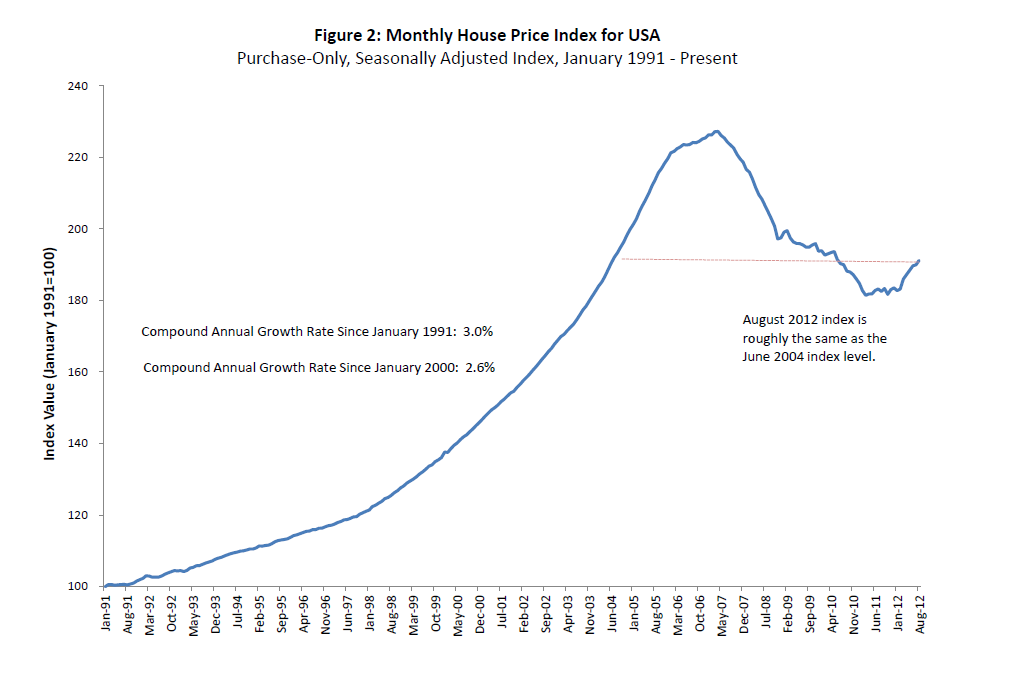
The FHFA House Price Index rose .7% in August, and is up 4.7% YOY.  This index covers only conforming mortgages, so it is less noisy than Case-Schiller or Radar Logic.

Freddie Mac’s latest US Economic and Housing Market Outlook expects QEIII to spark a further pick-up in housing activity, noting that housing has turned from a headwind to a tailwind for the economy. They are forecasting $2 trillion in originations this year, followed by a 15-20 percent contraction in 2013 as the refi boom plays out. They do worry about the fiscal cliff taking 2 percentage points out of GDP, although Obama is playing cat and mouse with the defense budget cuts, as he says one thing in the debates “cuts will not happen” and his advisers walk back the comments afterward. Elmer Fudd is quite concerned about the fiscal cliff as well.

Finally, Rob Chrisman gives you the data dump from the MBA Conference in Chicago.  Originators are adding capacity, the CFPB wants a flat fee for all mortgage originations, and the Street gets ticked when clients have the gall to check multiple dealers in order to get the best price on their TBA transactions.

Morning Report 10/23/12

Vital Statistics: 

  Last Change Percent
S&P Futures  1413.9 -16.2 -1.13%
Eurostoxx Index 2496.3 -34.9 -1.38%
Oil (WTI) 87.39 -1.3 -1.42%
LIBOR 0.315 -0.001 -0.16%
US Dollar Index (DXY) 79.85 0.202 0.25%
10 Year Govt Bond Yield 1.77% -0.04%  
RPX Composite Real Estate Index 193.9 -0.1  

Markets are lower this morning on earnings misses.  DuPont is down 5% pre-open after missing estimates badly.  Economic bulls will note that when late cyclicals like Dupont start reporting declines, that is usually an ominous sign for the expansion. UPS noted “uncertainty around the magnitude of the holiday shopping season.” Commodities are weaker as well.  Unsurprisingly, bonds and MBS are benefiting from the “risk off” trade. 

Today is another light day, economics wise, but tomorrow we get the FOMC announcement. The Street is looking for the Fed to broaden QEIII to include Treasuries.  Federal Reserve Bank of New York President William Dudley acknowledged in a recent speech that current policy “could distort asset allocations and lead to renewed financial asset bubbles. To date, there is little evidence of problems or excesses” Okay.  The 10-year is yielding 1.76%, below your stated inflation target of 2%. It makes you wonder where he would consider the 10-year to be in bubble territory.

Ever heard of “flopping?” It is the new scam where an underwater homeowner sabotages the resale value of a house in a short sale, which gets the bank to lower the asking price. The homeowner partners with a speculator who buys the property on the cheap, cleans it up, and flips it. The homeowner supposedly gets a piece of the action.

The Atlantic surveys the carnage of the lending industry from 2006 to the present.  3/4 of the biggest home lenders in 2006 no longer exist. I always thought the Super Bowl ad distribution is a tell – in the 2000 Super Bowl, the ads were dominated by dot coms.  In 2006, it was dominated by lenders. Hubris before the fall. Employment in the mortgage industry is roughly half of what it was at the height of the boom. Of course, now we have the opposite problem, with capacity constraints in the banking industry.  Of course regulatory uncertainty is playing a role, as Douglas Lebda of Lending Tree notes.

Is it really all just about price?  Financial and tech consulting firm Carlisle and Gallagher conducted a survey which revealed 34% of consumers are willing to pay more for a mortgage if it comes with superior customer service.  52% said they were willing to pay more to complete the mortgage process more easily. Note to Washington, only 23% of US consumers believe regulatory changes will have a positive impact on their next mortgage. 

Why should my vote count more than yours?

We’re two weeks away from the election, which looks like it’s going to be a nail biter. Most of you, though, needn’t bother to vote. Mark is free to make a statement with his vote, because Texas is deep red. For the time being. A California Republican is useful as an ATM, but not much more. As a resident of Virginia, my vote is being heavily courted.

The electoral college is the appendix of our constitution, prone to getting infected from time to time. As I love irony, I was hoping for Kerry to win Ohio in 2004 so that Bush would lose the presidency while winning the popular vote. Right now, Nate Silver has a 6% chance of Obama winning the election while getting fewer votes than Romney. There’s a 2% chance of the converse result. That puts the total odds at about one in twelve.

My modest suggestion would be to reform, but not eliminate, the electoral college. As every congressional district is electing a representative, one can also tally presidential votes by district. Winner of a state’s popular vote gets the bonus two electoral votes. Nebraska does it this way; I think one other state does as well. Maine, perhaps? DC gets a number of delegates that reflect its population, rounded up to an even number to eliminate the possibility of a tie. We keep the pomp and circumstance of the electoral college, but effectively it’s a popular vote.

The bonus being that certain states don’t get lavish attention. I’m not worried about all the political ads. With Virginia being a deciding state for president and senator, we get a truckload of them. I wouldn’t be surprised to find that Ohio has done very well in terms of federal contracts by being the swingiest of swing states.

As long as I’m proposing a significant change to elections, I would also suggest changing the terms of House members from 2 years to 4 years and having the entire House elected with the president. Or half and half if you’re into mid-terms. It’s interesting that the House has flipped only in mid-terms in my lifetime.

Well, I’m off to my bike. C’ya.

BB