Posted on November 21, 2014 by Brent Nyitray
Markets are higher this morning after China cut interest rates. Bonds and MBS are flat.
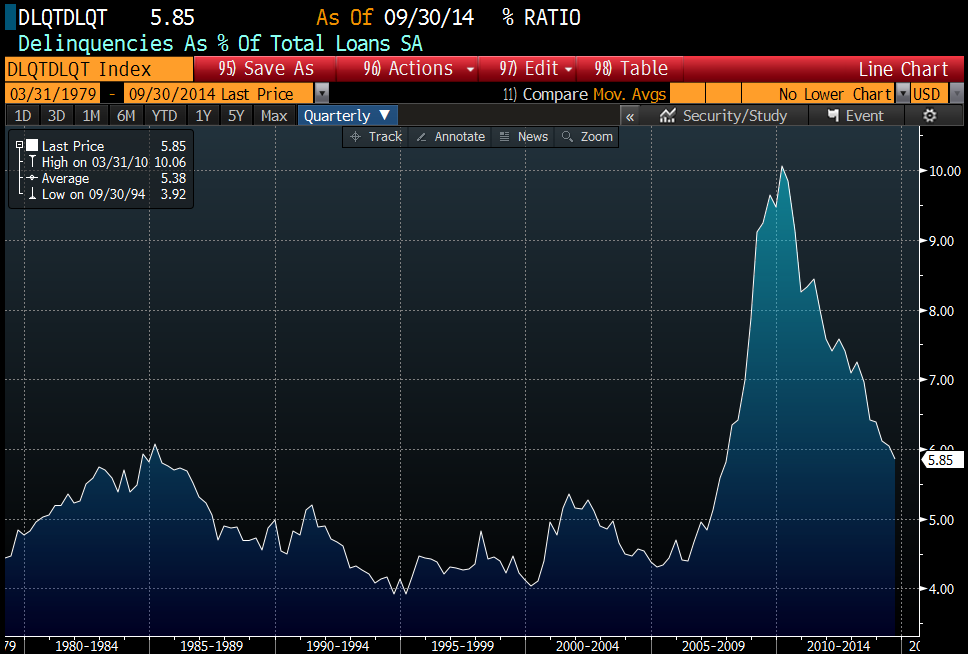
Delinquencies dropped again to 5.44% of all loans, according to Black Knight Financial Services. They are still elevated, but have quite a bit from their high of around 10%. Prior to the the bust, a typical delinquency number was about 4.5%.

Foreclosure starts declined 10% in October, and are down 31% year-over-year. Foreclosure inventory is down 33% YOY and is at the lowest level since February 2008.
The CFPB is coming down on lenders who ask too many questions about disability income in the verification process.
Filed under: Morning Report | 25 Comments »
Posted on November 20, 2014 by Brent Nyitray
Stocks are down on overseas economic weakness. Bonds and MBS are up.
Economic data dump: Initial Jobless claims came in below 300k for the 10th time this year. Lower energy prices are keeping a lid on inflation at the consumer level as the CPI came in flat. Philly Fed made a huge move upward – from 20.7 to 40.8. This is the highest reading in over 20 years. The Bloomberg Consumer Comfort Index rose to 38.5, while the Index of Leading Economic Indicators rose to 0.9%. All in all, some pretty good data this morning – surprising that bonds have taken all this in stride and are up so much.
Existing Home Sales rose to 5.26 million in October from an upward revised 5.18 million in September. They are up 2.5% on a year-over-year basis. The median home price was 208,300, which is up 5.5% from a year ago. All-cash sales increased to 27% from 24% in the prior month, but are down from 31% a year ago. Normalcy is around 20% cash sales. The first time homebuyer represented 29% of all sales. Normalcy is closer to 40%.
There was nothing earth-shattering in the FOMC minutes yesterday. Everyone agreed that QE had done its job and it was time to end it. They agreed to continue to re-invest maturing proceeds back into the market, and did not discuss suspending that or selling some of their portfolio. The staff economists tweaked their 2015 GDP estimates downward a bit. Since the October FOMC meetings don’t have a press conference of projection materials, they tend not to announce big changes. Bonds rallied on the minutes initially, but sold off to more or less end the day unch’d.
Mel Watt testified in front of the Senate Banking Committee yesterday. Elizabeth Warren laid into him about principal reductions on Fannie and Freddie loans. Mel said that reductions are still under consideration. Of course the FHFA Home Price Index (which represents homes with a conforming loan) is within 6% of the high, so if Mel continues to slow-walk principal mods, the problem eventually goes away on its own. They sound like they are bringing back the 3% down conforming loan for “targeted” borrowers.
Filed under: Morning Report | 33 Comments »
Posted on November 20, 2014 by markinaustin
Posted on November 19, 2014 by markinaustin
Posted on November 19, 2014 by Brent Nyitray
Markets are flattish this morning on no real news. Bonds and MBS are down.
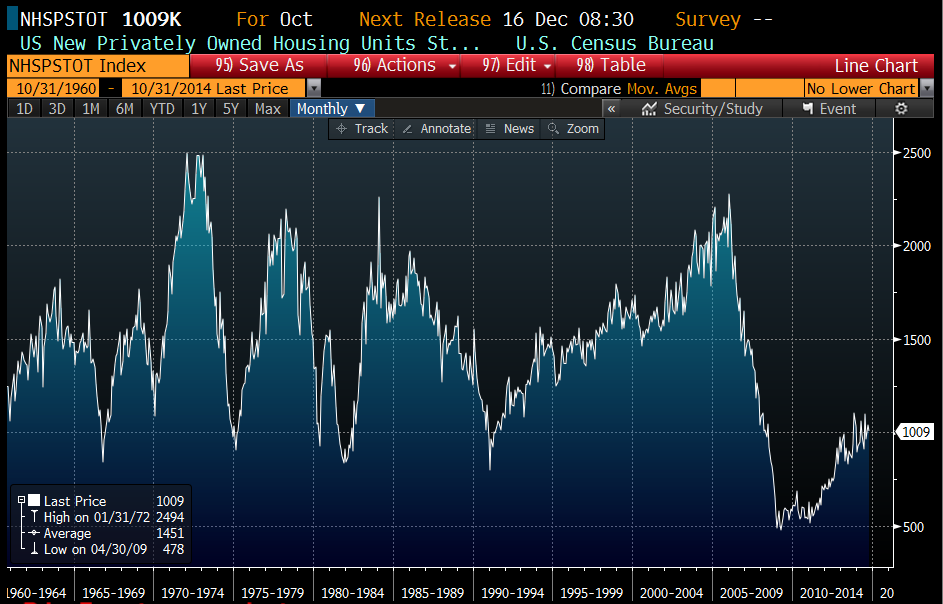
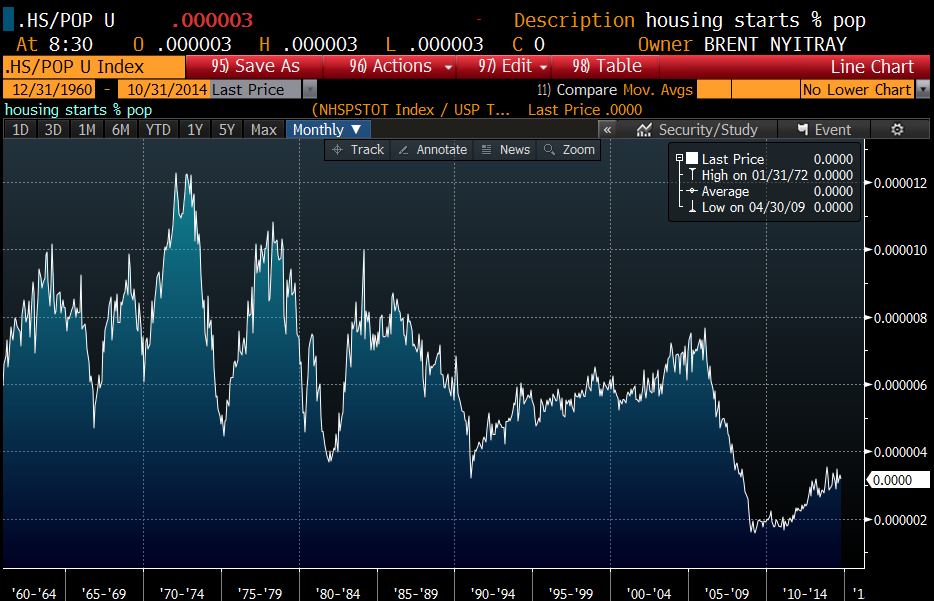
Housing starts dipped slightly to 1.01 million units, which is about 67% of “normal” levels. Single Family starts rose from 668k to 696k, while multi-fam fell from 370 to 313. Multi-fam starts are notoriously volatile, so this number isn’t as bad as it initially appears, at least from a resi building perspective. Building Permits rose to 1.08 million however. As you can see from the chart below, we are a long way from “normalcy” in housing starts. When you correct for population, Compare the chart of housing starts from 1960, and then look at the chart when you divide starts by the population:
Chart 1: Housing starts (unadjusted)

Chart 2: Housing Starts (adjusted for population):

When you take into account population growth, we have only recently touched the worst level seen in the previous 50 years. You can see how much we really under-built over the past 6 years. This represents pent-up demand that will drive the economy for years.
Mortgage Applications rose 4.9% last week. Purchases rose 11.7% while refis rose .9%. This push towards the end of the year bodes well for 2015.
Later on today, we will get the minutes from the last FOMC meeting. Key things to look for: (1) a discussion of the speed limit for the economy, particularly when discussing the labor market. The leading indicators (initial jobless claims, job openings) are at boom time levels, while the lagging indicators are still average at best. Does the Fed believe that the labor force participation rate will increase as things get better, or will it stay depressed? If it stays depressed, that means there is less slack in the labor market than appears, and wages will start to increase quicker than people are thinking. It also means less consumption however, so in effect the “speed limit” of the economy is reduced. On the other hand, if the long-term unemployed return to the labor force, wage increases may be further off in the distance, but the economy will have higher growth potential. (2) Discussions about re-investing their maturing QE securities. At the moment, they are re-investing maturing MBS and Treasuries back into the market, which turns out to be a sizeable amount of money – around $17 billion a month or so.
Filed under: Morning Report | 3 Comments »
Posted on November 17, 2014 by Brent Nyitray
Some disappointing manufacturing data this morning: Industrial production fell .1% in October, and capacity utilization fell from 79.2% to 78.9%. September’s numbers were all revised lower. The November Empire Manufacturing Index came in light as well, at 10.16.
We have some important data this week, with the manufacturing data just released, housing starts on Wed, and also the FOMC minutes. The minutes have the most potential to affect the bond markets. Those will be released Wed afternoon.
More M&A activity, with Halliburton buying Baker Hughes in a $34 billion deal, and Actavis buying Allergan in a $60 billion deal.
Housing affordability dipped slightly in the third quarter, according to the NAHB. Money quote from NAHB Chief Economist David Crowe: “Even with nationwide home prices reaching their highest level since the end of 2007, affordability still remains fairly high by historical standards, Rising employment and incomes, interest rates that remain near historically low levels, and pent-up demand should contribute to positive momentum heading into next year.”
Freddie Mac is forecasting mid single-digit home price appreciation next year and a 2.9% 10 year bond / 4.6% 30 year mortgage.
Another Gruber video is out, and it explains about how the “Cadillac Tax” was sold as a tax on only the top of the line medical plans, but it is in actuality a scheme to make all employee benefits taxable. John Kerry was given credit for this piece of newspeak genius. The idea is that the cadillac tax line of demarcation will be indexed to CPI, which is much lower than medical inflation. If medical inflation continues to outpace the CPI, eventually everyone will be subject to it. Of course employers are nominally the ones paying, but those taxes will be passed on to employees. The left has always been eager to tax employee benefits, and obamacare basically put that into law. Get used to the idea of paying taxes on your health care plan. The spin out of the Obama administration: “Who is this Gruber guy? Nobody knows him.” As the Supreme Court reviews the subsidy issue, the last thing the Administration needs is some guy from their side connecting the dots on how misdirection and newspeak was used to sell a massive government program that has never been all that popular in the first place.
Filed under: Morning Report | 38 Comments »
Posted on November 14, 2014 by Brent Nyitray
Stocks are flat this morning on no real news. Bonds and MBS are down.
Retail Sales came in strong during October, rising .3% (up.6% ex autos and gas). Retail Sales have been volatile lately, but this is certainly good news for the retailers.
Mortgage Delinquencies fell to 5.85% in the third quarter and foreclosures fell to 2.39%.
The University of Michigan Consumer Confidence Index rose to 89.4 from 86.9 last month. This is mainly due to the drop in gasoline prices, which is what these consumer confidence indices really reflect.
Import Prices fell 1.3% as the energy prices fell. The dollar rally has affected commodity prices in general, which does give the Fed room to maneuver if they want to maintain low rates.
The drop in energy prices is spurring M&A activity in the oil patch. Halliburton and Baker Hughes are in talks regarding a deal.
Obama has a new thorn in his side – a MIT economist named Jonathon Gruber who made some candid comments on the Administration’s thinking during the health care debate. Specifically, they relied on obfuscation and the general “stupidity” of the American voter to get it through. He also confessed that the “bending the cost curve” part of obamacare was simply a way to market the law to the American People and the law never intended to do that. Obamacare has never been all that popular to begin with, and this adds fuel to the fire. Given the rocky start between Republicans and Obama after the election, the politics could be interesting if the SC rules the law says what the law says and states that didn’t set up exchanges are ineligible for Medicaid subsidies. Note that Republicans truly dominate at the state levels.
Filed under: Morning Report | 4 Comments »
Posted on November 13, 2014 by Brent Nyitray
Markets are higher this morning after WalMart reported earnings that beat analyst expectations. Bonds and MBS are up small.
Initial Jobless Claims came in at 290k, an increase from the prior week, but still below 300k which is kind of the demarcation line denoting strength in the labor market. The JOLTs job openings fell to 4.7 million from 4.9 million the month before. Both initial jobless claims and the JOLT numbers are at levels that typically are seen during economic boom times (think the late 90s and the mid 00s).
This illustrates the conundrum the Fed is in with the labor market – the leading indicators (initial jobless claims and job openings) are signaling strength, while the lagging indicators (wage inflation, unemployment, labor force participation rate) have yet to reflect that strength. The open question is whether there is a skills gap (meaning companies are searching for workers that are just not there) or are we simply at an inflection point and should see big improvements over the next couple of months. How that plays out will undoubtedly be the difference between rate hikes in mid-2015 vs maybe a symbolic hike and nothing more. For the mortgage industry, if it is an issue of a skills gap, that means even a symbolic hike in the Fed Funds rate might not affect long term interest rates (in other words, the yield curve would flatten). This means mortgage rates would probably stay about where they are now. If the labor market is indeed turning around and the Fed starts hiking rates due to economic strength, long term rates (and therefore mortgage rates) are probably going up.
Regulators are drafting rules to address non-bank servicers like Ocwen and Nationstar. The biggest issues involve liquidity and solvency if we have another serious downdraft in real estate prices and loans stop performing. The nonbank servicers will probably be required to hold more cash, although it is an open question whether that would affect smaller originators who retain servicing for their own origination.
Foreclosure activity had its biggest monthly increase since 2010, according to RealtyTrac. Filings increased to 123k in October, up 15% from the prior month. This works out to 1 in every 1,069 housing units with a foreclosure filing. Note that they are talking about the biggest increase – actual foreclosure filings are down since 2010, obviously. Also, this is a seasonal blip (yes foreclosures are seasonal), as states typically impose foreclosure moratoriums around the holidays. Overall, we are seeing the judicial states work through their inventory. The expiration of the Mortgage Debt Forgiveness Act at the end of last year (which made any sort of principal forgiveness on a mortgage tax free) accounts for some of the increases we are seeing now.
Bank of America CEO Brian Moynihan said that the bank will not ease mortgage standards in spite of the exhortations out of Mel Watt and the affordable housing advocates to do so. Note that Jamie Dimon of JP Morgan also said they might get out of the FHA business. Given the fines they have had to pay, I can see how they are having difficulties making the numbers work. Too much risk for too little return.
Filed under: Morning Report | 7 Comments »
Posted on November 12, 2014 by Brent Nyitray
Stocks are down on no real news; bonds and MBS are up a few ticks.
Homebuilder D.R. Horton reported numbers yesterday, with a big increase in orders and deliveries. EPS missed Street estimates, however the stock was up on the news. Geographically, Texas, Florida, and the Carolinas are their strong areas. The company sounds optimistic about 2015, although pricing might be coming under pressure as they forecast lower gross margins in 2015. ASPs did increase, which were driven mainly by increasing house size – psf increased only by a small amount. D.R. Horton is rolling out a brand of true starter homes, with average selling prices around 170k, in anticipation of the return of the first time homebuyer. Overall, given Horton’s numbers and Toll’s pre-announcement, things may be looking up for the builders. The Spring Selling Season starts around Super Bowl Sunday.
Now for the bad news: A survey of 100 experts commissioned by Zillow says that the real estate market won’t truly recover until 2018. Blame the precarious position of the first time homebuyer.
Mortage Applications fell .9% last week, with purchases up 1.1% and refis down 1.9%.
The consensus is forming that Obama AG nominee Loretta Lynch is a civil rights type, not a Wall Street prosecutor type. Does this signal the Administration is burying the hatchet against the financial sector? Maybe. The affordable housing lobby is getting sick and tired of tight credit.
The Supreme Court agreed to hear King v Burwell – the case regarding Obamacare and subsidies. The cliff notes version of the issue concerns Medicaid subsidies to the states. The actual bill states that only states that set up exchanges are eligible for subsidies, meaning if a state didn’t set up an exchange, they cannot get Medicaid subsidies. Many states elected not to set up exchanges. Democrats are claiming this was a drafting error and they intended for everyone to get the subsidies. Republicans claim this was an incentive for states to create exchanges. If the Supreme Court rules in favor of the Democrats, nothing probably changes. If they rule in favor of Republicans, it doesn’t necessarily end Obamacare, but it would put pressure on these states to set up exchanges. Ultimately, it would probably have to go back to Congress, and Obama would have to accept some changes to Obamacare to get the language fixed. The first items likely to be discussed would be the medical devices tax, which many Democrats don’t even like, as well as the employer mandate. Ultimately that might not be enough to entice Republicans and some reduction in subsidies might be necessary, Given the 2014 results and his lack of political mojo, Obama might cut a deal to save his signature program and maintain his legacy.
Filed under: Morning Report | 6 Comments »
Posted on November 11, 2014 by markinaustin

Traditionally, a moment of silence is observed at 11 AM.
Filed under: This Day in History | 6 Comments »


 Brent Nyitray
 Fairlington Blade
 Let the mutherfuker burn!
 jnc4p
 Kevin S. Willis
 Michigoose
 lmsinca
 markinaustin
 Arcanaut
 novahockey
 quarterback
 ScottC
 yellojkt