Morning Report: The median house price hits a record 7/22/15

Stocks are lower as earnings have been generally disappointing. Bonds and MBS are up small.

Earnings season is off to a lousy start, highlighted by a miss from Apple. The stock is down 8% pre-open. IBM and United Technologies (which is selling its Sikorsky unit to Lockheed) reported disappointing earnings as well. The NASDAQ has been hitting records lately (it finally eclipsed its early 2000 high), but earnings are looking like a headwind.

Existing home sales rose 3.2% to a seasonally adjusted annual rate of 5.49 million units, the highest number in 8 years. Lawrence Yun, NAR chief economist, says backed by June’s solid gain in closings, this year’s spring buying season has been the strongest since the downturn. “Buyers have come back in force, leading to the strongest past two months in sales since early 2007,” he said. “This wave of demand is being fueled by a year-plus of steady job growth and an improving economy that’s giving more households the financial wherewithal and incentive to buy.”

Inventory remains tight as a drum, with 5.0 month’s worth of inventory, well below the 6.5 months that historically represents a balanced market. Time on market hit a record low of 34 days, down from 40 in May. The first time homebuyer represented 30% of sales, down from 32% in May and below its historical run rate of about 40%. All-cash sales fell to 22%, the lowest since December 2009.

The median house price rose to $236,400 a new record. Yes, we have surpassed the heights of the bubble years. That puts the median house price to median income ratio at a sporty 4.4x, well outside its traditional range of 3.15x – 3.6x and not far off its record of 4.8x. Either wage growth gets on its horse or further home price appreciation is going to be hard to come by.

Mortgage Applications rose 0.1% last week as purchases rose 1% and refis fell .5%. The 30 year fixed rate mortgage has been stuck at 4.23% for the last 3 weeks.

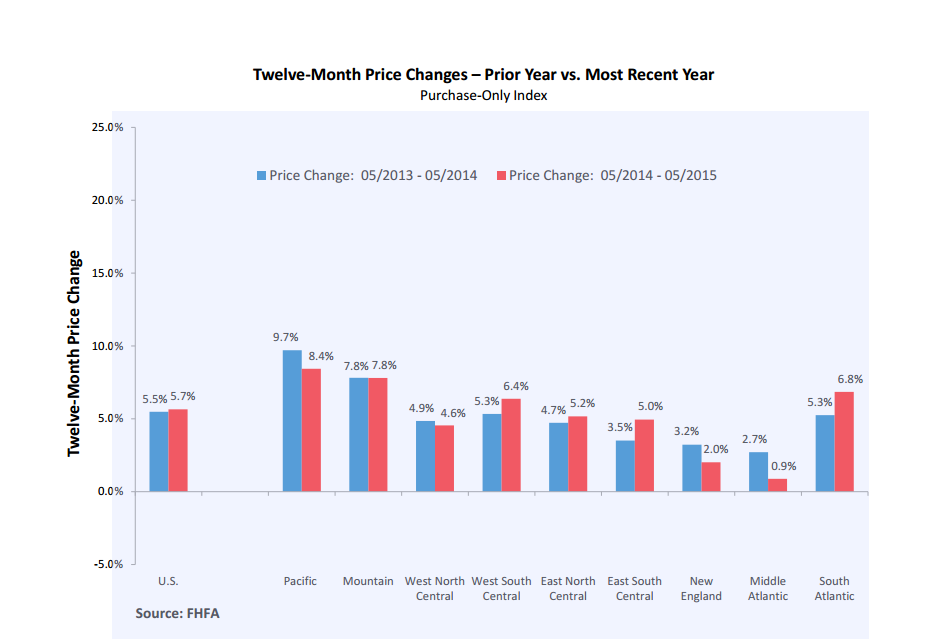
House prices rose 0.4% in May, according to the FHFA. On a year-over-year basis, prices are up 5.4%. Home prices are now about 1.8% from the peak in 2006. Note that this index only considers homes with conforming / government mortgages, so it excludes the jumbos and cash sales. While home price appreciation is accelerating nationwide, it is actually decelerating in the markets that have lagged the most – the Northeast and the Mid-Atlantic states. It has truly been a tale of two markets, with the red-hot West Coast and the ice-cold East Coast. That may be a result of increasing foreclosure activity in the Northeast / Mid-Atlantic judicial states.
Washington is looking for a way to fund infrastructure spending without raising the gasoline tax. It looks like at least one possibility would be to extend the 10bp Fannie Mae G-fee to 2025 from 2021. Banks may also see less dividend income on the shares of regional Fed bank stock they must hold.

Freddie Mac’s latest Housing Market Insight and Outlook is out, along with their forecasts for 2015 and 2016. 2015 GDP is forecast to be 2.2%, while 2016 is forecast to be 2.7%. The 30 year fixed rate mortgage is expected to be 4.0% for 2015 and 4.9% for 2016. Originations are expected to fall from 1.35T to 1.27T. They discuss why low downpayment loans are less risky now than they were in the bubble days.

Morning Report: Liquidity Issues Ahead? 7/21/15

Markets are lower this morning as earning pile in. Bonds and MBS are down small.

Dodd-Frank has severely neutered the market-making function of the banking system. When the Fed starts tightening and bonds sell off, the natural buyers of bonds (primary dealer banks) will no longer be able to dampen the moves by standing on the other side of the trade. The Fed is unconcerned about this, but we shall see what happens when rates start going up and the bond market starts falling faster than they are comfortable with.

Incidentally, Hillary will probably be forced to support a financial transactions tax, which is a tax on market-making as well. Basically it would slap a  tax on every stock trade, currency trade, and bond trade. Narrowing bid / ask spreads and a 90% drop in commission rates has basically eliminated the market-making functions (NASDAQ market makers, the specialists on the NYSE floor, block trading at banks) in the stock market. Machines are all that is left, and even they are not in the market-stabilization business. The next crash, they are going to suspend trading until things stabilize and there will be nothing but GTC (good till cancelled) buy orders for people to sell to. Washington should be careful what it wishes for.

As China’s economy cools off, and the US dollar rallies, we have seen commodities get absolutely slammed. Oil has been cut in half over the past year. Gold is in free-fall. Natural Gas is down big. This will keep a lid on inflation, and allow the Fed to keep rates lower longer.

Everyone knows that Chinese money has been behind the building boom in many large cities. This is actually driven by policy. Chinese investors who invest $500,000 and can prove that their investment created at least 10 jobs (not hard to do on a construction project) get permanent green cards. These are typically wealthy Chinese investors who are trying to get green cards for their kids and are not all that concerned about return on investment, which means dirt cheap financing for developers. Now, the government is thinking of making some changes. Obama would like these investors to put money in low-income housing, not luxury condos. Also, abuses in the program have led other to question it altogether. The program has bipartisan support so it probably isn’t going anywhere, but when you use policy as an economic lever you invariably create dislocations and marginal projects that don’t make economic sense. Something to watch.

Morning Report: Dodd-Frank 5 years on 7/20/15

Stocks are higher this morning after Greece made a payment to the ECB and re-opened its banks. Bonds and MBS are down small.

There is very little data this week – nothing today and tomorrow. We will get existing home sales on Wednesday and new home sales on Friday. Earnings season is in full swing and we will hear from heavyweights like Apple and IBM this week. Now that Greece and Chinese stocks seem to be stabilizing, I could see a gentle drift up in interest rates throughout the week.

Good housing numbers out of Census on Friday, with housing starts hitting 1.17 million and building permits hitting 1.34 million. Building Permits have risen by 200 units or so over the past two months, which portends an end to the tight supply we have been seeing in many real estate markets, which is causing bidding wars in some areas. The big improvement is largely in the Northeast, where permits are finally surpassing the levels in the West.

Chart: Building Permits: 1990 – Present

Interview with Chris Dodd and Barney Frank on Dodd-Frank 5 years later. Short summary: Dodd Frank is damn near perfect. A counter-take on it. Dodd-Frank did not end TBTF (too big to fail), however it does restrict credit, especially in mortgage banking (Barney Frank thinks D/F didn’t go far enough).

One of the unintended consequences of Dodd-Frank has been the pullback in liquidity in Treasury and corporate bond markets. Since Dodd-Frank prohibits proprietary trading, market-making has been pulled back as well, making Treasury markets more volatile, and according to studies has raised the interest rate the government pays on bonds by about 13 basis points or so. The side effect of this is that we will have more days like October 15, where Treasuries traded in a 36 basis point range as the market hit an air pocket during the day. What does this mean for LOs? Floating is going to be more dangerous.

Morning Report: Bank Earnings and Iran 7/14/15

Stocks are lower this morning after retail sales came in weaker than expected. Bonds and MBS are up.

Looks like we have a deal with Iran. Sanctions are lifted, but snap back if Iran violates any of the terms of the agreement. The immediate effect will to bring another 3 MM barrels of oil per day onto the market. Congress will have a vote on the deal.

Retail sales disappointed in June, with the headline number falling .3% versus expectations of a positive .3%. Ex autos and gas, they fell .2%, versus the .4% expectation. May strong numbers were revised down slightly. There appears to be some seasonal effects going on here (early Memorial Day “borrowed” sales from June) so don’t read too much into this number.

The NFIB Small Business Optimism Survey fell in June to 94.1 from 98.3. Weak sales and the political environment accounted for the decrease. Looks like hiring stopped in June.

Import prices fell .1% in June and are down 10% on a year-over-year basis.

Now that Tsipras has accepted the EU’s terms, he has to sell the idea back at home. Not going to be an easy task, but it will probably pass.

Hillary Clinton gave a speech yesterday on the economy, and it is more or less a grab-bag of assorted liberal ideas: increase the minimum wage, more aggressive enforcement of discrimination laws, paid family leave, free childcare, the usual.. She even went after Uber (who cheekily did a senior citizen promotion that day). It is clear she is feeling the #Bern and is worried about her left flank.

JP Morgan reported this morning that mortgage banking net income fell 20% in the quarter. Not a lot of color on mortgage banking in particular, however they are paying close attention to China (I’ll bet). The stock is up about 1 percent on the open.

Wells also reported this morning. Mortgage banking revenues fell 1% in spite of the fact that originations rose to $62 billion from $47 billion. Well’s market share fell to 13% from 28% three years ago.

Morning Report: Greece capitulates 7/13/15

Markets are higher as it looks like the Greek situation looks resolved for the time being and Chinese stocks staged another rally. Bonds and MBS are down.

Endgame continues in Greece, where Prime Minister Alexis Tsipras has agreed to bailout terms, but now must sell the agreement to his own country. The summit agreement avoided a worst-case scenario for Greece, but many of the terms of the bailout have strings attached. Dr. Cowbell is despondent over the whole episode, as the Germans are really pushing Greece hard. Memo to Tsipras: Don’t bring up the Nazis when negotiating with the Germans.

Earnings season kicks off in earnest this week, with the big banks reporting. Note the Mortgage Bankers Association Mortgage Applications index is off about 16% during the quarter, so mortgage origination numbers could be light.

We have some big economic data this week, with retail sales tomorrow, industrial production on Wed, and housing starts on Friday. Bonds should still be at the mercy of international events however.

Janet Yellen spoke on Friday and said she expects the Fed to hike rates this year, however she cited weakness in the labor market as a reason for caution. I think the Fed is determined to make at least a symbolic move to get off the zero bound, but will tighten much more gradually than it did in the past. The exit from the post stock market bubble days was pretty dramatic, about 2 percentage points a year, or 25 basis points every meeting.

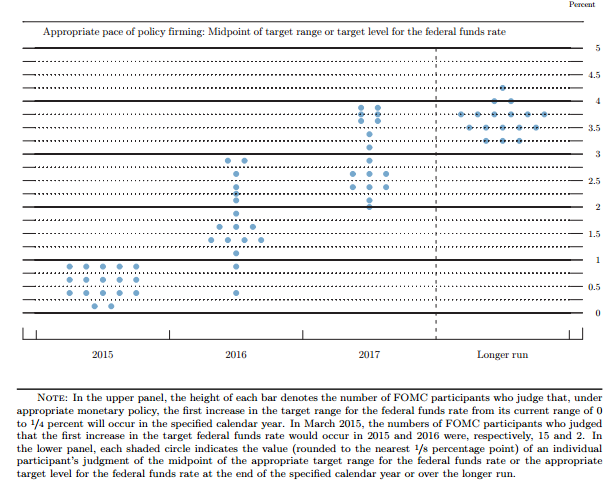
You can see from the dot graph from the June meeting that the FOMC is forecasting a slower liftoff, however we are still looking at a 350 basis point (roughly) tightening vs the 425 basis point tightening in 2004, which blew up the residential real estate bubble. Will this tightening campaign blow up the sovereign debt bubble? Or something else?

Morning Report: Mansions pile up in Greenwich 7/10/14

Markets are higher as Greece proposed a new package of spending cuts, reform, and tax increases in exchange for a new bailout. Chinese stocks rose overnight for the biggest 2-day gain since 2008. Bonds and MBS are down.

It looks like we are close to a deal to give Greece another bailout. Greece has proposed to more or less adopt the creditors’ proposals on sales and corporate tax rates. Pensions also got trimmed and the savings are more or less in line with that the creditors have wanted all along. Greece has capitulated and it looks like they will stay in the EU.

Janet Yellen will be speaking at 12:30 EST. Traders will be listening for comments regarding China and whether the melt-down there will cause the Fed to hold off raising rates.

Everywhere it seems like there is a shortage of real estate for sale. The exception is the uber-high end, especially in NYC suburbs like Greenwich, CT. At the current pace of sales, it would take 4.9 years to absorb the current inventory. Compare this to the NAR’s estimate of about 5 months nationally. IMO, there is an additional factor here – Wall Street salaries have been eroded over time as hedge funds consolidate, sales and trading jobs vanish and proprietary trading goes away. If the Chinese government orders their rich to repatriate their assets to support domestic markets, we could see more inventory in the big cities. Even if their government does not order them to repatriate, there is almost no doubt that the slowdown will affect their appetite for new properties.

Morning Report: NYSE shuts down on software error 7/9/15

There is a definite risk-on feel this morning after Chinese shares rebounded overnight. Bonds and MBS are down.

Actually a bit of a slow news day

Initial Jobless Claims rose 15k to 297,000 last week.

The FOMC minutes from the June meeting were generally taken as dovish. Housing was still characterized as “slow” and inflation remains below their target. Between Greece and China, it is hard to see how the Fed moves in September.

The New York Stock Exchange is blaming a software update for the trading suspension yesterday afternoon. Lots of people were thinking “cyber attack” yesterday.

This Sunday’s deadline for Greece might actually be a deadline. It’s “really and truly the final wake-up call for Greece, but also for us — our last chance,” EU President Donald Tusk said on Wednesday.

Wonder why so many stocks are suspended in China? It turns out many companies have been using their own stock as collateral for bank loans. These stocks have been suspended at the request of the companies themselves.

Morning Report: Don’t believe the Chinese stock market indices 7/8/15

Stocks are lower this morning as the sell-off continues in Asia. Bonds and MBS are up small.

Mortgage Applications increased 4.6% last week as purchases increased 6.6% and refis rose 2.7%. Good numbers considering last week was only 4 days.

We will get the FOMC minutes later this afternoon. The items of interest will be the big downward revision in GDP forecasts, and of course any references to Greece. The China situation really was not ripe at that point, so I don’t expect any mention there.

The EU put Greece on the clock, giving them until Saturday to come up with an agreement to stay in the EU. Europe has “a Grexit scenario prepared in detail,” European Commission President Jean-Claude Juncker said last night. Risk arbitrageurs have a term for this: showing them the downside. That is exactly what the EU is doing. The Greek ATMs are limiting withdrawals, however the Greeks have been taking out money for over 6 months, so most of them have an adequate cushion of cash at least for the time being. It won’t last forever, and the EU is pushing the Greeks to make the necessary reforms to stay in the EU. While we haven’t hit Venezuelan type shortages of goods, they are probably a month away.

Fun Chinese stock market fact: Last night the Shanghai composite fell 6%. Between the 1,331 stocks that are suspended, and the 747 shares that fell their daily 10% limit, approximately 72% of the index is non-tradeable. The A share index (which only Chinese can invest in) is down 33% since mid-June. The B share index (which foreigners can trade) is down around 43%. So when you hear someone point out that we are really only back to March levels, point out the index level is meaningless right now because 72% of the stocks aren’t trading. Oh, and the Chinese government ordered anyone with a 5% position in any company to not sell for 6 months. This is going to be a titanic battle of wills between Mr. Market and Communist Government.

Don’t forget, any economic pain in China due to the sell-off is going to be felt in commodity prices, which are already reflecting the sell-off. That will be deflationary, which the Fed fears more than inflation. IMO, unless something changes dramatically, the Fed isn’t moving in September. If they truly mean it when they say they are being data-driven, the data is screaming: wait to see what happens first. Even if they do raise the Fed Funds rate a symbolic 25 basis points, just to get off the zero bound, I don’t see how the long end of the curve moves all that much, if at all. Which means mortgage rates are probably not going to be affected.

The Obama administration has ordered HUD to re-integrate neighborhoods, using Federal funding as a carrot. LOs start thinking about FHA opportunities in areas that haven’t historically been jumbo territory. That said, I don’t know how many affluent areas get HUD grants in the first place so not sure how effective that will be. But, it might be an opportunity.

Morning Report – Chinese Stocks Collapsing 7/7/15

Markets are higher this morning as Europe and Greece still try and to seek a solution. Bonds and MBS are up.

Greece and their creditors are basically searching for a way to finance Greece’s next payment (about 3.5 billion euros) to the ECB which is due on July 20. If they default, the die is more or less cast. The final result of this negotiation will not be a bailout, but just a liquidity injection to keep things going for another month. The Greek banks have deferred tax assets and Greek government debt as their capital. They are cut off from global credit markets and have been closed to prevent a bank run. The banking system will have to be nationalized and the Greek government will have to issue some sort of scrip to pay people.

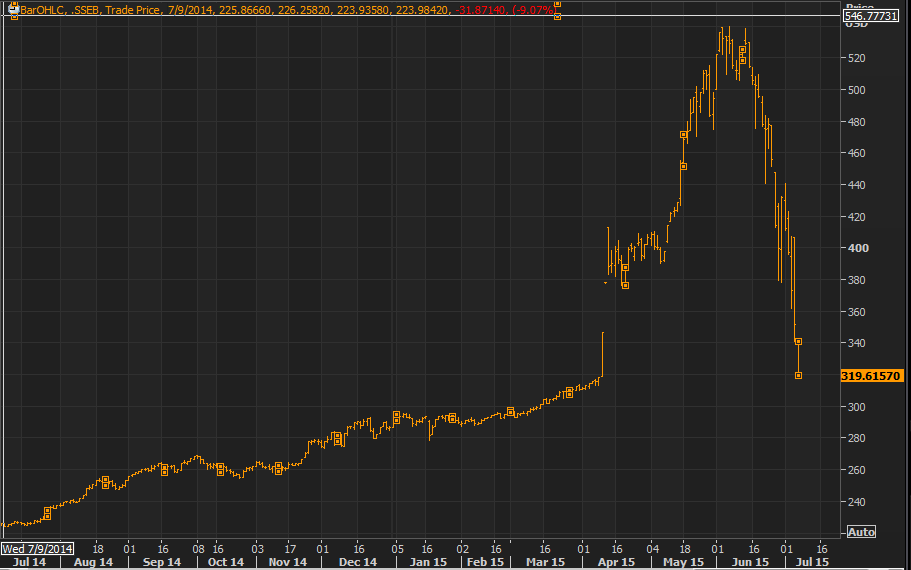
If it weren’t for the Greek Crisis, everyone would be talking about what is going on in China. Their stock market is collapsing, with the Shanghai Composite B share index down 40% in a month.  The Chinese government has been pulling out all the stops to try and support the market – cutting interest rates, increasing liquidity, creating a stock fund to buy up stocks to support the market – and none of it has been working. The Shanghia Composite B-share index dropped another 9% last night as margin traders get liquidated. To stop the selling, the Chinese government has basically suspended trading in 26% of the stocks on the Chinese exchange. Of course this does nothing but delay the inevitable. Chart: Shanghai Composite (B-shares)

Between the Greek and Chinese situations, bonds should be heading higher. We are already seeing the German Bund rally, with the yield having dropped from just over 1% to 66 basis points over the past month. Relative value trades should work US Treasuries higher as well. US investors (and loan officers) should brace themselves for a bumpy ride as the situation in Greece is hardly settled, China is a falling knife, and the Fed is in rate hike mode. Global financial stress is bond bullish, while the Fed’s posture is bond bearish. LOs, tell your borrowers they are playing with fire if they are floating.

That said, I think the overall medium term effect of the stress will be to push rates lower on the flight to safety trade. A struggling China will try and use exports to stimulate their economy, which means the US will be importing deflation. The last thing the Fed will want to do in that situation is to raise rates. As an added bonus, you could see renewed buying in MBS as investors reach for government guaranteed yield. TBA spreads to Treasuries could narrow, which means that mortgage rates could fall as fast or faster than Treasury yields. IMO, the Treasury market has been fading the moves overseas and is behind the curve.

Job openings hit 5.36 million in May, another record in the JOLTS Job Openings index. There definitely seems to be a mismatch between what employers want (someone with the wisdom of a 50 year old, the efficiency of a 40 year old, the drive of a 30 year old and the paycheck of a 20 year old) and what is actually available in the labor market.

Morning Report: Greferendum No 7/6/15

Stocks are down after Greece voted down further austerity. Bonds and MBS are up.

The jobs report last Thursday was okay for the most part. The labor force participation rate hit a new low, however.

The ISM Non-Manufacturing Index came in a little light, but was generally strong. Business Activity accelerated, however that was offset by weakening employment growth. Employment activity in the services sector has been decelerating for months.

The week after the jobs report is usually pretty data-light and this week is no exception. The highlight will be the FOMC minutes on Wednesday.

The immediate fallout of the crisis should be bond (and MBS) bullish. US stocks are down in sympathy with global markets, but there should be almost no exposure here. The ECB will probably take additional measures to boost markets via QE, so that should be stock and bond bullish here.

On to the next crisis, which is the bursting of the Chinese stock and real estate bubbles. China’s government is pulling out all the stops trying to support stock prices (the invisible hand meets the iron fist). In many ways it it reminiscent of the Japanese government in the 1990s, where they tried to artificially support markets through “price keeping operations.” Of course these measures inevitably prevent necessary adjustments from occurring, which is why Japan has stayed in economic stagnation for over a generation.

The Chinese situation has more potential to affect US markets than Greece. Chinese money is behind a lot of the price appreciation in the cities, especially at the high end. Whether it stays or goes will be dependent on what the Chinese government wants.