Morning Report: Greferendum No 7/6/15

Stocks are down after Greece voted down further austerity. Bonds and MBS are up.

The jobs report last Thursday was okay for the most part. The labor force participation rate hit a new low, however.

The ISM Non-Manufacturing Index came in a little light, but was generally strong. Business Activity accelerated, however that was offset by weakening employment growth. Employment activity in the services sector has been decelerating for months.

The week after the jobs report is usually pretty data-light and this week is no exception. The highlight will be the FOMC minutes on Wednesday.

The immediate fallout of the crisis should be bond (and MBS) bullish. US stocks are down in sympathy with global markets, but there should be almost no exposure here. The ECB will probably take additional measures to boost markets via QE, so that should be stock and bond bullish here.

On to the next crisis, which is the bursting of the Chinese stock and real estate bubbles. China’s government is pulling out all the stops trying to support stock prices (the invisible hand meets the iron fist). In many ways it it reminiscent of the Japanese government in the 1990s, where they tried to artificially support markets through “price keeping operations.” Of course these measures inevitably prevent necessary adjustments from occurring, which is why Japan has stayed in economic stagnation for over a generation.

The Chinese situation has more potential to affect US markets than Greece. Chinese money is behind a lot of the price appreciation in the cities, especially at the high end. Whether it stays or goes will be dependent on what the Chinese government wants.

Morning Report: Greece officially defaults 7/1/15

Stocks are up smartly this morning on stronger economic data and the prospect of a solution in Greece. Bonds and MBS are down.

Mortgage Applications fell 4.7% last week as interest rates spiked on the strong personal spending data. Purchase applications fell 4.1% while refis dropped 5.2%. The average 30 year fixed rate mortgage rose to 4.26%.

The ADP employment survey reported that 237k jobs were created in June, higher than the 218k forecast. The Street is forecasting a rise of 230k for the jobs report tomorrow. Challenger job cuts rose to 44k.

Fed St. Louis President James Bullard spoke last night and said the Fed should consider raising rates at the Sep meeting given the strength of the latest economic data.

Vehicle sales will be coming in all day. Early returns are disappointing.

Construction spending rose .8% in May, beating the .5% estimate. Residential construction rose .3%.

The ISM Manufacturing Index rose in June from 52.8 to 53.5. A reading over 50 indicates expansion. This is good news as the decline in oil prices had depressed activity in the oil patch. New orders and employment drove the increase. The 53.5 reading would typically correspond to a GDP growth rate of 3.3%.

Last night, Greece became the first advanced economy to officially default on an IMF loan. Most Greek banks are out of money, and pensioners who are used to getting 600 euros for the month are being given less than a quarter of that – about 120 euros. ATM deposits are being limited to 60 euros a day. The first snap poll of Greek citizens has pretty convincingly rejected the EU’s offer – 53% “no”, 33% yes.

Greece has told Europe that the latest offer comprises the basis of a compromise. The Europeans are going to wait until the results of the referendum are out on July 5. If the voters say “no” to the European demands, Greece will have no other option than to print its own currency to pay workers and pensioners. IMO, a Greek exit will be bond bullish, as it will probably force a policy response out of the ECB and that means more QE.

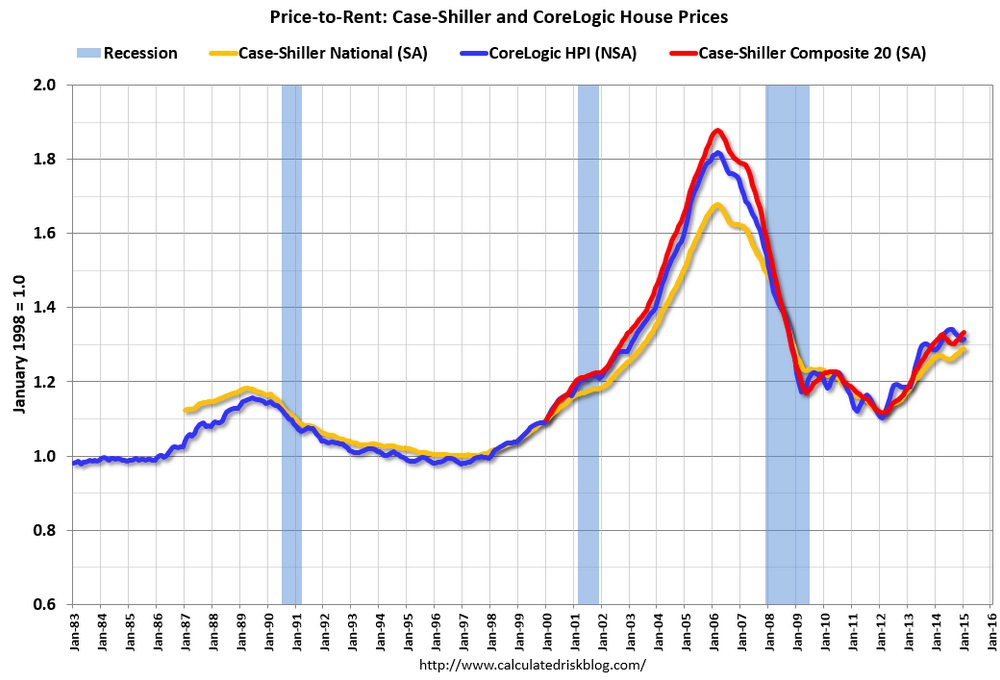
While home prices still remain affordable compared to the bubble years, low inventory has pushed up the price / rent ratio. We are back to late 2003 levels. On a nominal (in other words, non-inflation adjusted basis), prices are approaching peak levels, but on an inflation adjusted basis, they still have a ways to go. Of course wage inflation remains muted, so that will act as a drag on home price appreciation, or at least affordability.

The latest CoreLogic Market Pulse is out, and it has some good stuff on the state of the housing economy. They discuss the most overvalued housing markets, and find 4 are in Texas. Not sure how their index works, but there you go. The other ones are Washington DC (duh), Miami FL (huh?) and Charleston SC (huh?). Overall, prices nationwide appear reasonable and sustainable, with many localities still recovering from the collapse.

Morning Report – Home price appreciation is decelerating 6/30/15

Markets are higher this morning after the Chinese stock market posted an impressive turn-around and rallied 5.5% overnight on hopes the government would do more to support stock prices. Bonds and MBS are down.

Greece’s bailout expires tonight, and they are preparing for life post-bailout. The government has scheduled a referendum for 7/5 to accept or reject the austerity. Mohammed El-Arian lays out the path forward.

After the Greek situation gets resolved, attention will turn to the melt-down in China. Chinese stocks entered bear market territory (notwithstanding yesterday’s humongous rally) and a lot of this rally is being supported by dumb money – margined retail money. People are looking to the government to do something to support the markets, and it feels a lot like the Japanese market did in the 90s, where the Ministry of Finance would call the banks during the lunch break and basically tell them to tear up their sell tickets for the day.

House prices increased 4.9% year over year in April, according to Case-Shiller. Home price appreciation is decelerating as wages fail to keep up with house prices.

Consumer confidence rose to 101.4 in June, according to the University of Michigan.

Obama just increased the cost of labor by demanding that anyone who earns just less than $1,000 a week be eligible for overtime, whether they are managerial or not. The new rules will take effect in 2016. IMO, this will only accelerate the replacement of technology for labor and the Uber-ization of the economy, but I suspect Obama isn’t thinking about that. He is focused on whipping up the base, which is lukewarm with Hillary. With employment costs already soaring from regulatory mandates, I don’t see how this helps overall employment levels. I suspect this is a variation of the French mentality that limiting hours will somehow encourage more hiring. It never ceases to amaze me that the left is completely comfortable with the concept of raising the price of gasoline and cigarettes via excise taxes in order discourage consumption, but yet they somehow imagine the laws of supply and demand are suspended in the labor markets.

Morning Report: Grexit Imminent? 6/29/15

Stocks are down worldwide as Greece imposed capital controls and China enters a bear market. Bonds and MBS are up.

We have a short week coming up, with markets closed on Friday for the 4th of July. The jobs report has been moved up to Thursday. Liquidity could be lighter than normal this week as traders head to the Hamptons for a long weekend.

Greece and their creditors are at an impasse, with the Greek government scheduled a vote to determine whether to accept the creditor demands. The European Central Bank froze their Emergency Liquidity program at the same level as last week, making the Greek banks more or less insolvent. ATMs are out of money and the banks will be closed for the next six days. If they cannot get a deal with creditors, Greece will have to start printing money in order to keep the banks solvent, which would pave the way for their exit from the Euro.

While the Greek economy is only about 2% of the Eurozone (in reality, about the size of Milan or Dusseldorf) their exit will probably be bond bullish. Why? In order to support European banks which hold Greek sovereign debt, the ECB will probably announce further measures to support the banking system, and that means more QE. This will cause the Bund to rally, and relative value trading will pull the US 10 year along for the ride.

ICYMI: Puerto Rico can’t pay their debts, either.

TBAs got clobbered last week, with the Fannie TBA and the Ginnie TBA losing well over a point. This sent mortgage rates up. It may have been an overreaction to the strong personal spending data we got on Thursday, or fears of volatility over the Greek situation, but it is something to keep an eye on.

Pending Home Sales rose .9% in May, which is the highest level in over 9 years. Home Price Appreciation continues to rise about 4 times wage growth, which is an issue.

The Supreme Court ruled that the CFPB could use the “disparate impact” theory in housing discrimination cases. This was unexpected. It no longer matters whether a lender intended to discriminate, all that matters is the numbers. While the Court tried to explain that this doesn’t mean lenders just got quotas, for all intents and purposes, they just did.

Morning Report – A generation of renters? 6/24/15

Markets are lower after Greek Prime Minister Tsipras expressed shock that his proposals still do not go far enough to get a deal. Bonds and MBS are up.

Mortgage Applications rose 1.6% last week as purchases rose 1.2% and refis rose 1.8%.

The third revision to first quarter GDP came in at -0.2%. This is an upward revision from the previous -0.7% estimate. A combination of harsh weather, a West Coast port strike, and a slowdown in the oil patch depressed growth. Lower gas prices still are not translating into higher spending at the malls, however. Consumers continue to save / repay debt.

Greece was handed new terms for a bailout. The proposals Tspiras provided do not go far enough, and he took to Twitter to harangue the IMF and the EU. Brave new world: negotiating and posturing via Twitter. “There is still a lot of work to do,” Dutch Finance Minister Jeroen Dijsselbloem, who chairs meetings of his euro-area counterparts, told reporters in Brussels. “We are not there yet.”

Homeownership levels have fallen back to the levels of the early 90s. Millennials are renting in droves. Is this the new face of homownership, or simply the pendulum overcorrecting on the other side? While house prices are back in bubblicious territory (primarily due to a lack of inventory), rates are so low that mortgage payments are still comparable to rents.

Speaking of lack of inventory, homebuilding giant Lennar reported earnings this morning, beating the Street. Revenues increased 30% as deliveries increased 21% and ASPs increased to $348,000. New orders increased 18% in units as well. The stock is up about 5% pre-open. Could housing be the new engine for the economy? Hopefully, as manufacturing seems to be going through a soft patch.

Washington is alleging discrimination in REO, saying that homes in low-income neighborhoods are not being properly maintained. The problem in many of these place, especially in the rust belt, is that the opportunities are so sparse that people are moving out, and no one is moving in. When you have a net outflow of people and an endless supply of vacant houses, these properties become basically worthless. And what bank wants to throw good money after bad maintaining a house that probably will never sell in the first place?

Morning Report: New Home Sales highest in 7 years 6/23/15

Stocks are higher this morning on optimism for a Greek deal. Bonds and MBS are down.

New home sales rose 546k in May, higher than the 523k expectation and the upward-revised 534k April number. We will hear from homebuilding giant Lennar tomorrow. This is the highest number in 7 years, which will hopefully alleviate the problem of low inventory.

Durable Goods Orders fell 1.8% in May. April was revised downward from -0.5% to -1.5%. Capital Goods Orders ex defense and air (which is a proxy for business capital expenditures) rose 0.4% in May after falling a revised 0.3% in April. The low CAPEX numbers were largely driven by the decline in oil prices, which appear to have stabilized.

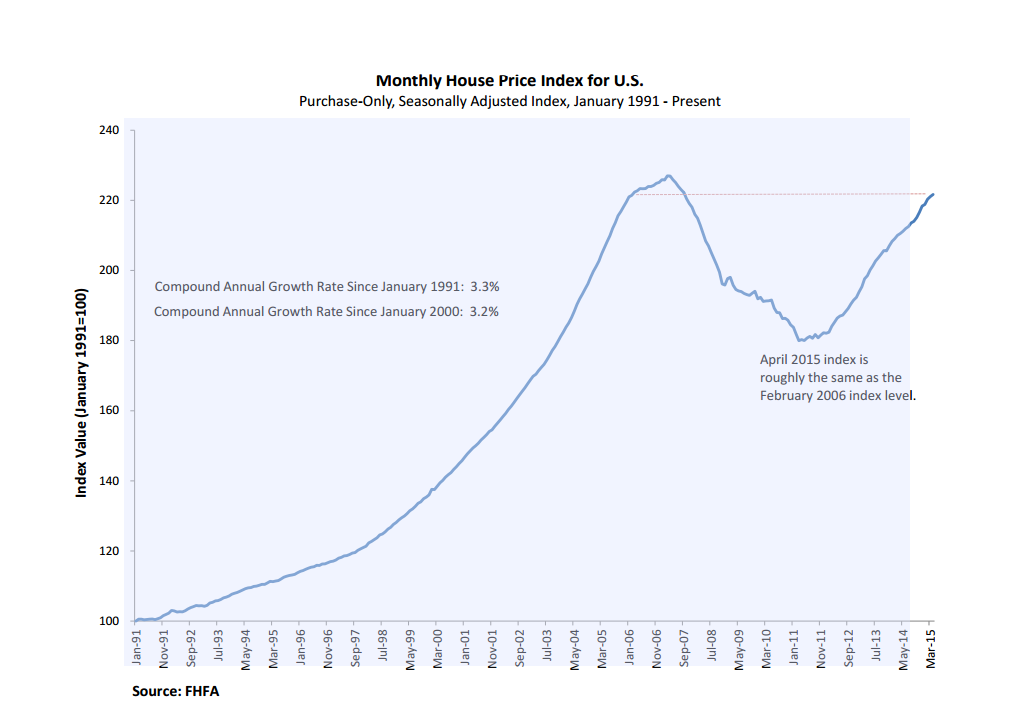
Home Prices rose 0.3% in April, according to the FHFA. The index is now roughly 2.3% below its March 2007 peak and corresponds to Feb 2006 prices. Note the FHFA index is narrower than the other indices like Case-Shiller in that it only looks at homes with a conforming mortgage. As usual, the West coast did the best, while the Northeast lagged.

Tspiras surrenders. That is the headline in Bloomberg regarding the Greek situation. Greece has more or less offered to meet the demands of their creditors. The glass of ouzo is close to being full.

Morning Report – Existing Home Sales rise 6/22/15

Markets are higher this morning after the Greek government offered a new proposal to end the standoff. Bonds and MBS are down

The Chicago Fed National Activity Index improved slightly in May to -.17. The 3 month moving average was also negative, which means the economy is growing a little below trend. Production and Consumption were negative, while employment was positive.

Merger mania in the health insurance space: Cigna rejected an offer from Anthem, and Aetna supposedly approached Humana. Insurers are looking to cut costs.

Existing Home Sales improved 5.1% to 5.35 million in May, according to the NAR. This is the highest since May 2009.  The first time homebuyer accounted for 32% of sales, up from 30% in April, but still below its historical average of about 40%. All cash transactions were flat at 24%, while days on market ticked up slightly to 40 days. The median price of a home rose 7.9% to $228,700. This puts the median home price to median income ratio at 4.3x, which is again stretched and well outside the historical norm of 3.2x – 3.6x.

In political news, the Supreme Court is supposed to rule on King vs Burwell, the case which decides whether states that did not set up exchanges are eligible for federal subsidies. This will dominate the news headlines in Washington if the Court decides the language in the law needs to be changed.

Morning Report – Endgame for Greece 6/19/15

Markets are lower after the ECB increased the size of its emergency liquidity program to Greece. Bonds and MBS are up.

No economic data today

We are getting to crunch time with Greece. Euro-area leaders are meeting Monday to try and hammer out some sort of gameplan. The ECB’s emergency liquidity package expires on June 30, which is also the day a big payment is due to the IMF. It is looking more and more likely that Greece is going to exit the Euro. While most Greek debt is owned by the Greek banking system, some is owned by the big European banks as well. Some could see a hit to their capital. This will probably be dollar (and Treasury) bullish.

Chinese stocks have been selling off, and have entered correction territory (defined as down 10%). The Chinese stock market has been in bubble territory for a while, and it looks like it is finally bursting. This market is being fueled by a toxic cocktail of margin debt and dumb money. Current margin debt is $368 billion. The market increased over 150% in one year (or about $6 trillion). While the index was higher in 2009, the Shanghai Composite P/E is currently about 95x earnings, versus 68x at the height of the 2009 market.

The bursting of the Chinese stock and real estate bubbles is going to complicate the Fed’s job of trying to normalize interest rates by causing a flight to quality in US Treasuries. The biggest headache for the Fed will be when China begins to export deflation. Inflation is still too low as far as the Fed is concerned. The biggest fear? Interest rates are already at the zero bound throughout the world, and central banks are largely out of ammunition.

Morning Report: FOMC data dump 6/18/15

Markets are higher this morning after the FOMC statement was more dovish than people had feared. Bonds and MBS are flat

The Consumer Price Index rose .4% in May, slightly below expectations. Ex-food and energy, it rose 0.1%. On a year-over-year basis, the CPI is flat, while the core index is up 1.7%. Inflation remains below the Fed’s target.

Initial Jobless Claims fell to 267,000 last week, another strong number. Real average weekly wages increased 2.3%.

The Bloomberg Consumer Comfort Index rose to 40.9 from 40.1 last week, while the Philly Fed index rose to 15.2 and the Index of Leading Economic Indicators was flat at 0.7%.

The FOMC statement was pretty much non-eventful, as was the press conference. The action was in the projection materials and the revised economic forecasts. As expected, the Fed took down its forecast for 2015 GDP growth to a range of 1.8% – 2.0% versus 2.3% – 2.7%. The Fed has been consistently high in its estimates for GDP growth ever since the crisis. It is almost as if they are trying to shoehorn an post asset bubble economy into a garden-variety Fed-driven recession model. Unemployment was taken up as well, from a range of 5.0%-5.2% to 5.2%-5.3%. We will have to wait until the minutes come out to understand the rationale there. Inflation is still expected to come in around .7%. Overall, the economy is still fragile and the Fed wants to take it slow.

The dot graph lowered the median projection for the Fed Funds rate to .7% from .9% at the March FOMC meeting, and the trajectory of interest rates is expected to be lower.

The CFPB is delaying the deadline for TRID until October, in order to give the industry a little more time. Sounds like the industry lobbied for this extension pretty hard.

We are getting a woman on the $10 bill by 2020. Jack Lew is asking for suggestions. Of course no one will be using cash anymore by 2020 anyway, and you can put whoever you want on the wallpaper on your phone…

Morning Report – Fed Day 6/17/15

Stocks are flattish this morning ahead of the FOMC decision. Bonds and MBS are down small.

The FOMC rate decision is scheduled for 2:00 pm EST today, so beware of volatility around that time. We will be getting a new set of economic projections and a new dot graph. Yellen will also hold a press conference afterward. What will investors focus on? the dot graph.

Mortgage Applications fell 5.5% last week. Purchases fell 4.2% while refis fell 6.9%.

It is looking like there might not be a deal with Greece, as Tsipras said Greece was willing to live with the consequences of saying “no” to their creditors. Bloomberg provides this helpful graph of where we are in the tug-of-war between creditors and Greece: The ouzo is definitely running out of the glass at this point

“Sell in May and Go Away” meets “Don’t fight the Fed.” A record number of investors have told BOA / Merrill Lynch that they have bought downside protection in stocks ahead of rate hikes. FWIW, I am not sure that a 50 basis point or 75 basis point Fed Funds rate is going to do that much to pull back the economy, and I think the Fed is going to take it very, very slow. This is not a typical tightening, where the Fed is trying to cool off the economy. The last thing they want to do is choke off the recovery. Second, if (when) China’s stock market bubble bursts, we could see a massive flight to quality (in other words, investors buying Treasuries) that would probably offset at least some of the effect of higher short term rates.

Barclay’s is exiting the US MBS market, following Royal Bank of Scotland’s lead. They will still trade risk sharing bonds and might still trade agency paper, but they are out of the market making business in pre-crisis paper.