Posted on January 7, 2016 by Brent Nyitray
Markets are lower again after Chinese markets got slammed down 7% overnight. Bonds and MBS are up small.
Chinese shares fell 7% in the first 30 minutes of trading and the authorities suspended trading for the rest of the day. FWIW, George Soros is comparing what is going on in China with 2008. That probably isn’t far off, given they have a real estate bubble which seems to be bursting as well.
In spite of all the volatility in the markets, we aren’t really seeing much of a bid under Treasuries, or the dollar for that matter. No big flight to safety trade. The market seems to be taking the view that any problems in China will remain contained and won’t affect the Fed’s policy of normalization. Remember, the Fed was going to hike rates in September and chose not to after the late summer sell-off, so overseas markets do matter to them.
Initial Jobless Claims fell to 277k from 287k the week before. Announced job cuts fell 28% according to outplacement firm Challenger, Gray and Christmas.
Filed under: Morning Report | 60 Comments »
Posted on January 6, 2016 by Brent Nyitray
Markets are getting slammed as China revalued the yuan at a weaker level than expected. Bonds and MBS are up on the flight to safety trade.
Mortgage Applications fell 11.6% last week as purchases fell 11% and refis fell 12%.
The ADP Employment Change came in at 257k, much better than the 198k Street expectation. Note Friday’s jobs report is forecasting an increase of 200k.
The ISM Non-Manufacturing Index fell to 55.3 from 55.9 last month.
Factory Orders fell 0.2% in November, while durable goods orders were flat. Capital Goods orders (a proxy for business capital expenditures) fell 0.3%.
Fed Vice Chairman Stanley Fischer says that 4 rate hikes this year is “in the ballpark” of what to expect. Note the FOMC minutes are scheduled to be released at 2:00 pm EST today.
Banks are taking down their estimates of Q3 GDP based on the lousy ISM data. Deutsche Bank took down Q4 to 0.5% from 1.5%. The Atlanta Fed took it down to 0.7% from 1.3%.
While inventories and exports are pushing down the GDP data, consumption seems to be turning around. 2015 was the best year for vehicle sales in the US since 2000. While some of that undoubtedly has to do with easy financing (some calling autos the new subprime) most was due to a replacement cycle that was long overdue.
Speaking of autos, GM is inventing in Lyft, the competitor to Uber. This is to have a foothold in the future of summonable driverless cars.
Filed under: Morning Report | 54 Comments »
Posted on January 5, 2016 by Brent Nyitray
Stocks are lower this morning on no real news. Bonds and MBS are flat
The ISM New York ticked up to 62 from 60.7 in December.
House prices rose 0.5% month-over-month and are up 6.3% year-over-year, according to CoreLogic. Home prices remain 7.3% below their April 2006 peak. Note the FHFA House Price Index has recouped its post-bubble losses.
The bigger question for China is what happens when their real estate bubble bursts. If that happens, 4% GDP growth may be optimistic. The reverberations will almost certainly be felt in the US real estate market, especially at the high end in the big pricey urban markets like NYC, SF, and Seattle.
After the weak ISM numbers yesterday, the Atlanta Fed took down their estimate for Q4 GDP growth from 1.3% to 0.7%.
Byron Wein’s predictions on 2016: Another down year for the S&P, the 10 year holds below 2.5% and Hillary defeats Ted Cruz. Oil stays in the 30s, and the Fed only hikes once, in March.
Filed under: Morning Report | 29 Comments »
Posted on January 4, 2016 by Brent Nyitray
Markets are getting rocked to start the new year, with China limit down overnight and Euro markets down anywhere from 2% to 4%. Bonds and MBS are up.
The ISM Manufacturing Index fell to 48.2 from 48.6 in December, which is the second month of contraction in the manufacturing sector. Blame the dollar. A 48.2 reading in the manufacturing PMI would normally be associated with GDP growth of around 1.6%.
Tensions are increasing in the Middle East, with Saudi Arabia cutting diplomatic ties with Iran over the execution of a cleric. Saudi Arabia is struggling since its economy is based on redistributing oil money and there hasn’t been a lot of oil money to redistribute lately. They may have miscalculated on trying to drive out fracking – it can be turned on and off with very little expense and time.
Filed under: Morning Report | 41 Comments »
Posted on December 30, 2015 by Brent Nyitray
Markets are lower this morning on no real news. Bonds and MBS are down small.
Not a lot going on today with New Year’s just around the corner. The MBA will be releasing mortgage application data next week, but is skipping this week.
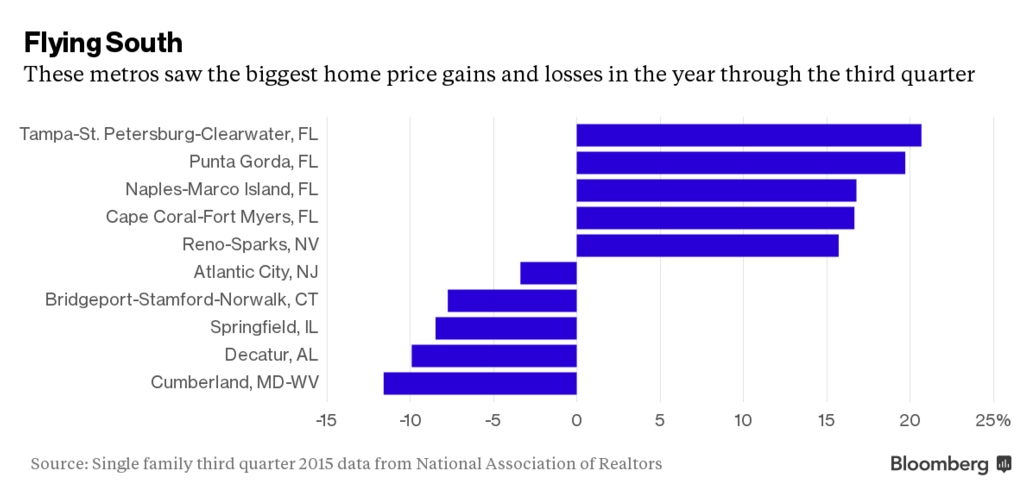
A good recap of 2015. They discuss wages, consumer confidence and real estate, with a good chart of where the action was (and wasn’t) in 2015.

Meanwhile, the IMF is predicting global growth will be disappointing in 2016. They are blaming a slowdown in China and rising rates in the US as the catalysts. Interesting theory about US rates being a drag since G7 yields have been going nowhere as US rates have risen and the spread of Treasuries to Bunds (a proxy for global interest rates) hit a record earlier this year.
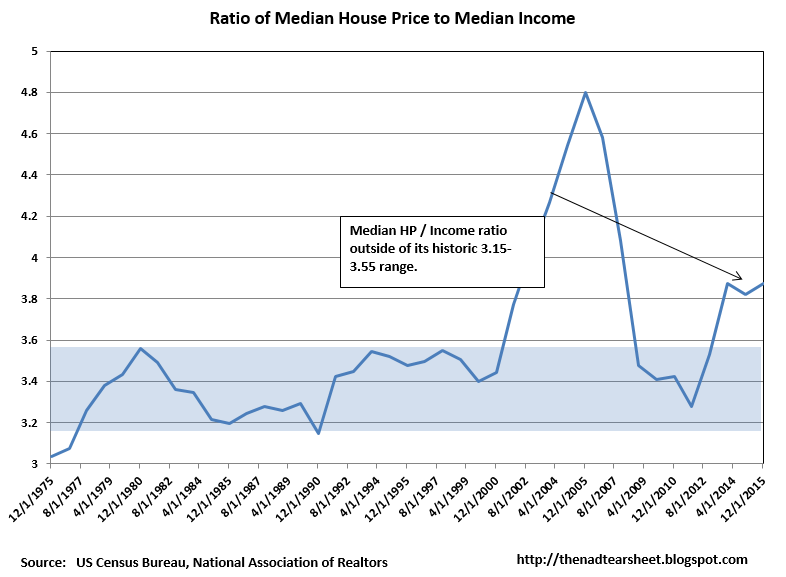
Median incomes are almost back to pre-recession levels, according to Sentier Research. The median income at the end of November was $56,888 and the median existing house price was $220,000. This puts the median income / median house price ratio to 3.87x, which is still a little elevated compared to pre-bubble years.

Filed under: Morning Report | 2 Comments »
Posted on December 29, 2015 by Brent Nyitray
Markets are higher this morning as commodities gain. Bonds and MBS are down.
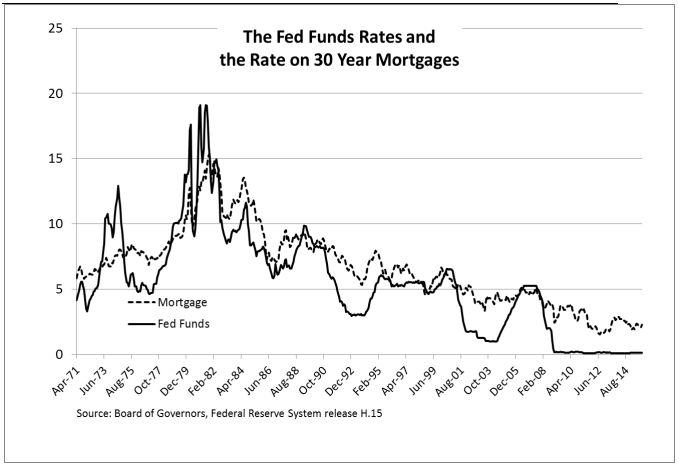
Home Prices rose 0.84% in October and are up 5.5% YOY, according to the Case-Shiller Home Price Index. Portland, San Francisco, and Denver led the charge. For those worrying about how the increase in the Fed Funds rate will affect mortgage rates, don’t worry about a 1-for-1 increase in mortgage rates as the Fed hikes rates. Note that in the 2004-2005 tightening cycle, the Fed Funds rate went from 1% to 5.25% while the average 30 year fixed rate mortgage went from 6% to 6.75%.

One thing to keep in mind, however: ARMS that are pegged to shorter-term rates like LIBOR, Fed Funds or Prime will increase as the Fed hikes short term rates. Might be a good time to pitch a switch from an ARM to a 30 year fixed.
Ever since the bubble burst, homebuilders have largely focused on the luxury end of the market and the move-up buyer. Fun fact: the average size of a new home has increased by 150 square feet since 2008. Entry-level homebuyers had been priced out of the market. Now that is beginning to change, as builders are focusing on starter homes. High land prices remain an issue.
Consumer Confidence rose from 92.6 to 96.5 in December.
Average days to close a loan increased by 3 in November, according to Ellie Mae. Blame TRID. Average FICO slipped a point to 721.
Filed under: Morning Report | 4 Comments »
Posted on December 28, 2015 by Brent Nyitray
Stocks are lower on weaker data out of China. Bonds and MBS are flat.
Not a lot of data this week, which will be shortened by the New Year’s holiday on Friday. Not sure if we get an early close on Thursday.
2015 will be remembered as the year that nothing worked. Stocks, bonds, and commodities all performed lousy. Jim Bianco explains: “The Fed stimulus lifted all boats, and then the Fed withdrawing the stimulus is holding the boats down,” Bianco said by phone. “If the argument is right that the economy is going into 2016 weak and earnings are negative, those conditions will continue and therefore on the asset allocation level, I don’t expect anything to break out just yet.”
Filed under: Morning Report | 8 Comments »
Posted on December 23, 2015 by Brent Nyitray
Stocks are up this morning on no real news. We are entering the end of year “window dressing” time where a lack of volume allows people to move stocks (at least temporarily). Bonds and MBS are down.
Big economic data dump today and tomorrow with the holiday shortened week.
Mortgage Applications rose 7.3% last week as purchases rose 4.1% and refis rose 10.8%.
New Home Sales rose to 490k from a downward revised 470k in November. Consumer sentiment rose to 92.6 from 91.8.
Personal Income and Personal Spending rose 0.3% last month.
PCE Inflation was flat on a month-over-month basis and up 0.4% YOY. The core PCE, which strips out volatile commodity related items rose 1.3% YOY. Inflation remains nowhere to be found.
Durable goods orders were flat in November, and fell 0.1% ex-transportation. Capital Goods shipments (a proxy for business capital expenditures) fell 0.5%. The Street was looking for 0.5%, so that is a big miss.
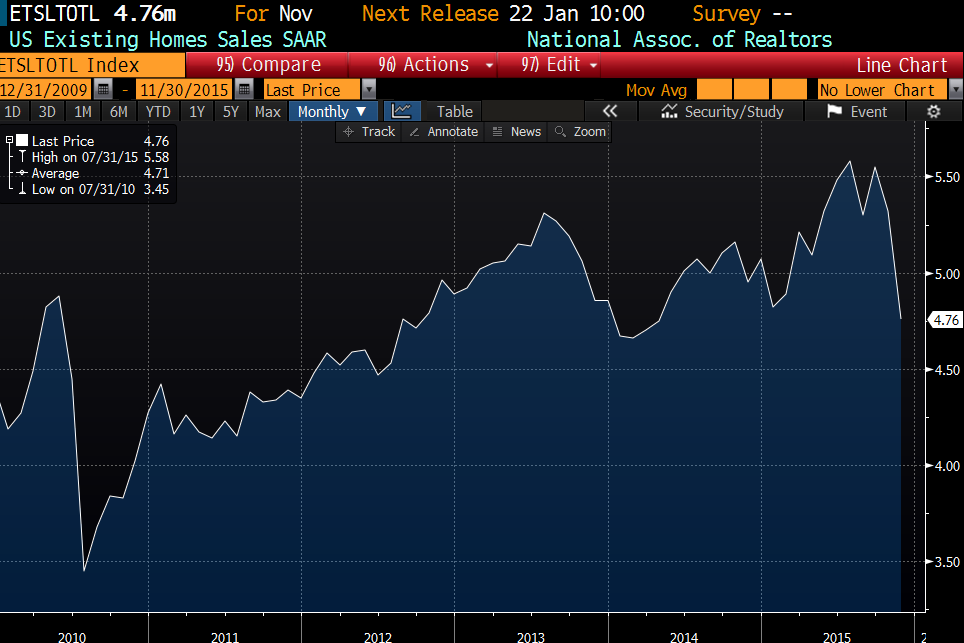
Existing Home Sales fell by a lot yesterday, which was largely attributed to TRID issues. Look at the chart – biggest drop in a long time – certainly since 2010 when the homebuyer tax credit expired.

Filed under: Morning Report | 4 Comments »
Posted on December 22, 2015 by Brent Nyitray
Stocks are higher this morning on hopes of more stimulus for the Chinese economy. Bonds and MBS are down small.
The third revision to Q3 GDP came in at 2%, a slight downward revision from the 2.1% second estimate. A lower inventory estimate drove the revision. Personal consumption was 3%, while the core PCE index (the Fed’s preferred measure of inflation) rose at an annualized rate of 1.3%. Consumption has been depressed for so long that eventually consumers are forced to replace worn out clothes and cars. The average age of a car in the US recently hit a record at 11.5 years, and this is behind the stronger auto sales (along with cheap and easy financing).
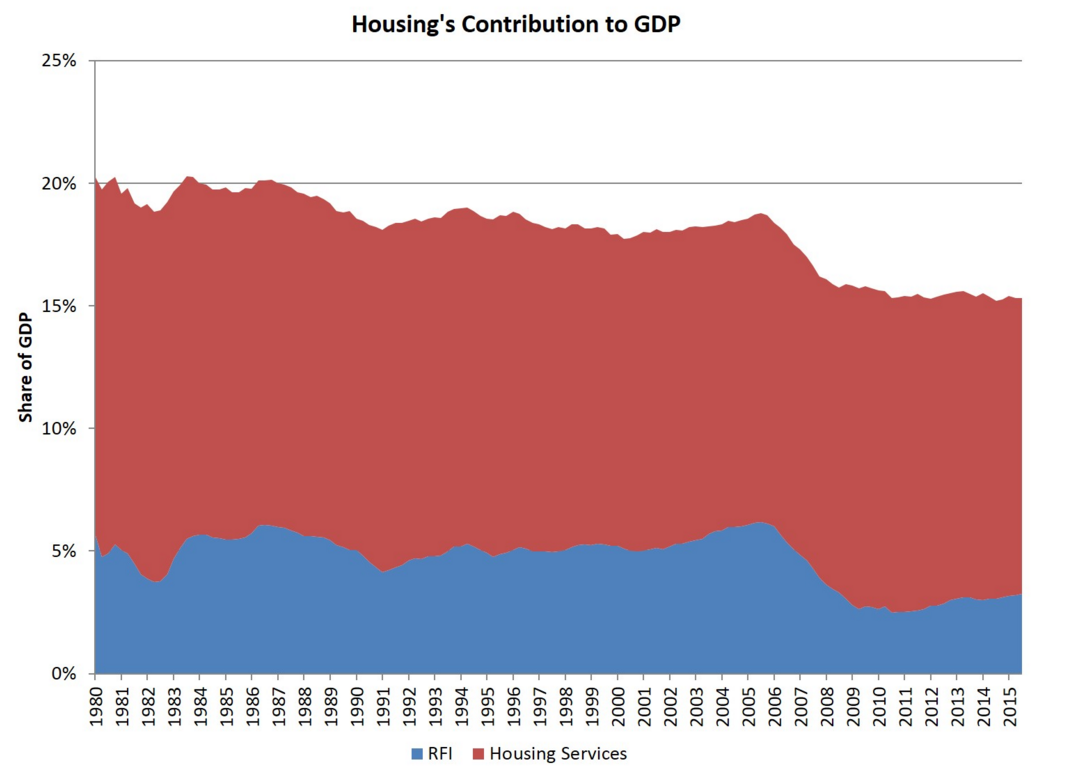
Housing contributed 15.3% of GDP in the third quarter, about where it was in the fourth quarter. This is well below the historical levels and is explained by the drop in homebuilding. Given that the excesses of the bubble were worked off years ago, inventories are tight, and the Millennial generation is even bigger than the Boomers we will see a pick-up at some point, which should last years. Remember, housing starts averaged 1.5 million a year from the 1960s to 2002 (pre-bubble years). Since 2002, we have averaged under 1.2 million. When you take into account population growth, the deficit grows even larger.

House prices rose 0.5% in October, according to the FHFA. On a year over year basis, they rose 6.1%. Looking at the chart, it seems like we are back at the heights of the index set in 2007 or so.The Mountain states led the charge, while the Northeast fell a little.
Cash sales as a percentage of home sales fell to 32.5% of all sales from 35.9% a year ago, according to CoreLogic. REO sales tend to be most likely to be cash sales. You can see on the map below the range of percentages based on the state. It looks to correlate most closely with the foreclosure pipelines.

More TRID horror stories. Borrowers are having to pay for longer lock periods, and lenders are scrambling to meet closing deadlines. Hopefully this will be a memory in a few months. Non-agency remains an even bigger problem as investors are taking a zero defects stance on TRID and not buying loans.
Filed under: Morning Report | 3 Comments »
Posted on December 21, 2015 by Brent Nyitray
Stocks are up this morning on no real news. Bonds and MBS are up small.
We have a holiday shortened week, with markets closing early on Thursday. We do get some important data with the final revision to Q3 GDP, Existing Home Sales, New Home Sales, the FHFA House Price Index, personal spending and income, and inflation. Basically a week’s worth of data crammed into 3 days.
Oil continues to fall, hitting $34.23 a barrel for WTI.
The Chicago Fed National Activity Index fell to -.3 from – .17.
Goldman is predicting a March rate hike – a “fairly easy path.” They anticipate growth will remain above trend and employment growth to be well above breakeven. Inflation will pick up as the the big swoon in oil from $100 to $50 will be a year old and won’t be pushing down the inflation numbers.
Filed under: Morning Report | 38 Comments »


 Brent Nyitray
 Fairlington Blade
 Let the mutherfuker burn!
 jnc4p
 Kevin S. Willis
 Michigoose
 lmsinca
 markinaustin
 Arcanaut
 novahockey
 quarterback
 ScottC
 yellojkt