Morning Report: GDP revised upward on inventory build 11/24/15

Markets are lower this morning after Turkey shot down a Russian plane in Syria and Brussels stays on lockdown. Bonds and MBS are up small.

The second revision to third quarter GDP came in at 2.1%, in line with estimates, and up from the initial 1.5% estimate. Personal consumption rose 3.0%, a little below expectations, while inflation was slightly higher. Inventory build accounted for a lot of the growth, which means the third quarter may have “borrowed” some growth from Q4.

Consumer Confidence took a big hit in November, falling from 97.6 to 90.4,

The Richmond Fed Manufacturing Index fall to -3 from -1 in November.

The S&P/Case-Shiller index rose .61% in September and is up 5.45% year-over-year.

The Allergan / Pfizer merger has brought out all the usual suspects jawboning about “corporate patriotism.” It is another inversion trade, where the larger Pfizer is getting bought by smaller Allergan in order for Pfizer to change its domicile to Ireland and lower its effective tax rate from 25% to 17-18%. The companies sure made themselves a target by doing this in an election year, however the reality remains: the US has the highest corporate tax rate in the world, and we double-tax foreign income, which most countries do not. Until corporate tax reform happens, these sorts of things will continue.

Apple Cranberry Currant Pie 11/24/15

My annual contrib to the meal is apple cranberry currant pie.

PREP AND COOK TIME: About 1 1/2 hours, plus at least 1 hour to cool
MAKES: 8 [adult male or teenager] servings
1/4 cup Gran Marnier [or brandy, if you are short on the good stuff]
1/4 cup currants [look like tiny raisins – you could use raisins in a pinch but they are not the same]
1 cup fresh [or thawed frozen] cranberries [I find fresh make a tarter pie – I am OK with tart]
About 1 cup granulated sugar
1/2 cup tapioca flour [I never use cornstarch in a fruit pie]
1/2 teaspoon ground nutmeg
1/2 teaspoon ground cinnamon
1/4 teaspoon salt
2 oz 1/2+1/2
6 cups sliced/chopped Granny Smith apples [about 2 1/4 lb].  I like the skin on for this pie – it’s more “rustic”.
2×9-inch pie pastry shells  – I either make my own or buy really great shells at Central Market.  When I make my own it is in no way unusual.
1. In a small bowl, combine Gran Marnier and currants. Cover and let stand until currants are plump, at least 1 hour.  [Sometimes I cheat and do not soak this long.  No biggie.  The plumpness of currants is mainly a texture deal.  Also, pre-warming the Gran Marnier quickens the plumping]
2.  Chop/slice apples, skin on, using a mix of techniques for slices and chunks.  If there will be a delay between prep and oven, put the 6 cups of apples in a big bowl and add a little OJ to keep them from browning.  LATER YOU MUST THOROUGHLY DRAIN AND PAT DRY THE APPLES!  My grandmother taught me the OJ instead of lemon juice trick about 56 years ago. 
3. Sort cranberries and discard any that are bruised or decayed. Rinse and drain berries.
4. In a large bowl, mix sugar, tapioca flour, nutmeg, and salt. With a slotted spoon, lift currants from Gran Marnier ; reserve Gran Marnier. Add currants, cranberries, and chopped apples to fructose mixture and mix well. Taste and add more fructose if desired. Pour filling into unbaked pie pastry in pan.  Cut hole pattern in top crust.  Mix 1/2+1/2 with reserved Gran Marnier and cinnamon and brush liberally on pie crust.  Carefully braid foil around pie’s edge to keep pie from from crisping-burning on crust edge that overlaps the pan during baking.  [Later, pass off the tiny pieces of foil that some guest finds in the crust edge as “healthy mineral”. :-)]
5. Bake on the bottom rack of a 375° oven until juices bubble around edges and through top holes, 55 to 65 minutes. If pie browns too quickly – check after 30 minutes – cover loosely with foil.
6. Set pie, uncovered, on a rack until cool to touch, at least 1 hour.

Morning Report: Existing Home Sales fall 11/23/15

Markets are flattish on no real news. Bonds and MBS are down.

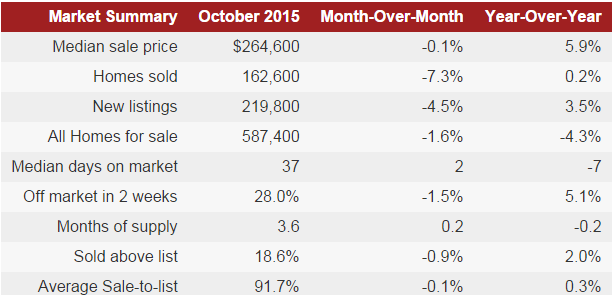
Existing Home Sales fell to 5.36 million in October, according to the NAR. The median home price increased to 219,600. Inventories remain tight, with the number of homes for sale dropping to 2.14 million, which is about 4.8 month’s worth of inventory. 6 – 6.5 months is considered a balanced market. It doesn’t appear that TRID had much of an effect on home sales, at least so far.

The Chicago Fed National Activity Index increased to -.04 in October. This is the third negative reading in a row, and the 8th  negative month this year. Note we will get the second revision to Q3 GDP this week.

We have another big merger today, with Pfizer buying Allergan in a $160 billion inversion trade. Pfizer will become an Irish corporation for tax purposes, although the headquarters will remain in New York.

The S&P 500 is approaching its highs yet corporate profits have fallen in the second and third quarters. Blame low oil prices and the strong dollar. Of course stocks are forward-looking instruments and investors may be focusing on 2016 and beyond. Still, it is one more reason to be cautious about stocks as the Fed begins a tightening cycle. I would venture to say the majority of the traders on the Street have never witnessed one. Goldman is forecasting a 100 basis point hike in rates in 2016.

The back-to-school shopping season was somewhat disappointing for retailers as consumers remain cautious. Retailers continue to be promotional (retail-speak for “cutting prices”) and WalMart will begin its Cyber Monday sales prices on Sunday night.

Part of the issue with consumption is that homeowners are not tapping their home equity, at least the way they did before. Home equity loans are about 25% of what they were in 2007. While mortgage lenders are being more conservative, auto loans are now the new credit bubble. When you can get an 8 year car loan for about the same prices as a 30 year fixed rate mortgage, you know this has the potential to end very badly.

Morning Report: Americans are re-leveraging 11/20/15

Markets are higher this morning after Mario Draghi said the ECB will do what it must to raise inflation as quickly as possible. Bonds and MBS are rallying.

Fed Heads Bullard and Dudley will be speaking on the economy today.

Weakness in Europe has pushed bond yields down overseas, and the relative value trade should start having an effect here. The German Bund has been incredibly volatile over the past year, trading in a range of 5 basis points to 106 basis points. It currently stands at 47 basis points and looks to be headed lower.

Home sales stalled in October, according to Redfin. Sales increased 0.3%, and the median house price rose about 6% year over year. TRID probably played a role in bumping up September’s numbers and lowering October’s.

Americans are re-leveraging. Household debt reached $12 trillion in the third quarter according to the New York Fed. Mortgage debt, student loan debt and auto loans all increased. The delinquency rate for student loans is an astounding 11.6%.

Credit is loosening somewhat, according to Ellie Mae. Average FICO scored dropped a point to 722. Note that time to close a loan (46 days) did not increase in October, so if TRID is slowing down closings, it isn’t apparent in the numbers, at least not yet.

Morning Report: The Fed sets the table for a Dec rate hike 11/19/15

Stocks are higher this morning on no real news. Bonds and MBS are up.

Slow news day

Initial Jobless Claims fell to 271k last week.

The Index of Leading Economic Indicators rose in October to 0.6% from an upward-revised -0.1% in September.

The Philly Fed Business Outlook rose to 1.9 from -4.5 in October.

The Bloomberg Consumer Comfort Index slipped to 41.2 from 41.6 last week.

France has shot and killed the mastermind of the Paris terrorist attacks. Now the debate turns to Syrian refugees, which has predictably lined up as a partisan issue.

The FOMC minutes were a nonevent as there was no new information and bonds barely moved. They sound like they are going to move in December, especially since some of the economic data has improved since then.

Atlanta Fed Chairman Dennis Lockhart endorsed raising rates yesterday, provided there is no deterioration in the economy.

Morning Report: Cracks appearing in the credit markets 11/18/15

Stocks are higher this morning on no real news. Bonds and MBS are down small.

Housing starts fell from a 1.19 million average pace in September to a 1.06 million pace in October. Building Permits rose from 1.1 million to 1.15 million. Multifam starts (which is notoriously volatile) drove the decline.

Mortgage Applications rose 6.2% last week as purchases rose 11.9% and refis rose 2.3%.

We will get the FOMC minutes from the October meeting around 2:00 pm today. Not expecting any big bond market moves from it, but I wouldn’t rule anything out. Here is a rundown on what the Street is looking for.

Investors are starting to balk at the debt issues. The latest one was the financing for the Veritas / Symantec deal. Interestingly, the first indication we had a problem during the financial crisis was a deal-related bond issue that was unsold. Not predicting another 2008, but just be aware.

We are starting to see an increase in consumer credit defaults. Auto loan financing has gotten absolutely ridiculous, with companies offering 8 year car loans at 30 year fixed rate mortgage interest rates. Yet another unintended consequence of ZIRP. You can’t blame consumers for taking the money – eventually all of this central bank money printing will make its way into the inflation numbers.

FHA is trying to ease rules to financing condos. Affordable housing advocates have been pushing for these changes.. Separately, Obama has threatened to veto legislation that would increase lender protections for non-QM loans. Guess FHA lending is going nowhere as the leader in low – income / low downpayment financing.

Actually, the Islamic State IS “Islamic” 11/18/15

Turns out the official line about the ISIS as proclaimed by our President (you will recall the blanket statements – not Islamic, and AQ’s junior partner) were as ignorant in their dismissiveness as they were dangerous in their denial.  This excellent Atlantic article spells out what we actually know about these militant medieval religious zealots, their appeal, and their goals.


http://www.theatlantic.com/magazine/archive/2015/03/what-isis-really-wants/384980/

Morning Report: Foreclosures continue to decline 11/17/15

Markets are higher this morning after good numbers out of Wal Mart and the Home Despot. Bonds and MBS are down.

Russia and France are going to coordinate military operations against ISIS.

Foreclosures fell to 1.88% of all homes with a mortgage in the third quarter, according to the Mortgage Bankers Association. While we are approaching normalcy, we still have a ways to go to get there. That said, I wonder how many of the homes left in foreclosure will ever sell. Many have been vacant for years and are in areas where the population is leaving.

Mortgage delinquencies fell to 4.99% from 5.3% as well.

The National Association of Homebuilders sentiment index slipped to 62 in November from 64 in October.

Inflation remains well-controlled, as the Consumer Price Index came in at 0.2% MOM in October and is up 1.9% YOY. Real average weekly earnings were up 2.1%.

Industrial production fell 0.2% in October, while manufacturing production increase 0.4%. Utilities and mining dragged down the industrial production numbers. Capacity Utilization fell to 77.5%.

Yes, house prices are approaching their 2006 highs. Do we need to worry about another bubble? The Fed says no. The bubble years were fueled by an expansion of mortgage credit, while this time around we aren’t seeing that. Two other indicators: the house price to rent ratio and mortgage debt to personal income ratios are both well below the bubble years. I have always said bubbles are a psychological phenomenon. People have to believe an asset class is “special” and cannot go down in value. That isn’t the case anymore.

Morning Report: Surprising calm in the markets 11/16/15

Markets are flattish despite the terrorist incidents in Paris over the weekend. Bonds and MBS are up small.

Not much in economic data today, but we will get some important numbers with industrial production / capacity utilization tomorrow, housing starts and building permits on Wednesday, and the FOMC minutes as well.

The Empire Manufacturing Index fell for the fourth month in a row.

The usual playbook says things like terrorism are stock bearish and bond bullish. Surprised to see so little reaction to the news. Even oil is flat. Not a lot is making sense in the bond markets these days.

To me, the most striking statistic about ISIS is this: 3 attacks (Russian airliner, Beirut suicide bombing, and Paris) in 2 weeks. These guys are stepping it up. If there is one thing markets weren’t counting on, it is a war.

The Fed Funds futures markets are still predicting a 77% chance of a rate hike at the December meeting.

Morning Report: Retail Sales disappoint 11/13/15

Stocks are lower this morning after some disappointing data and an earnings miss out of Cisco Systems. Bonds and MBS are up small.

Retail Sales rose 0.1% in October, missing estimates. The control group which strips out autos, gas and building supplies rose 0.2%, which was again below expectations. Retail sales are getting tougher to measure as more and more shopping goes on line. Many of the small online shops do not report their sales data to the government, so actual retail sales data is hard to come by.

The Producer Price Index fell 0.4% in October, which was well below expectations again. Ex-food and energy, the index was up 0.1%.

The University of Michigan Consumer Sentiment Survey increased to 93.1 from 90.

Low energy prices are a big driver of this disinflationary environment. They aren’t going away as the International Energy Association says we have 3 billion barrels in storage, which is a record. And soon we will have Iran adding to the supply.

The third quarter was the best in nearly a decade, according to the NAR. Home prices increased in 87% of all MSAs. Existing home sales are up 8.3% YOY and prices are up 5.4%. Inventory remains tight.

Citing market conditions, non-bank lender Loan Depot is postponing its IPO.