Morning Report: Home prices rise 5% 9/27/16

Vital Statistics:

Last Change
S&P Futures 2142.2 2.0
Eurostoxx Index 338.6 -1.0
Oil (WTI) 44.8 0.5
US dollar index 86.4 -0.2
10 Year Govt Bond Yield 1.56%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.47

Markets are lower this morning on no real news. Bonds and MBS are up small.

Donald Trump and Hillary Clinton had their first debate last night. Early polls are showing Hillary won, however the debates went up against Monday Night Football, so the sample is going to skew female. Major media outlets are declaring the winner based on their ideological leanings: Bloomberg says Hillary won, and the WSJ says that Trump won. Did the debate change anyone’s vote? We’ll see, but my suspicion is that people’s minds are more or less made up at this point.

Global bonds have been rallying, but the US 10 year hasn’t been following suit. The German Bund is now back at -15 basis points. Meanwhile, Blackrock is advising caution in Treasuries as the Fed starts hiking rates. Global central banks are selling Treasuries, which is putting pressure on yields.

Tim Duy says December is a good bet for another tightening, but next year’s voting members will skew more dovish than the current FOMC.

Home prices were flat month-over-month and are up 5% for the year, according to the Case-Shiller home price index. The real estate indices are beginning to show a slowdown in home price appreciation. Until we start seeing wage inflation, real estate prices will be stretched versus incomes. The labor market continues to send mixed signals.

Morning Report: New Home Sales fall 9/26/16

Vital Statistics:

Last Change
S&P Futures 2149.0 -9.0
Eurostoxx Index 340.6 -5.0
Oil (WTI) 45.0 0.5
US dollar index 86.4 -0.2
10 Year Govt Bond Yield 1.60%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.49

Markets are lower this morning on no real news. Bonds and MBS are down

Home prices rose 0.5% MOM and are up 5.8% YOY, according to the FHFA House Price Index. Home price appreciation is the highest in the West and Mountain states, while the Northeast and Middle Atlantic are bringing up the rear.

Existing Home Sales fell 0.9% in August as tight inventory depressed transactions. The median home price was just over $240,000 which was a 5.1% YOY increase. Housing inventory was down to just over 2 million homes, which is a 4.6 month supply. First time homebuyers accounted for 31% of sales. Strong job growth and low mortgage rates are pumping up demand, but builders remain reticent.

The Index of Leading Economic Indicators fell 0.2% last month, lower than expectations.

New Home Sales came in at an annualized rate of 609k, a little better than expected, but below last month’s 659k pace. The median sales price of new houses sold in August 2016 was $284,000; the average sales price was $353,600. The seasonally adjusted estimate of new houses for sale at the end of August was 235,000. This represents a supply of 4.6 months at the current sales rate.

Central Banks are dumping Treasuries, which is putting pressure on bonds, even thought the latest economic data is on the weak side. US investors (especially bond funds) are on the other side of the trade. This is also a warning to investors to take a look at their bond funds and determine how much interest rate risk they are bearing.

Minneapolis Fed Head Neel Kashkari did a Twitter Q&A about monetary policy. He is worried more about deflation than inflation and doesn’t see a bubble in housing.

Tonight, candidates Hillary Clinton and Donald Trump will have their first debate. The latest poll numbers show a dead heat, and a Trump lead when third party candidates are included. Note that the debate will be up against Monday night football, so all the post-debate polls will skew female which will be more favorable for Hillary than Trump.

Morning Report: Markets rally on the Fed 9/22/16

Vital Statistics:

Last Change
S&P Futures 2163.0 7.0
Eurostoxx Index 347.6 5.0
Oil (WTI) 46.0 0.7
US dollar index 86.1 -0.2
10 Year Govt Bond Yield 1.65%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.56

Markets are higher after the Fed maintained interest rates yesterday. Bonds and MBS are up.

The Fed kept interest rates unchanged yesterday, and released new economic projections. Most members expect the Fed to hike another 25 basis points this year according to the dot plot. They tweaked their economic projections slightly, taking down their GDP forecast for 2016 and inching up their unemployment forecast. Longer term projections were unchanged. Three members dissented, wanting to hike rates in September.

In her press conference, Janet Yellen was careful to say the Fed was confident in the economy: “Our decision does not reflect a lack of confidence in the economy, Conditions in the labor market have strengthened and we expect that to continue, and while inflation remains low we expect it to rise to our 2 percent objective over time.” She also guided that the default path was for one more rate hike this year, assuming no major changes in the economy: “I would expect to see (a rate increase this year) if we continue on the current course of labor market improvement, and there are no major risks that develop and we stay on the current course.”

Bonds rallied on the Fed’s announcement, and that is carrying over this morning as markets rally worldwide.

FWIW, Bill Gross isn’t buying that the Fed is “data dependent.” He thinks they are “market dependent.”

In other economic news this morning, initial Jobless Claims fell to 252k last week.

The Chicago Fed National Activity Index fell to -.55 last month, which confirms the slowdown we have seen in other indicators. The 3 month moving average is slightly negative, which means the economy is growing, albeit below trend.

Delinquencies and foreclosures continued to fall in August, according to Black Knight Financial Services. The rally in bonds from Brexit caused prepayments to spike, with prepayment speeds hitting a 3 year high. 4.24% of all homes are delinquent and just over 1% are in foreclosure.

Morning Report: Fed Day 9/21/16

Vital Statistics:

Last Change
S&P Futures 2137.0 7.0
Eurostoxx Index 342.9 2.0
Oil (WTI) 44.8 0.8
US dollar index 86.7 -0.2
10 Year Govt Bond Yield 1.69%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.56

Stocks are up this morning after stocks rallied overnight on moves from the Bank of Japan. Bonds and MBS are flat.

The Japanese Central Bank is embarking on a new version of QE: attempting to hold the yield of the 10 year bond precisely at 0%. The BOJ holds something like 40% of all Japanese Government bonds, and between the other players that must hold Japanese government bonds (banks for capital and insurance companies) the central bank has essentially cornered the market in bonds, and can therefore set just about any price it wants.

The FOMC decision will be out around 2:00 pm today. Bonds could get volatile around then so be careful if you have locks to deal with. The Fed Funds futures have a low 20% chance of a rate hike at today’s meeting. Note that this meeting will introduce new economic forecasts and rate forecasts, so there will be a lot that can move markets. Janet Yellen will have a press conference at 2:30 PM EST following the decision.

Mortgage applications fell 7.3% last week as purchases fell 7% and refis fell 8%.

Housing starts and building permits fell last week due to lousy weather in the South. Housing starts came in at a 1.14 million annual rate. Single family starts rose while multi-fam (which is much more volatile than SFR) fell.

KB Home and Lennar both reported earnings that beat estimates, although the orders numbers disappointed. Gross margins fell as land prices increased. Lennar reported weakness in some Texas markets due to the slowdown in the energy patch.

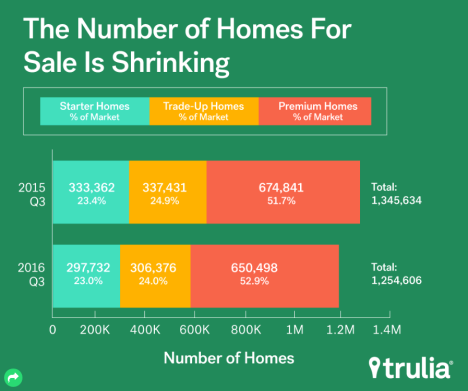
Housing inventory fell for the fifth straight quarter, according to Trulia. Affordability continues to fall as the percentage of income to buy a home continues to rise. Starter homes now require 38.5% of the typical borrower’s income, up from 36.8% in the third quarter last year. Historically, 36% has been a level where the GSEs begin to get concerned. Starter homes represent 23% of the available inventory, which is out of whack with the historical average of about 40%. The high end represents the majority of the inventory out there (which is where we are starting to see softness in pricing). We are starting to see increases in inventory in some of the West Coast markets where supply is the tightest, especially places like San Francisco and San Diego.

trulia-inventory

Wells Fargo CEO Joe Stumpf went to Washington yesterday and got scolded by the usual suspects. Although the area affected was retail lending and not mortgages, I am sure the effects will be felt in mortgage banking as well.

As banks get hammered and tied up in red tape, house flippers who need money fast are turning to crowdfunders. One flipper raised $1 million in 12 hours on crowdfunding sites RealtyShares, LendingHome, PeerStreet and Patch of Land. He is paying 14% for 2.5 year money. You are even seeing builders use this market as banks back away.

Morning Report: Inflation comes in hotter than expected 9/16/16

Vital Statistics:

Last Change
S&P Futures 2117.0 3.0
Eurostoxx Index 338.7 0.3
Oil (WTI) 43.8 0.2
US dollar index 86.7 0.0
10 Year Govt Bond Yield 1.71%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.54

Markets are up as the Bank of England maintained policy. Bonds and MBS are down.

Mortgage applications rose 4.2% last week as purchases rose 9% and refis rose 2%. The increase was driven due to a favorable comparison to the Labor Day shortened week before.

Initial Jobless Claims came in at 260k last week. Consumer comfort slipped.

Inflation remains tough to find at the wholesale level, according to the Producer Price Index. The PPI was flat month over month and year over year. Ex-food and energy it rose 0.1% last month and is up 1% YOY. The Fed prefers to use the Personal Consumption Expenditure index versus the CPI and PPI, but the Fed’s measures are in the ballpark with CPI / PPI. Neither indicator is suggesting the Fed has to hike in order to stop inflation.

Retail Sales fell 0.3% in August. Less autos and gas they fell 0.1%. While the latest GDP numbers show an increase in consumption, you aren’t seeing that in these numbers. Online shopping explains it to some extent, however August and September are the back to school shopping season, which is usually a good predictor for the holidays.

Manufacturing continues to disappoint, as industrial and manufacturing production fell 0.4% in August. Capacity Utilization slipped from 75.9% to 75.5%. Meanwhile, the Philly Fed Business Outlook rose to 12.8 while the Empire State improved to -2. July’s improvement in manufacturing looks more like a blip than a trend reversal.

Morning Report: Median incomes rise 9/15/16

Vital Statistics:

Last Change
S&P Futures 2117.0 3.0
Eurostoxx Index 338.7 0.3
Oil (WTI) 43.8 0.2
US dollar index 86.7 0.0
10 Year Govt Bond Yield 1.71%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.54

Markets are up as the Bank of England maintained policy. Bonds and MBS are down.

Mortgage applications rose 4.2% last week as purchases rose 9% and refis rose 2%. The increase was driven due to a favorable comparison to the Labor Day shortened week before.

Initial Jobless Claims came in at 260k last week. Consumer comfort slipped.

Inflation remains tough to find at the wholesale level, according to the Producer Price Index. The PPI was flat month over month and year over year. Ex-food and energy it rose 0.1% last month and is up 1% YOY. The Fed prefers to use the Personal Consumption Expenditure index versus the CPI and PPI, but the Fed’s measures are in the ballpark with CPI / PPI. Neither indicator is suggesting the Fed has to hike in order to stop inflation.

Retail Sales fell 0.3% in August. Less autos and gas they fell 0.1%. While the latest GDP numbers show an increase in consumption, you aren’t seeing that in these numbers. Online shopping explains it to some extent, however August and September are the back to school shopping season, which is usually a good predictor for the holidays.

Manufacturing continues to disappoint, as industrial and manufacturing production fell 0.4% in August. Capacity Utilization slipped from 75.9% to 75.5%. Meanwhile, the Philly Fed Business Outlook rose to 12.8 while the Empire State improved to -2. July’s improvement in manufacturing looks more like a blip than a trend reversal.

Technical analysis shows the latest rout in the bond markets resembles the taper tantrum of 2013. The long bond trade simply got too easy and too crowded. Note that mortgage rates lagged the move up in 2013. The 10 year bond yield bottomed in the spring and the Bankrate mortgage rate didn’t bottom until fall. This time, mortgage rates are increasing with the bond yields, but at a much slower pace.

Median incomes rose 5.2% in 2015, according to the Census Bureau. This is a surprising number that doesn’t really comport with what we have been seeing out of the Bureau of Labor Statistics. This number puts the median house price to median income ratio at 3.9x which is higher than the historical range of 3.2-3.6x. Low interest rates complicate the comparison, however.

Morning Report: Small Business Optimism falls 9/13/16

Vital Statistics:

Last Change
S&P Futures 2135.0 -17.0
Eurostoxx Index 314.7 -0.6
Oil (WTI) 45.1 -1.2
US dollar index 86.5 0.3
10 Year Govt Bond Yield 1.66%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.54

Markets are lower this morning as overseas stocks remain weak. Bonds and MBS are flat

Small Business confidence slipped in September according to the NFIB Small Business Optimism Index. Small business earnings are taking a hit as labor costs increase and sales growth remains muted. Small Businesses added .24 workers on average, which is the 12th monthly increase in a row and the highest reading this year. That said, job openings are falling, so we could be losing some momentum here in the future. Planned capital expenditures (another big measure of confidence) fell. Overall, as NFIB Chief Economist Bill Dunkelberg says, “Small business cannot get out of second gear.” Sentiment still remains lower than pre-recession levels and Washington remains the first and second biggest issues facing business.

Completed Foreclosures fell 3.9% MOM and 16.5% YOY, according to CoreLogic. Foreclosure inventory is down 29% to about 355,000 homes or 0.9% of all homes with a mortgage. The Northeast (especially NY and NJ) continue to have the highest level of foreclosure inventory.

Yesterday, stock rallied after Lael Brainard called for prudence in raising interest rates. The Fed now enters their quiet period until the FOMC decision next week. The Fed Funds futures are assigning a 20% probability of a rate hike in September and a 60% probability of a rate hike by December. Meanwhile, JP Morgan CEO Jamie Dimon says “just hike rates, already”

The House is expected to pass a reform of Dodd Frank today. The Senate has their own bill that has yet to be introduced. Obama will undoubtedly veto any change, but it will be on the table for the next administration. The biggest part will be providing regulatory relief to smaller entities, and bringing the CFPB under Congressional oversight.

Morning Report: Global Bond sell-off continues 9/12/16

Vital Statistics:

Last Change
S&P Futures 2111.5 -5.0
Eurostoxx Index 340.7 -5.0
Oil (WTI) 44.9 -1.0
US dollar index 86.5 0.3
10 Year Govt Bond Yield 1.68%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.48

Stocks are weaker this morning as global markets continue the sell-off that began on Friday. Bonds and MBS are lower.

Dennis Lockhart is speaking this morning, and said that it is time to have a serious discussion about raising rates. Neel Kashkari and Lael Brainard will be speaking later on today. That should be the end of Fed-speak until the FOMC meeting later this month. Fed Funds futures are now signalling a 60% chance of a rate hike by the end of the year.

So far it appears that mortgage rates are lagging the move up in sovereign yields. The same thing happened after the taper tantrum in 2013. The 10 year bottomed in spring, while mortgage rates kept falling and didn’t start rising until fall.

Donald Trump went after Janet Yellen and monetary policy, accusing the Fed of being political to protect Obama’s legacy. FWIW, it seems like there is a change in the consensus over ZIRP and whether it is causing more problems than it is solving. Not too long ago, such comments would have been treated with “How dare you!” kvetching by the press.

Certainly you are seeing the change in consensus overseas, as foreign bond markets have been selling off over the past week, with the German Bund now trading with a positive yield. Even the Japanese bond market is heading lower. Deutsche Bank lays out the scenarios going forward.

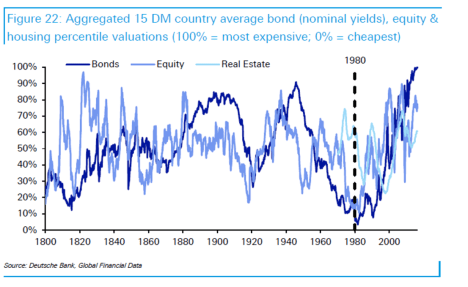
The chart below (courtesy of Deutsche Bank) looks at overvaluation / undervaluation of various asset classes over a two centuries. Bonds are extremely overvalued (we know that already), but ZIRP has also caused overvaluation in stocks and real estate, which should unwind as rates start going up. Best case scenario: a situation like the post WWII era where rates gradually crept up over the course of a few decades. Of course currencies were linked to gold back then.. Today, we are on the PhD standard where the value of paper is based on the relative value of other paper.

asset-overvaluation

It is almost as if global bond markets jumped the shark last week when Sanofi and Henkel were able to issue corporate debt at negative yields.

Morning Report: Ratio of job openings to unemployed back to pre-recession levels 9/9/16

Vital Statistics:

Last Change
S&P Futures 2159.0 -12.0
Eurostoxx Index 347.1 -2.0
Oil (WTI) 46.7 -0.9
US dollar index 86.4 0.3
10 Year Govt Bond Yield 1.65%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.52

Stocks are lower as emerging markets sell off. Bonds and MBS are down.

Risk-off feel today, but bonds aren’t rallying. What is going on? Global bond yields are increasing, especially in Japan where the BOJ is taking a breather purchasing bonds. The German Bund is down as well. Some strategists are beginning to sense that the Japanese bond market could be headed lower. So, despite weak US economic data, a global bond sell-off will affect US Treasuries as well.

Boston Fed President Eric Rosengren is sounding hawkish, which is not his natural home. His argument is that a campaign of slow, steady rate hikes will prolong the expansion more than waiting and then having to move more aggressively. Of course it all comes down to wage growth, which decelerated in the last jobs report.

Barry Ritholz took a look at the the lack of wage growth and comes up with an interesting chart: the ratio of the unemployed to the number of job openings. This ratio is back down to pre-crisis levels. While we have yet to see much evidence of increased turnover in the quits rate, it does appear at least anecdotally that we are seeing more turnover. Certainly the stage is set for further wage inflation.

jolts-to-unemployed

Mortgage credit tightened slightly in August, according to the MBA. Apparently, one investor is exiting the correspondent business and that accounted for the tightening. Credit is easing in the jumbo space however.

Morning Report: Consumers are getting more constructive 9/8/16 on the economy

Vital Statistics:

Last Change
S&P Futures 2186.5 2.0
Eurostoxx Index 350.5 1.0
Oil (WTI) 46.4 0.9
US dollar index 85.7 -0.1
10 Year Govt Bond Yield 1.54%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.52

Stocks are higher after the ECB left rates unchanged. Bonds and MBS are flat.

Initial Jobless Claims came in at 259k, We have been below 300k (an important level) for 80 weeks now.

Consumer comfort increased to 44 last week, according to Bloomberg.

Wage inflation is evident only in certain pockets of the labor economy – tech workers, engineers, construction, and remains flattish in the less skilled sectors. Elsewhere, hours are being cut and we are seeing full-timers being relegated to part-time. Until we start seeing broad-based wage inflation, the Fed is going to move slow. Note there is a disconnect between the Fed heads and what the markets are saying regarding near-term rate hikes. The markets aren’t buying the hawkish language.

Consumers are getting somewhat more constructive on the economy, according to Fannie Mae. The number of people who think the economy is on the right track improved to 38% and the number of people who think the economy is on the wrong track fell to 52%. Given the weak data recently that could be a temporary blip.