The Fed shrinks its balance sheet using this one weird trick..10/12/16

Vital Statistics:

Last Change
S&P Futures 2130.8 -4.0
Eurostoxx Index 339.6 -0.6
Oil (WTI) 50.8 0.0
US dollar index 88.4 0.1
10 Year Govt Bond Yield 1.79%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.54

Stocks are down again after getting roughed up yesterday. Bonds and MBS are down as well.

Mortgage applications fell 6% last week as purchases fell 3% and refis fell 8%.

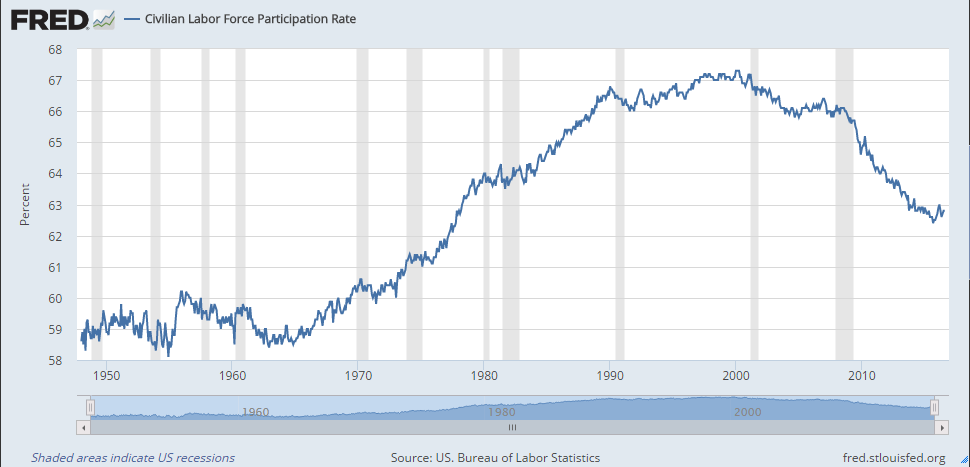
Job openings decreased by 400k to 5.4 million in August, according to the BLS. The quits rate (which is probably the best indicator for strength in the labor market) was steady at 2.1%. I wonder if we are seeing employers begin to hire the long-term unemployed, which would account for the drop in openings and the flat quits rate. The labor force participation rate is beginning to pick itself off the floor, as we saw in the latest jobs data.

We will get the FOMC minutes from the September meeting at 2:00 pm EST today. Be aware of possible market movement around then, especially if the minutes turn out to be a bit more dovish than expected. On Sunday, Fed Vice Chairman Stanley Fischer said that September’s decision to wait on hiking rates was a “close call.” The minutes will hopefully shed further light on that statement.

The biggest problem with QE is what to do with all of these assets that now sit on the Fed’s balance sheet. The Fed can’t sell the Treasuries it bought without withdrawing liquidity from the system. That would be contractionary, and the economy (or at least the financial system) might be too fragile to handle it. That would be the case even if the Fed just lets it run off by not re-investing maturing proceeds. There is now a school of thought that the Fed’s balance sheet should simply remain the size it is now, and we shouldn’t return to pre-bubble levels. The thinking is that governments should simply consolidate the Fed’s assets onto its own balance sheet. (called “permanent monetization”) Given that central banks are ultimately owned by the government, its Treasuries would effectively “cancel out” the debt issued by the government. This is why looking at the debt to GDP ratio is somewhat misleading: about a quarter of our debt is owned by the central bank. It is like taking out a loan and leaving the money in your savings account. In nominal terms, your debt is up, but your net worth is unchanged. One thing is for sure: none of this is in the econ textbooks. We are all making it up as we go along.

A Federal Appeals court ruled yesterday that the CFPB’s structure is unconstitutional. The director of the CFPB is appointed for a 5 year term, and can only be fired for cause by the President. The court found that this structure puts too much power in the hands of one person, and is more or less unaccountable. Rob Chrisman takes a look at what is going on.

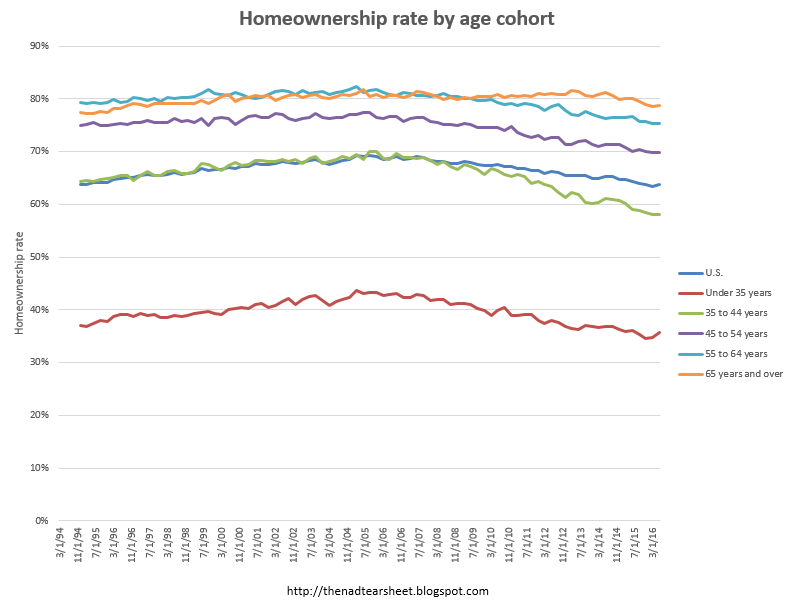
A study from the Urban Institute forecasts that the homeownership rate will continue to decline. The question ultimately rests on whether the Millennials are going to follow a different path than previous generations, or are they simply late bloomers who will eventually marry, have kids, and want a place in the suburbs. Note that the homeownership rate started going vertical in 1994, with the Clinton Administration’s policies to encourage homeownership, as a tool for social engineering. Post-crisis, the rates has returned to its previously undisturbed rate.

Morning Report: Optimism in short supply 10/11/16

Vital Statistics:

Last Change
S&P Futures 2152.8 -6.0
Eurostoxx Index 342.3 0.3
Oil (WTI) 51.0 -0.3
US dollar index 87.9 0.3
10 Year Govt Bond Yield 1.77%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.54

Stocks are up small on no real news. Bonds and MBS are down.

Alcoa kicked off Q3 earnings season with a miss. Earnings season gets into full swing next week when all the big banks announce.

While bond yields rose pretty dramatically during September, there are still $10.7 trillion worth of negative bond yields worldwide. Half of it is from Japan. The German Bund is now trading at a yield of 6 basis points.  A years’ interest on a 1 million euro Bund would cover one night at the Bayerische Hof hotel in Munich. Happy Oktoberfest.

Small business optimism dipped in September, according to the NFIB. Sentiment came in at 94.1, well below the historical 98 average. The bright spot was an improvement in economic expectations (basically improving to neutrality) while job openings and inventories fell. Small business is also firmly in maintenance capital expenditure mode, choosing not to deploy capital for expansion. The election is probably having a negative effect on sentiment as well.

Meanwhile, the US economic confidence index continues to languish in negative territory. Historically, you would see a jump in confidence around election times, as candidates promise to make things better. Not this time around, however. This also makes the Fed’s job more perilous, as they don’t want to depress what little animal spirits are out there at the moment.

Tim Duy argues that Friday’s jobs report is bad news for Fed hawks who want a December tightening. He sees November as a long shot, and December as not a foregone conclusion. Lots of wonky labor economics, but he does give you a good idea on how the Fed thinks.

Goldman is out with a “be cautious” call for the rest of the year. A vulnerable European economy, combined with high US stock prices means the market could be looking at a 2% decline over the next couple of months.

Morning Report: RIP the mortgage interest deduction? 10/10/16

Vital Statistics:

Last Change
S&P Futures 2158.0 12.0
Eurostoxx Index 341.2 1.6
Oil (WTI) 50.6 0.8
US dollar index 87.6 -0.2
10 Year Govt Bond Yield 1.72%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.54

Bonds are closed today, but overseas bond markets are weaker. Stocks are up.

No economic data today. The week after the jobs report is typically data light to begin with, and there really isn’t anything market-moving this week, except for may the PPI on Friday.

Dave Stevens of the MBA raised the issue of eliminating the mortgage interest deduction, albeit with the caveat that it be done in the context of tax reform, with lowering rates and eliminating deductions. He wasn’t advocating eliminating it in a vacuum.

If Donald Trump wins, tax reform is a definite possibility. If Hillary wins, will she be more like her husband, willing to deal with Republicans to get something done, or will she be more like Obama, where both sides had hardened positions? If you were going to eliminate the mortgage interest deduction, it will certainly make housing less affordable and would have a dampening effect on home price appreciation. That said, with rates as low as they are, interest payments as a percentage of your mortgage payment are at all-time lows. So if you wanted to eliminate it at the time when it causes the least amount of pain, now is the time to do it.

Republicans will never support eliminating deductions without cutting rates, and the historical bargain between right and left (Democrats trading increased taxes and spending for increased defense spending) might not work this time around. Believing in that trade was what got us the sequester, where Obama found his bluff called, as Republicans tolerated lower defense spending in exchange for lower discretionary spending. Given the general war fatigue of the American voter, Republicans are probably not going to be willing to trade increases in defense spending for more social spending, and certainly not for tax increases.

Punch line: the mortgage interest deduction probably isn’t going anywhere.

That said, the US subsidizes the residential real estate market six ways to Sunday, with the mortgage interest deduction, the 30 year fixed rate mortgage (try finding that anywhere else on the planet), taxpayer backing of almost all new origination, and the cornucopia of subsidies for affordable housing. Not to mention the central bank targeting of mortgage rates and real estate prices. And the powers that be still scratch their heads wondering why we had a real estate bubble…

Mortgage credit availability improved in September, according to the MBA.

Morning Report: Decent jobs report 10/7/16

Vital Statistics:

Last Change
S&P Futures 2156.0 -1.0
Eurostoxx Index 340.7 -2.0
Oil (WTI) 50.2 -0.3
US dollar index 87.7 0.0
10 Year Govt Bond Yield 1.76%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.54


Stocks are flat this morning after an ok jobs report. Bonds and MBS are down.
Jobs report data dump:
  • Nonfarm payrolls increased by 156,000 (August revised upward)
  • Unemployment rate 5%
  • Labor Force Participation Rate 62.9%
  • Average weekly earnings up 0.2% (2.6% annually)
  • Average weekly hours 34.4
Overall, a decent report, but nothing to write home about. The best news in the report was the increase in the participation rate as the labor force increased by about 440k while the number of employed increased by about 350k. The labor force participation rate looks like it may have bottomed, at least for now.

Global sovereign debt continues its sell-off, with the German Bund venturing back into positive yield territory. Overnight we had a flash crash in the British pound, which fell 6%. For currency traders, a 6% move is gargantuan.
We will have a lot of Fed-speak today, with Stanley Fischer at 10:30, Loretta Mester at 12:45, Esther George at 3:00 pm and Lael Brainard at 4:00.
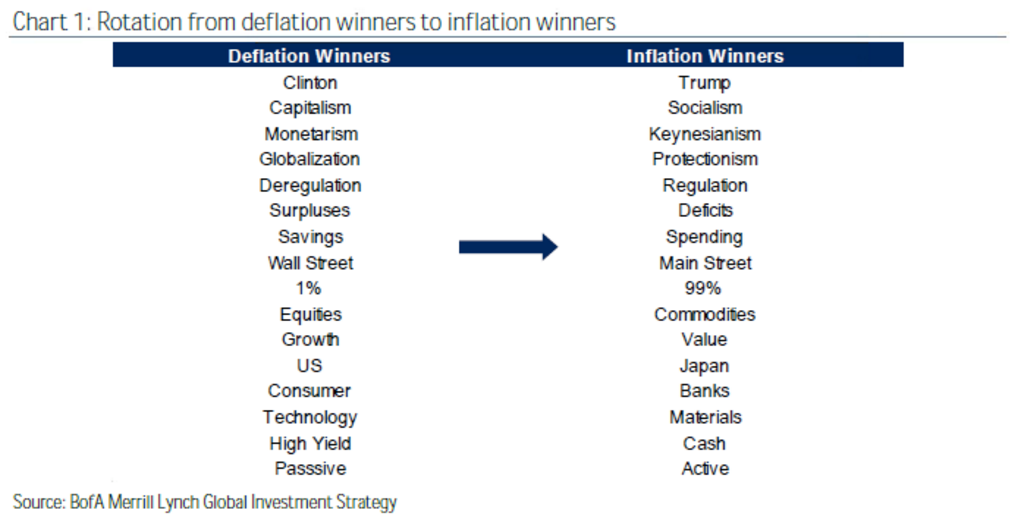
Bank of America is out with a report saying that the new populism and push-back against globalization represents a possible sea-change in asset pricing. The big picture is that we are moving from a “deflation” asset pricing environment to an inflation asset pricing environment. Corporate profitability will suffer as wages increase, regulation increases, and people push back against using globalization as a means of cost-cutting. Government attempts to goose the economy will transition from monetary stimulus to fiscal stimulus. Overall, bad for bonds, but probably good for real estate.

Assuming Hillary wins, she may face the same nemesis her husband did early in his first term: bond market vigilantes. Every time Bill Clinton talked about stimulating the economy, bonds would sell off, which would offset any potential stimulative effect. Bob Woodward said that Bill Clinton’s reaction to this dynamic as :”You mean to tell me that the success of my program and my reelection hinges on the Federal Reserve and a bunch of f*****g bond traders?” Clinton political adviser James Carville said at the time that “I used to think that if there was reincarnation, I wanted to come back as the president or the pope or as a .400 baseball hitter. But now I would like to come back as the bond market. You can intimidate everybody.”
Regardless of what this does to the refi market, it should positively affect the purchase market. Currently, the homeownership percentage for the Millennials is about 34%. That number should increase to above 40% as the Millennial age cohort hits homebuying age. The homeownership rate for the 35-45 age cohort has historically been 60%+. So there is a lot of pent-up demand for homes, which should keep the purchase business humming for many years to come.

Morning Report: Bond yields rising on central bank comments 10/5/16

Vital Statistics:

Last Change
S&P Futures 2148.0 3.0
Eurostoxx Index 343.7 -2.0
Oil (WTI) 49.6 0.9
US dollar index 87.0 0.0
10 Year Govt Bond Yield 1.68%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.48

Stocks are higher this morning on no real news. Bonds and MBS are flat

Bonds sold off yesterday as Chicago Fed President Charles Evans said he expected a rate hike at the December FOMC meeting. Global bonds are also selling off after the ECB discussed tapering its bond purchase program in a move similar to what the Fed did. The German Bund is at -4 basis points after closing last week at -15.

We will have some Fed-speak today, with Neel Kashkari speaking at 9:30 and Jeffrey Lacker speaking at 1:00 pm.

Regardless of who wins in November, there will probably be some changes at the Fed. Donald Trump will probably pursue more wall street types (like Neel Kashkari) while Hillary will focus on diversity. There has been speculation that Janet Yellen would resign if Trump wins, but that looks like a long shot and would weaken the non-political perception of the Fed.

Bill Gross takes aim at central banks worldwide in his latest investment outlook.While central bankers are on a mission to reflate economies via low and negative interest rates, they are undermining the process via which capital gets allocated. Pension funds and insurance companies have to buy overvalued paper simply because there are no alternatives. Ultimately the financial markets exist to allocate capital to new businesses and projects based on risk and reward. Interest rates act as critical inputs into the risk and reward calculation. Central bank activity is distorting the signal that interest rates ordinarily provide, and the longer they do it, the more likely we will increase the misallocation of resources (generally known as bubbles) which will hinder the economy going forward. Exhibit (a) is Japan.

Despite the sell-off in the bond market, mortgage rates seem to be holding steady. This is par for the course, as mortgage rate movements typically lag bond market movements.

Speaking of mortgages, mortgage applications rose 2.9% last week as purchases fell 0.1% and refis increased 5%.

The ADP employment report came in weaker than expected, with 154k jobs added in September, which was less than the 170k forecast. The Street is looking for 168k jobs in Friday’s report. The big number will be wage growth.

Morning Report: Home prices within 6% of peak levels 10/4/16

Vital Statistics:

Last Change
S&P Futures 2155.0 1.0
Eurostoxx Index 346.0 3.0
Oil (WTI) 48.9 0.1
US dollar index 86.4 -0.2
10 Year Govt Bond Yield 1.64%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.49

Stocks are up this morning on no real news. Bonds and MBS are down.

Slow news day, with no economic data.

Economic confidence improved slightly in September, according to Gallup.

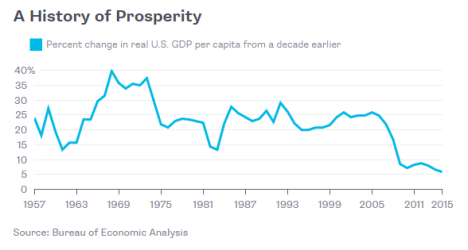
Former Minneapolis Fed Head Narayana Kochlerakota discusses why people feel like the economy is struggling. Per-capita GDP growth is coming in around the high single-digits over a period of 10 years. Historically, that number has been much higher. The US economy has had “lost decades” like this before (basically the 1950s and the 1970s), and growth eventually rebounded. Unsurprisingly, he calls for higher inflation, and further monetary and fiscal stimulus.

per-capita-gdp-growth

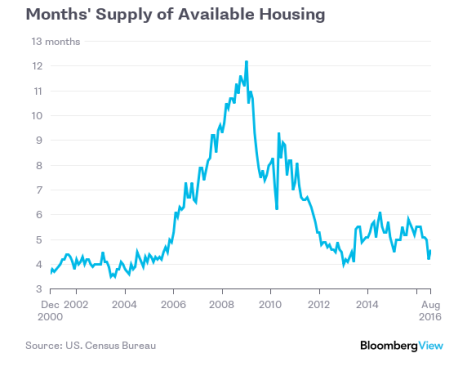
Interesting comparison between the peak of the housing bubble and labor today. In both situations, investors and employers aren’t seeing the ground shift underneath them. The piece also included a chart of housing supply over the past 16 years. Believe it or not, we still have more inventory than we did in the early bubble days, although I wonder how much of this supply consists of abandoned homes that are uninhabitable.

housing-supply

Home prices increased 6.2% YOY according to CoreLogic. This puts home prices at about 6% below the 2006 peak. Increasing prices combined with stagnant incomes is creating an affordability crisis.

Morning Report: Construction spending falls 10/3/16

Vital Statistics:

Last Change
S&P Futures 2155.5 -5.0
Eurostoxx Index 343.2 0.2
Oil (WTI) 48.6 0.4
US dollar index 86.6 0.4
10 Year Govt Bond Yield 1.60%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.46


Markets are down this morning on no real news. Bonds and MBS are down as well.
The big event this week will be the jobs report on Friday. We will also have a lot of Fed-speak as well.
The PMI Manufacturing Index slipped in September, while the ISM manufacturing index rose.
Construction spending fell 0.7% in August.  It is also down 0.3% on a year-over-year basis. Residential construction spending fell 0.2% and is up 1.3% for the year. Public construction was down 2.2% and is down 8.8% on a year-over-year basis. Note both Hillary Clinton and Donald Trump support a big infrastructure spending program.
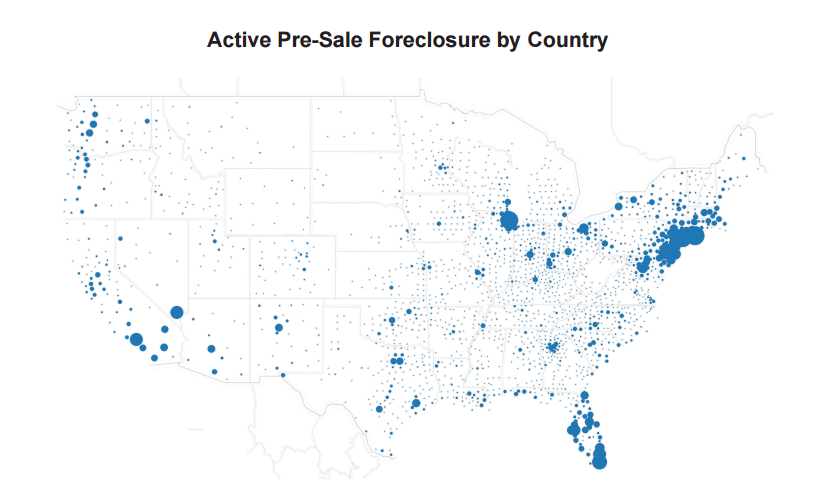
Delinquencies are down in August according to the Black Knight Mortgage Monitor. The pre-sale foreclosure inventory is now down around 1%, although the inventory is still concentrated in the Northeast, Florida, and Chicago areas. Cash-out refinances increased to 42% of all refis.

After Friday’s weak consumer spending data, the Atlanta Fed took down their estimate of Q3 GDP to 2.4% from 2.8%.
Portfolio Managers are forecasting the bond bull market will continue into the 4th quarter as global growth is simply too weak to push up inflation. Of course they are talking their books, but they are probably correct. Separately, Henderson of the UK bought Janus Capital this morning.
Over the weekend, the New York Times got ahold of Donald Trump’s taxes from 1995, where he showed a $916 million loss, which he has used to write off taxes owed going forward. Of course, using business losses to offset business income is as legal as eating a hot dog at the ballpark, so there probably isn’t a lot of political “there” there. Separately, Julian Assange claims he has emails which will finish Hillary Clinton, though WikiLeaks is delaying the release.
China continues to grapple with its housing bubble in hopes of engineering a soft landing. Watch the video at the end of the story, where investors storm an entrance in order to buy property.

Morning Report: Incomes up, spending flat 9/30/16

Vital Statistics:

Last Change
S&P Futures 2150.0 1.0
Eurostoxx Index 340.9 -2.0
Oil (WTI) 47.9 0.0
US dollar index 86.6 0.4
10 Year Govt Bond Yield 1.55%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.47

Stocks are lower this morning as the markets fret about Deutsche Bank. Bonds and MBS are up on the risk-off trade.

Deutsche Bank, which is being fined by the US government for $14 billion is starting to see some hedge fund clients back away from it. While it probably doesn’t really pose any systemic risk (the US government isn’t about to bankrupt German’s biggest bank) it will cause a flight to safety, which will push down Treasury yields. If this snowballs, look for more easing out of the ECB, and potentially another excuse for the Fed to stand pat.

Personal Incomes rose 0.2% last month while personal spending was flat. The core personal consumption expenditure index (the Fed’s preferred inflation measure) rose 1.7% YOY, which is below the Fed’s 2% inflation target. Larry Summers says income inequality is depressing spending by about 3%.

The Chicago Purchasing Manager Index rose in September.

Consumer confidence improved in September.

Janet Yellen mused about the Fed buying corporate bonds and stocks in order to respond to a downturn after they have hoovered up all the government debt out there.

Seriously delinquent loans fell to 1.24% in August, the lowest level since April 2008. Pre-crisis it was below 1%.

Morning Report: Pending home sales fall on tight inventory 9/29/16

Vital Statistics:

Last Change
S&P Futures 2159.0 -4.0
Eurostoxx Index 344.3 2.0
Oil (WTI) 47.1 0.0
US dollar index 86.5 0.4
10 Year Govt Bond Yield 1.59%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.47

Stocks are lower this morning as oil rallies. Bonds and MBS are down small.

Initial Jobless Claims came in at 254k, which is at a 43 year low. When you take into account population growth, that number is astounding. The last time jobless claims were around these levels, we had just ended the draft for the Vietnam War.

The third revision for Q2 GDP came in at 1.4%, which was an increase from the second estimate of 1.1%. Non-residential fixed investment and consumption drove the upward revision. The Personal Consumption Expenditure Index (the Fed’s preferred measure of inflation) came in at 2%, spot on with their target. Gross Domestic Income fell 0.2%, which is a disappointment.

Consumer Comfort ticked up last week, according to the Bloomberg Consumer Comfort Index.

Pending Home Sales dropped 2.4% in August, according to the NAR. Lawrence Yun, NAR chief economist, says suffering supply levels have taken the wind out of the momentum the housing market experienced earlier this year. “Contract activity slackened throughout the country in August except for in the Northeast, where higher inventory totals are giving home shoppers greater options and better success signing a contract,” he said. “In most other areas, an increased number of prospective buyers appear to be either wavering at the steeper home prices pushed up by inventory shortages or disheartened by the competition for the miniscule number of affordable listings.”

Immigrants are much more educated today than they were a couple of decades ago. That is creating issues in the housing market. Traditionally, low-skilled immigrants were builders of housing. Today many are arriving with college degrees, and therefore they are much more likely to be buyers of housing. This partially explains why inventory is tight and why it is hard to find skilled labor.

Corporate profits fell 1.7% YOY in the second quarter. This is the third consecutive drop, which is a worrisome stat for the stock market, especially as the Fed begins to take away the punch bowl.

Separately, are rising incomes helping to alleviate the problem of affordability? The drop in GDI didn’t help. The ultimate issue will revolve around the long-term unemployed. Do they come back into the workforce or stay out? If they come back, wage inflation will be modest until that reservoir is used up. Ultimately that is better for the economy long-term. If they stay out, it will depress consumption and will probably start pushing up wages for those that do have jobs. Watch the quits rate on the JOLTS job openings. That will be the tell.

Morning Report: The hottest real estate markets are cooling off 9/28/16

Vital Statistics:

Last Change
S&P Futures 2153.5 1.0
Eurostoxx Index 343.1 3.0
Oil (WTI) 45.2 0.5
US dollar index 86.3 -0.2
10 Year Govt Bond Yield 1.56%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.47

Stocks are flat this morning on no real news. Bonds and MBS are flat as well.

We have a lot of Fed-Speak today, with Neel Kashkari, Janet Yellen, and James Bullard speaking this morning. Charles Evans, Loretta Mester, and Esther George speak this afternoon. There is the possibility that some of them could say something market-moving so be careful with your locks.

Mortgage Applications fell 0.7% last week as purchases rose 1% and refis fell 2%.

Durable Goods orders were flat month-over-month and down 1.3% YOY. Ex-transportation, they fell on a MOM and YOY basis. Capital Goods orders (a proxy for business capital investment) is also down for the year, although it was up on a MOM basis. July’s numbers were revised downward, so this report is nothing to write home about.

Despite the gloom in the corporate sector, consumer confidence rose and is at post-crisis highs. This is probably being driven by the stronger labor market. We aren’t seeing these numbers flow through to actual sales at the retailers though. The Back-To-School shopping season was a disappointment.

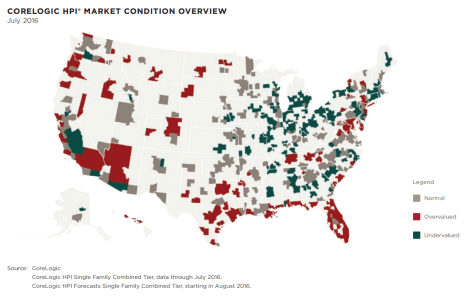
The hottest real estate markets are beginning to cool off, as high prices and low inventory are putting off buyers. Many of these markets have long surpassed their bubble peaks and are hitting new highs. Given that incomes have not recovered, these price levels may be unsupportable, especially as the Fed hikes interest rates and mortgages become more expensive.

The latest CoreLogic Market Pulse looks at some of the overvalued markets based on price to income ratios and price to rent ratios. Unsurprisingly, there are pockets of overvaluation in CA, NY, FL, and TX, while the Midwest remains undervalued. The chart is below:

corelogic-overvalued

The article also goes on to say that we aren’t in a housing bubble. This is true, as bubbles are largely psychological phenomenons where investors and lenders consider an asset “special” and believe it can only go up in price. The last residential real estate bubble (aside from the mid 00s) was in the 1920s. Residential real estate bubbles are rare and I doubt any of us will see another on in the US in our lives. That said, we have residential real estate bubbles in lots of countries overseas (especially China, Norway, and Canada), which will be a damper on global growth when they burst.

During the debates, Donald Trump went after the Fed, calling them “political” for not raising interest rates. Politicians have always jawboned the Fed, but this has to be the first time I have heard a politician complain that the Fed is keeping rates too low. Usually, politicians are calling for the Fed to not raise rates because they are worried about a recession. At least one economist thinks Janet Yellen would resign if Trump wins.