Morning Report – FOMC data dump 9/18/14

Markets are higher after yesterday’s FOMC statement was still reasonably dovish. Bonds and MBS are down small.

Initial Jobless Claims dropped to 280,000, an extraordinarily low number that is associated with boom times like 1999 and 2005.

Housing starts were disappointing, coming in at 956k, a sizeable drop from the upward-revised 1.11 million in July. The drop was almost all in the multi-fam segment, which tends to be extremely volatile. Building Permits fell as well.

The FOMC statement kept language stating that the Fed Funds target rate should remain at current levels for “a considerable time” after QE ends. The Fed noted there remains “significant under-utilization” of labor resources. That said, the FOMC raised their Fed Funds forecast for 2015 by 1/4 and 2016 by 3/8, according to the dot graph in the projection materials. The Fed took down their unemployment and GDP forecasts for this year and next year as well. On the subject of QE, it should end this year and for the time being, the Fed will continue to re-invest maturing proceeds. They do not intend to sell their MBS portfolio. At the margin, this means lower mortgage rates going forward. Bonds sold off on the statement (probably due to the dot graph), and stocks rallied as the Fed’s posture will remain dovish for the near and intermediate future.

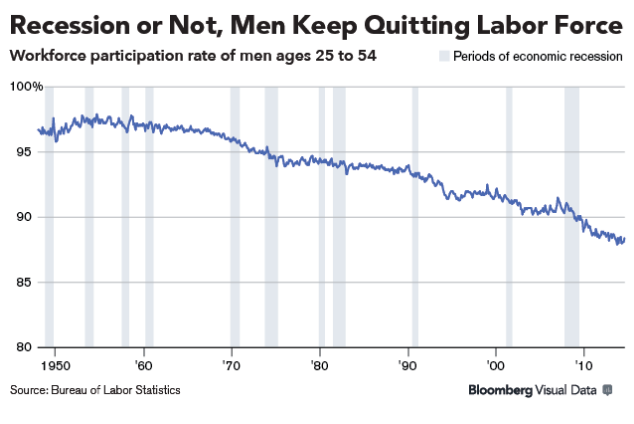
Note that the “significant under-utilization” language is at odds with what the Staff economists believe is going on in the labor market. The Staff Economists discussed the idea that those who are long-term unemployed may turn out to be effectively retired, and if that is the case, then there is less slack in the labor market than previously thought. The Great Recession has put a lot of men in their prime earning years on the sidelines.
I appeared on Louis Amaya’s Capital Markets Today show and discussed the FOMC statement and the economy. You can hear the interview here.

Morning Report – Waiting on the Fed 9/17/14

Markets are flat this morning as we await the Fed’s decision at 2:00 pm. Bonds and MBS are up.

The FOMC decision should be out by 2:00 pm EST. I suspect any surprises will be in the press conference, not the actual release.

The NAHB Homebuilder Sentiment Index rose to a post-bubble high.

Mortgage Applications rebounded 7.9% last week after printing the lowest level since 2001 in the prior holiday-shortened week. Purchases rose 4.8%, while refis increased 10.3%. Interestingly, MBA is reporting the average 30 year fixed rate mortgage rate increased to 4.36% after having been stuck in a 4.25% – 4.30% range all summer. Mortgage rates didn’t really follow bond yields lower ahead of the ECB announcement, but now they are heading higher along with bonds. This could be evidence of (a) capacity having been wrung out of the system, or (b) bankers making loans that they wouldn’t have made a year ago, which carry higher rates.

Inflation at the consumer level remains muted. The consumer price index fell .2% in August as gas prices decreased. Ex-food and energy, it was flat. Certainly not seeing much evidence of inflation.

Lennar reported good numbers, with a 23% jump in new orders, a 29% increase in backlog, Average Selling Prices rose 14% to $332,000. Lennar was one of the few companies that reported increases in deliveries – most had been showing drops in deliveries offset by an increase in ASPs. The stock is up a couple of bucks pre-open.

Good news for builders like Lennar, Pulte, and D.R. Horton who have exposure to the entry-level buyer – the Millennial generation is moving out of Mom and Dad’s basement. This has all sorts of implications for the housing market – they will be the demand for rentals and also for starter homes. We have underbuilt since the bust and demand is starting to come back. Of course we have a long way to go to get to normalcy, but at least we are headed in the right direction. Note the Wells survey from yesterday – many might actually be interested in buying, but they believe (wrongly) that a 20% downpayment and perfect credit is mandatory to get a loan. Education about FHA loans is key.

HUD secretary Julian Castro spoke at the Bipartisan Policy Center 2014 Housing Summit. Here are his prepared remarks. Obviously access to credit is a big concern on the part of HUD, and they are trying to address it by clarifying rules and regulation and putting them in a single resource – the Single Family Handbook, which will address loan defects and how serious they are. Second, they are rolling out a program designed to counsel first time homebuyers, rewarding them with a MI break if they go through the program. I do wonder how much improved access we are going to get with the barrage of lawsuits continuing.

Morning Report – Buybacks are levitating the market 9/16/14

Markets are lower on no real news. Bonds and MBS are up small. Today starts the FOMC meeting.

Inflation at the wholesale level remains under control, with the Producer Price Index coming in flat for the month of August. Ex food and energy, it was up .1% (or 1.8% annualized). Inflation is still below the Fed’s target.

Wells Fargo conducted a survey about homebuying attitudes, and there are some major misconceptions out there. 30% believe only individuals with high incomes can obtain a mortgage. 64% believe they must have a “very good” credit score to buy a home. 44% believe a 20% down payment is a requirement. People really do not know about FHA lending.

CALPERS (the California Public Employees Retirement System) – the biggest US pension fund, is redeeming its hedge fund investments. High costs and low transparency are the stated reason, but another reason is underperformance. Average public pension gains from hedge funds were 3.6% over the past 3 years, vs 10.6% in stocks and 5.7% from bonds.

What is holding up the stock market these days? Buybacks. Interesting stat: companies in Q2 spent 31% of their cash flow on buybacks. This is having an outsized effect as volumes dry up. In Q2, stock market volume averaged just over 6 billion shares a day, the lowest level in 7 years.

Morning Report – Big Week Ahead 9/15/14

Markets are flat this morning ahead of a big week for data and events. Bonds and MBS are down.

Industrial Production fell .1% in August, while capacity utilization dropped by 30 basis points to 78.8%. It looks like the notoriously volatile motor vehicle sector accounted for the decline. The previous month had a big increase in motor vehicles, which it looks like we gave back in August.

The Empire Manufacturing Survey came in at 27.5, a multi-year high.

This week we will have the FOMC meeting, with the decision on Wed afternoon. This meeting will include new projections and also should include a press conference. The Street will be focusing on any changes in the rate projections from the voting members (note that the mix of voting members will turn much more dovish at the beginning of 2015).

One of the interesting features of mortgage rates this summer has been the decoupling from long-term bonds. As rates fell during the summer, mortgage rates stayed stuck at the 4.25% range. Now that bonds are selling off, mortgage rates are still relatively constant. Look at the graph below. The top line is the 30 year fixed rate mortgage according to Bankrate, and the lower line is the 10 year bond yield. The correlation has completely broken down.

Morning Report – The Fed thinks the labor force participation rate isn’t going to increase meaningfully9/12/14

Markets are flat as we close out a dull week. Bonds and MBS are down amidst a global bond sell-off.

Retail Sales increased .6% in August. Ex autos and gas, they increased .4%. July’s numbers were revised upwards.

Import prices fell .9% in August, driven by a drop in oil prices. Ex food and fuels, import prices were flat.

The preliminary September reading for the University of Michigan Consumer Sentiment indicator showed an increase and hit the high for the past year.

The jumbo securitization market is pretty much dormant, except for the occasional Redwood Trust deal. Only 2.3% of all jumbos originated in the first half of 2014 have been securitized. At the peak of the housing bubble, almost half of all jumbos were securitized. Banks are instead choosing to hold them on their balance sheet. Banks are subsidizing the jumbo mortgage rate in order to bring in the wealthy client and then offer all other sorts of banking services, including the lucrative wealth management business.

Another article about the lowering of the speed limit for the economy. Federal Reserve economists do not expect the labor force participation rate to increased meaningfully as the labor market improves. They argue that the number of people who aren’t working, but would work if conditions were better are relatively small. The upshot is that this paper bolsters the hawk case at the Fed and is ammo for those who want to start raising rates. Not sure dove Yellen will play along, and the voting members will take a dovish turn next year as hawks like Plosser lose their vote.

Morning Report – Another sign of a credit market top 9/11/14

Markets are higher this morning on on real news. Bonds and MBS are rallying.

Initial Jobless Claims came in at 315k, a little higher than street expectations, but still a good number.

The President talked about ISIS last night. It was a declaration of war. Or something. Here are the takeaways.

The Fannie Mae National Housing Survey is out – average home price expectations continue to fall as consumers temper their bullishness on home price appreciation. People still have a dour view on the economy but it is improving slightly. That said, it looks like incomes took a bit of a hit in August.

Bill Gross of PIMCO has been raising cash in his Total Return Fund, selling Treasuries and developed sovereigns. Mortgages as a percent stayed flat at 20%.

Twitter is doing a new convertible bond which are convertible into stock or cash at Twitter’s election. This is rare – usually the choice is the bondholder’s not the issuer’s, at least on senior unsecured paper. This isn’t a convertible pref issue. It will be interesting to see the pricing on this – essentially the holder will be short a put on Twitter stock. If Twitter’s stock craters, Twitter gets to essentially sell stock at current levels. If Twitter stock continues to rally, they can either pay cash, or sell Twitter stock in the market at higher prices, redeem the bonds and pocket the difference between the sales price and the conversion price. The bigger point is that bond issues are getting more and more lopsided in favor of the borrower, and that is a classic market top signal. Investors are reaching for yield and taking risks they are not getting adequately compensated for. Paper like this can go no-bid in a hurry. IMO, the stock market is assuming that the Fed can start raising rates without anyone blowing up. Historically that hasn’t happened.

Foreclosure activity picked up in August, according to RealtyTrac. Activity picked up in the big judicial states like New York, New Jersey, and Connecticut.

Morning Report – Mortgage Applications lowest in 14 years 9/10/14

Stocks are lower this morning on no real news. Bonds and MBS are down as European bonds sell off.

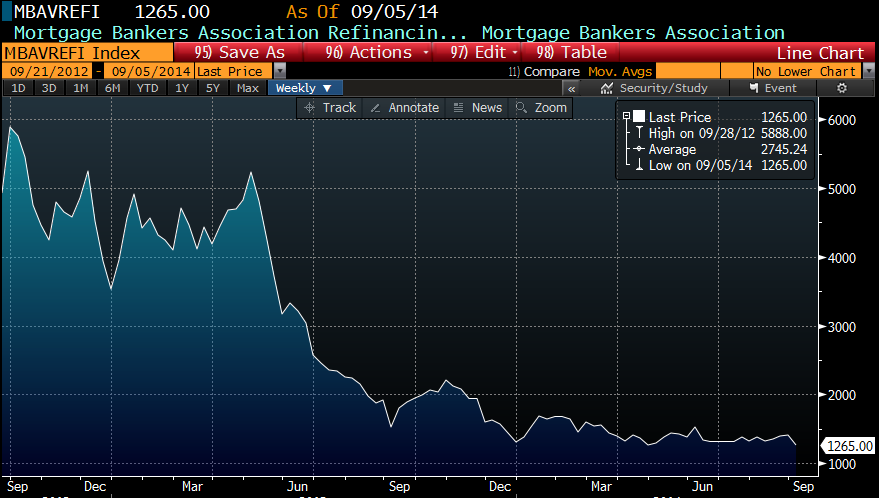
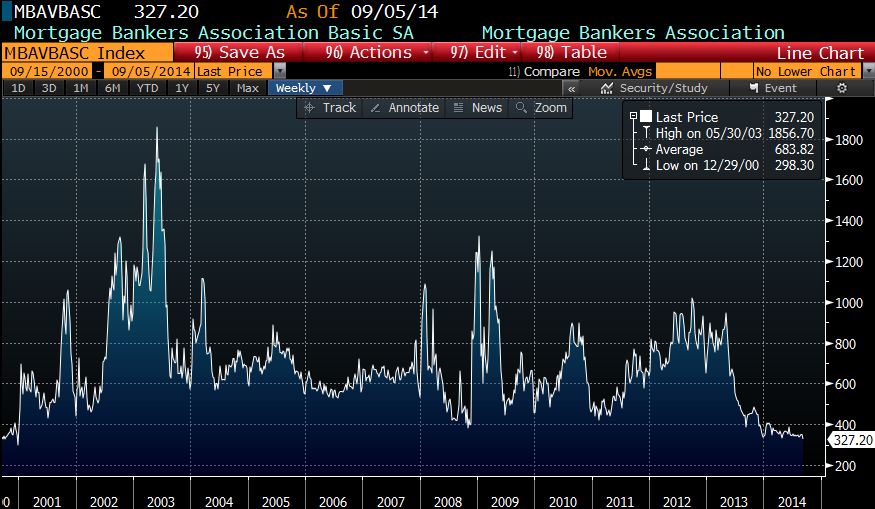
Mortgage Applications fell 7.2% last week as we had the Labor Day holiday and rates backed up. Purchases fell 2.6% while refis fell 10.7%. Refis accounted for 55.4% of all loans. The refi index just hit its lows for the year, even though rates have fallen almost 50 basis points. This effect is called prepayment burnout, and it is due to the fact that anyone that has been able to refinance already has. The driver of refis going forward will be home price appreciation, not rates.

Note that the overall mortgage application index is hitting lows not seen since 2000.

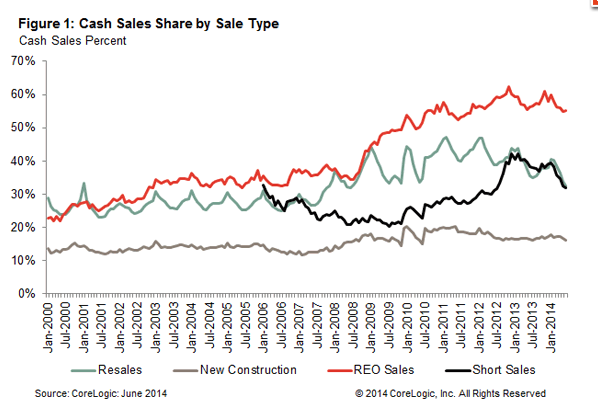
On the plus side, all-cash transactions are down to a six year low.  Cash sales fell to 33% of total home sales in June, down from 36.3% a year ago.

Rep Maxine Waters (D-CA) is introducing legislation to change what goes on credit reports. One fix being considered is eliminating medial debt, which accounts for more than half of all unpaid debt in collection, from credit scores. Other changes would remove settled debts, remove black marks after 4 years instead of 7, and remove student debt defaults if the loan performs for a set period thereafter. The idea is to open access to credit.

Think fast food workers are irreplaceable? Think again. McDonalds is expanding a test concept allowing people to order via a tablet. This makes a good juxtaposition to the “living wage” strikes and legislation being considered.

Unintended consequence of ZIRP, number 1,234,567 – LBO funds are ratcheting up the leverage to boost returns. Not only that, but credit quality and covenants have been declining in these deals. The S&P 500, sitting at record levels, is assigning a 100% probability that the Fed can stick the landing and start raising interest rates without anyone blowing up. As we saw when the Fed started raising rates in 1994, 1999, and 2004, bad things tend to happen (Orange County in 94, the end of the stock market bubble, the end of the real estate bubble). If I was fully invested in the market, I would begin to finish my drink, find my coat, and watch the door.

Morning Report – Job openings the highest since 2001 9/9/14

Stocks are flat on no real news. Bonds continue their post-ECB retreat.

Consumer credit increased 9.7% year over year in July, according to the Fed. Note this does not include mortgages. Revolving debt increased 7.4%, while non-revolving debt increased 10.6%.

Job openings remained steady at 4.7 million in July, which is the highest level since 2001. So why does the labor market stink? People don’t have the skills employers demand.

Small business optimism increased by .4 in August to reach 96.1, the second highest reading since October 2007. Expectations are still glum, however as the majority of small business owners think conditions will be worse in six months. NFIB owners increased employment by an average of 0.02 workers (basically flat), however it was the eleventh positive month in a row. Earnings trends improved 1 point to -17. This statistic shows the stark contrast between the big S&P 500 names (which have a lot of international exposure) versus Main Street Small Business. Reading the report, you wouldn’t guess the S&P 500 is at record highs.

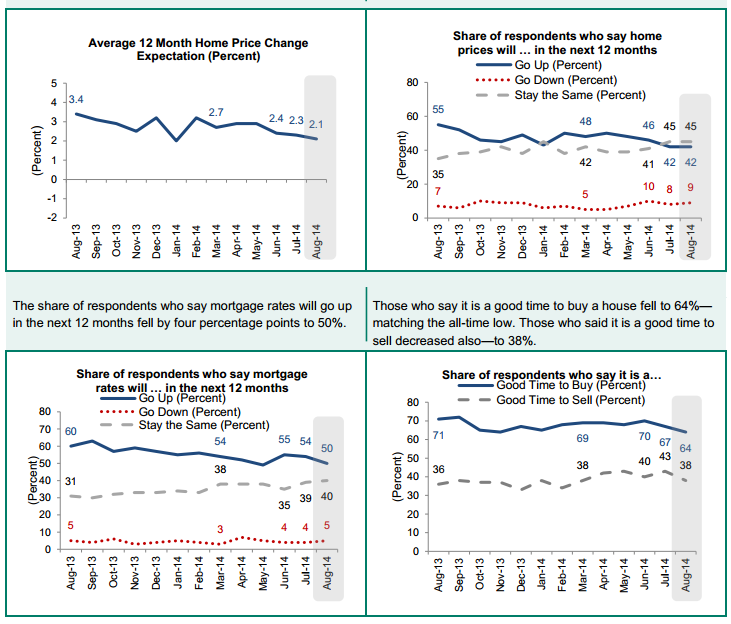
Consumers continue to temper their expectations for home price appreciation, according to the Fannie Mae National Housing Survey. Consumers expect an average 12 month appreciation of 2.1% going forward. 42% of respondents thing house prices will increase, 45% expect them to stay the same, and 9% expect them to fall. 23% said their household income was significantly higher than it was a year ago (a drop from 28% last month), while 15% said their income was significantly lower than it was a year ago (an increase from 12% last month). So regardless of what the consumer sentiment surveys say, things are not necessarily getting better for the average homeowner.

Mohammed El-Arian explains what is going on with US yields vis a vis European yields. Yields could rise in US Treasuries as f/x rates adjust to persistent European economic weakness.

The Fed is contemplating capital requirements that will be even tougher than Basel. At the margin, this would mean less mortgage lending by the big banks like Wells and JP Morgan.

Morning Report – Slow data week ahead 9/8/14

Slow news day. The week following the jobs report always has a dearth of data, so there isn’t much on the economic front to talk about.

We will get consumer credit out of the Fed sometime this afternoon.

Why is credit so tight for first time homebuyers and people with low FICOs? Ask Washington. It seems like the authorities are now forcing buybacks and fines over relatively minor errors, and as a result, lenders are refusing to extend credit to low-income / low FICO borrowers. Of course the Administration continues to exhort the industry to loosen standards at the same time it announces record settlements.

A majority of primary dealers see the first rate hike in the second quarter of 2015. The median forecast for the Fed Funds rate at the end of 2015 is 1% and 2.5% for the end of 2016.

Hawk Charles Plosser says that keeping rates near zero until the Fed’s goals are achieved is a risky strategy.

Morning Report – Lousy jobs report 9/5/14

Markets are lower after a lousy jobs report. Bonds and MBS are up.

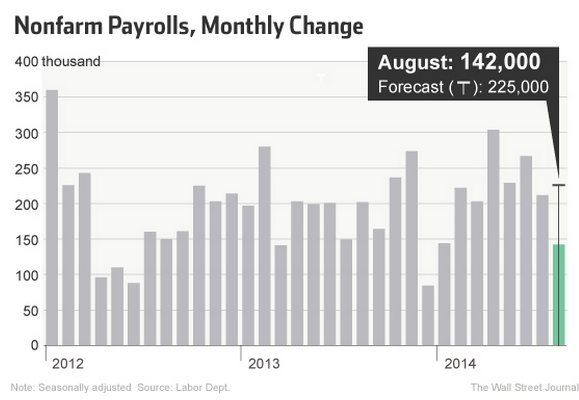
The jobs report came in surprisingly weak. Payrolls increased 142k in August, while the Street was expecting to see 230k. The two-month revision was -28k. Unemployment ticked down to 6.1%, however the labor force participation rate dropped back to its lows at 62.8%. Average Hourly Earnings rose .2% and the workweek was flat at 34.5 hours. Overall, a very disappointing report that doesn’t really comport with some of the other data we have been seeing (like the ISM which has been super strong). I wouldn’t be surprised to see this report revised upward (for the record, August reports are notorious for big revisions), but for the moment, there it is.

 nonfarm payrolls wsj

Demographically, it looks like the biggest growth was in the 25-35 year old cohort, which is what we need to see in order to bring back the first time homebuyer. Interestingly we saw a bit of growth in the 55+ age bracket.

Minneapolis Fed President Kocherlakota believes the Fed should be doing more, not less to stimulate the economy. He says that “interest rates are not low enough….Given where we are with inflation, I think that it’s challenging to know why we are removing stimulus from the economy at the rate that we are.” Note that the makeup of the Fed changes every year, and two hawkish voting members – Plosser and Fisher are being replaced by doves Evans and Lockhart. This  will mean one lone hawk, four neutral, and five doves.

Mortgage credit tightened slightly in August, according to the MBA. Credit did ease for 203k loans and construction loans, but overall credit dipped, particularly on the government side.