Posted on September 4, 2014 by Brent Nyitray
Markets are higher this morning after the ECB cut rates to 5 basis points and committed to start buying securitized debt and covered bonds in October. Bonds are flat as this decision had been priced in already.
Just something to think about – the “buy the rumor, sell the fact” effect. In other words, the big move for ECB QE was over the past six months, and it wouldn’t be surprising to see a sell-off in sovereigns as the announcement is out of the way and speculative players unwind their positions. Euro sovereigns are driving the US bond market at the moment.
Denmark just cut its deposit rate to negative 5 basis points. They are in the throes of a burst real estate bubble.
The ISM Non-Manufacturing index rose to 59.6, the highest since August 2005. The manufacturing index rose to 59, and would correspond to a GDP growth rate of 5.2%. Of course manufacturing doesn’t have the impact on the US economy it used to, but still….
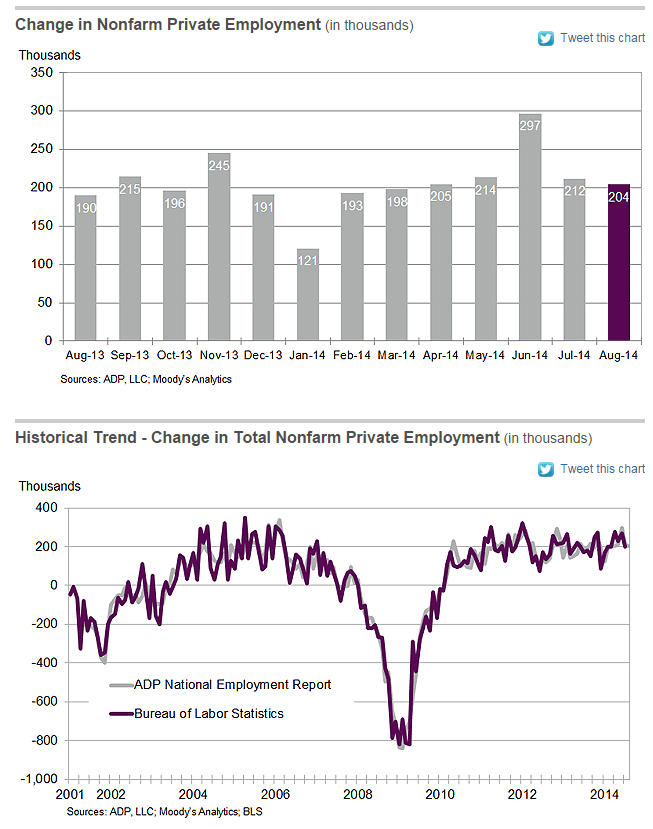
ADP is forecasting the economy will add 204,000 jobs in August. ADP has been spot-on the last couple months. The Street is forecasting 215k tomorrow.
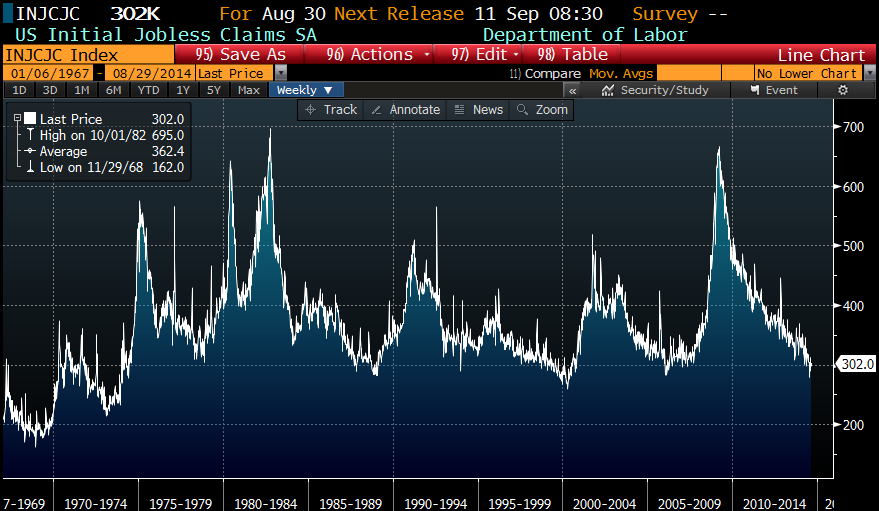
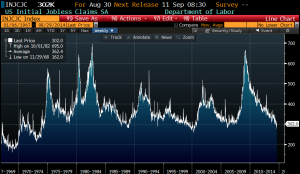
In other labor market data, announced job cuts fell 21% according to outplacement firm Challenger, Gray and Christmas. Unit Labor Costs fell .1% in the second quarter as productivity rose 2.3%. Finally, initial jobless claims ticked up slightly to 302,000. Initial Jobless Claims levels are back to boom-time levels, and as a percent of the population are back to levels not seen since the late 1960s.
What is holding back wage inflation? Pent-up deflation. As Keynes pointed out, during recessions wages should fall as the demand for labor falls. However, employers are loath to cut pay (a phenomenon called sticky wages) which means that by not cutting wages, employers are overpaying during a recession. As the recovery builds steam, therefore they are not feeling pressure to raise them either. Interesting theory, and one thing the researchers say is that once this runs its course, wages could rise more quickly than economic models suggest as businesses that kept wages low for too long are forced to play catch up. This may in fact be what was behind the language in the FOMC minutes about there being less slack in the labor market than people think. We will see tomorrow with the jobs report. Separately, the average weekly hours worked by a full time employee inched up to 46.7 hours.
Filed under: Morning Report | 21 Comments »
Posted on September 3, 2014 by Brent Nyitray
Markets are stronger this morning as tensions ease in Ukraine. Bonds and MBS are down small.
The ISM New York Index fell to 57 from 68, while factory orders rose 10.5%.
Luxury builder Toll Brothers reported earnings this morning. The luxury end of the market is doing just fine, with deliveries up 53% in dollars and 36% in units. ASPs increased 12% to 732k. Net signed contracts fell however, and the average price for signed contracts increased only 1.4% year-over-year, Perhaps we have seen the point where buyers are finally balking at higher prices.
Mortgage Applications rose .2% last week. Purchases fell 1.5% while refis rose 1.4%. Refis are back up to 57% of total number of loans.
Part of the reason why purchases are slipping is due to seasonality, however mortgage rates have not been falling with Treasury rates. The average 30 year fixed rate mortgage has been stuck in the same 4.1% to 4.2% range for the past 3 months, while the 10 year has rallied from 2.6% to 2.34%. The last time rates were this low, the average 30 year fixed rate mortgage was 3.93%. I think there are two things going on here – first I think banks view this move in rates as being driven by overseas events and therefore temporary. Second, I think that lenders are taking more risk than they were a year ago, which means higher rates on average.
Have you noticed that chocolate bars are getting smaller? That your “pint” is no longer a pint at your local watering hole? Welcome to shrinkflation, a state of affairs where companies maintain the same price, but give you a little less. We saw this movie before in the 1970s and 1980s, which was captured quite eloquently in Wendy’s “Where’s the Beef” ad campaign. This actually started in the 1970s, and shows that inflation can take two forms – price increases and quantity (or quality) decreases.
Filed under: Morning Report | 47 Comments »
Posted on September 2, 2014 by Brent Nyitray
Markets are higher this morning on no real news. Bonds and MBS are down.
Short week, but a lot of important economic data. Today, we get the ISM Manufacturing Survey and Construction Spending. On Thursday, we get the ISM Non-Manufacturing Index, and on Friday, we get the jobs report. Between the data and European events we could have a volatile week for rates.
The ISM Manufacturing Index rose than expected, while the ISM prices paid index dropped. Production and New Orders jumped. Employment ticked down slightly. The production and new orders numbers bode well for 3Q GDP.
Construction spending rose 1.8% month-over-month as residential construction increased .7% and non-residential rose 2.5%. Of private residential construction, 52% was single family construction, 12% was multi-fam, and 36% was home improvement.
The IBD / TIPP Economic Optimism Index rose slightly, but came in a bit light. Note that this Thursday we will be getting same store sales from the retailers and back-to-school shopping numbers. BTS is a good indicator for holiday shopping. We have seen strong consumer sentiment numbers, but so far that hasn’t translated into actual spending.
Euro sovereigns are weaker this morning, which means US Treasuries are weaker. Speculation over whether the ECB will start quantitative easing is going to be driving bonds as much, or even more, than US economic data. Note that hedge funds are getting long Treasuries. It finally happened. People are momentum trading bonds.
Angelo Mozillo has no regrets over what happened with Countrywide. As he puts it: “Countrywide didn’t change. I didn’t change. The world changed.” Compared to other CEOs of that era, Mozillo has not shied away from the public spotlight. The US Attorney’s Office in Los Angeles is suing him now.
Finally, I appeared on Louis Amaya’s Mortgage Markets Today show last week and discussed interest rates and the housing market. The full interview is here.
Filed under: Morning Report | 9 Comments »
Posted on August 29, 2014 by Brent Nyitray
Markets are flat this morning on no real news. Bonds and MBS are flat as well.
I don’t think bonds are closing early today, but for all intents and purposes they are as most of the Street will be gone by noon ahead of the 3 day weekend.
The ISM Milwaukee index fell to 59.6, however the Chicago Purchasing Managers Index rose to 64 and the University of Michigan Consumer Sentiment Survey rose to 82.5.
Ready to pop the champagne over the good consumer sentiment numbers? Well, it has yet to flow through to actual spending. Personal Spending fell .1% in July, however the reason was falling energy prices. Ex-food and energy, spending increased .1%. That said it isn’t that strong of a number. Personal Income rose .2%.
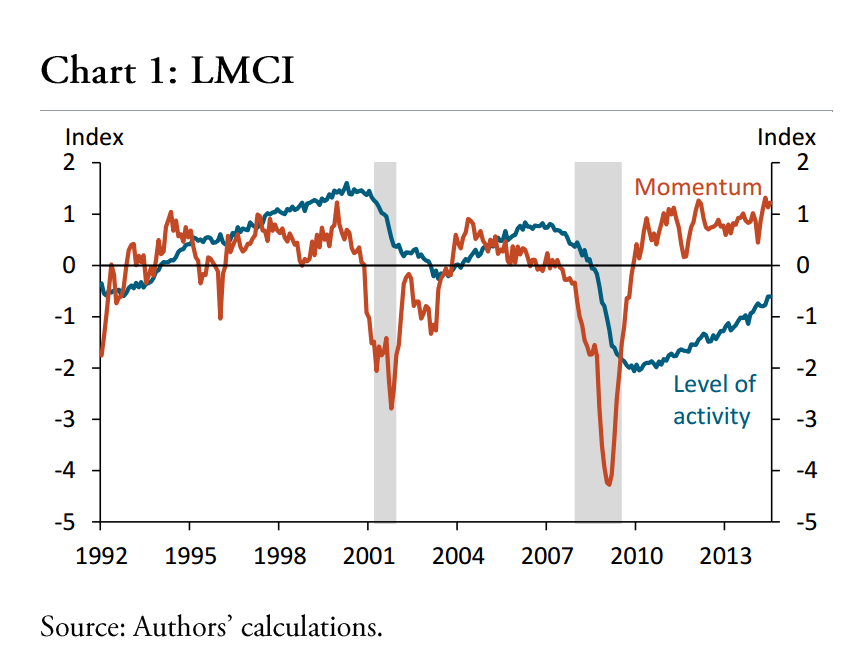
One of the interesting features of this recovery has been the disconnect between the reported unemployment rate and the actual health of the labor market. While unemployment keeps falling, the labor market still doesn’t feel much better. The Fed is now looking at an index comprised of 24 indicators called the Labor Market Conditions Index (LMCI) to describe the health of the labor market. There are two pieces to the index – the current level of activity and momentum. The momentum indicator gives you clues as to where the market is going in the future. Here is what it looks like at the moment – about a year away from normalcy.
Short missive as there is not much going on. Have a happy Labor Day everyone.
Filed under: Morning Report | 23 Comments »
Posted on August 28, 2014 by Brent Nyitray
Some strong economic data this morning, with the second revision to 2Q GDP coming in at 4.2%. Consumption rose to 2.5% and the PCE price index (the Fed’s preferred inflation indicator) came in at 2.1%, with the core at the Fed’s target rate of 2%.
Initial jobless Claims came in at 298,000, another strong number. The Bloomberg Consumer Comfort Index rose to a 5 week high.
Pending Home Sales rose 3.3% in July, but are down 2.7% year-over-year.
The Ellie Mae Origination Insight Report is out. Refis dropped to 32% of all loans in July. FHA accounted for 20%, Conventional 64%, VA 11% and other 5%. The average FICO dropped to 727.
New rules on PMI could raise rates on average 15 basis points.
The elderly are finding the amount they owe on their mortgages increasing. Not sure how much of this is due to reverse mortgages. The mortgage-burning party seems to be a thing of the past.
Consumers have confidence, but not the cash to do anything about it. This is why the consumer confidence numbers look good, but spending numbers are not. Asset prices can only do so much – the chief driver of spending is wages, not asset prices. In fact, home equity extraction during the bubble years masked the overall weakness in wage growth.
Filed under: Uncategorized | 9 Comments »
Posted on August 27, 2014 by Brent Nyitray
Stocks are higher this morning as the S&P 500 crossed the 2000 level yesterday. Bonds are following the rally in Europe. The German 10 year hit 90 basis points this morning.
Slow news day. Going to be a short missive because there isn’t much to talk about.
Mortgage Applications rose 2.8% last week. Purchases rose 2.6% while refis rose 2.8%. Refis were 55.7% of all mortgages originated.
As European economies continue to struggle, the speculation is that European Central Bank Head Mario Draghi will announce some sort of quantitative easing early in September. Blackrock was just appointed as the ECB consultant for the ABS purchase program, it looks like the ECB is serious about going down this route.
The 2008 meltdown was worse than the Great Depression, according to Ben Bernanke. “Of the 13 most important financial institutions in the United States, 12 were at risk of failure within the period of a week or two.”
Filed under: Morning Report | 10 Comments »
Posted on August 26, 2014 by Brent Nyitray
Rallies in European stocks and bonds are dragging US stocks and bonds along for the ride. Remember the PIIGS? The US 10 year yields just a touch less than Italian sovereign debt and about 20 basis points more than Spanish sovereign debt. Let that sink in.
Durable goods orders were all over the map due to a big jump in aircraft orders. The headline number increased 22.6%, however the number most pros focus on – Capital Goods Orders Non-defense / ex-aircraft was down .5%, however June was revised up big, from 1.4% to 5.4%.
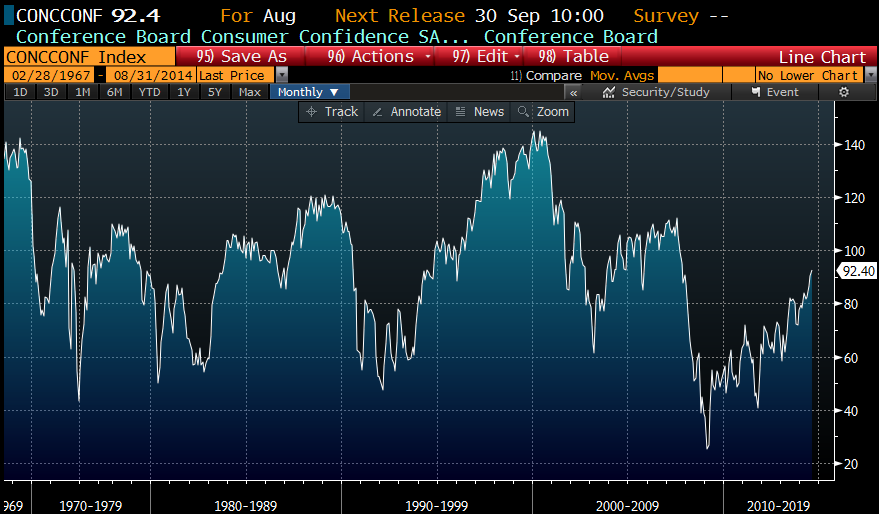
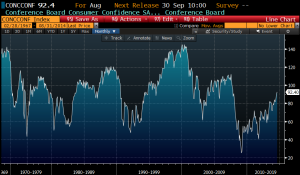
The Richmond Fed Manufacturing Index rose to 12 from 7. Consumer Confidence rose to 92.4 in August, from 90.3 the prior month. This is a post-recession high and we are approaching historical normalcy. Lets see if this translates into good personal spending numbers on Friday.
It is official: Burger King is buying Tim Horton’s and plans to move its headquarters up north. Expect the usual kvetching about “corporate patriotism” out of the usual suspects. That said, Walgreens was jawboned into not moving their headquarters, but the stock was slammed on the decision. I am curious as to whether the left will go after the company by threatening a boycott or will go after Burger King Worldwide’s biggest shareholders – 3G and Pershing Square. That said, 3G is a Brazilian investment firm, and who knows if Ackman holds BKW in its onshore or offshore accounts. BKW could already be more or less foreign owned to begin with.
House prices are down month-over-month and year-over-year according to Case-Shiller. These are the seasonally-adjusted numbers – the non-seasonally adjusted numbers were still up .9% month over month.
Separately, home prices continue to rise, according to FHFA, with the index up .4% from May. Prices are up 5.1% year-over-year. The FHFA index is different than Case-Shiller in that it only looks at homes with a conforming mortgage, which means it excludes distressed and high end home. It is more of a central tendency index and tends to be less volatile than Case-Shiller.
Filed under: Morning Report | 105 Comments »
Posted on August 25, 2014 by Brent Nyitray
Markets are higher this morning on no real news. Bonds and MBS are up small.
Lots of economic data this week: Tomorrow we get durable goods, the FHFA Home Price Index and Case-Shiller. Thursday, we get the second revision to second quarter GDP, and Friday we get Personal Income and Personal Spending.
On GDP, note that the Street is forecasting the advance estimate of +4.0% gets revised downward to +2.4%. If that ends up being the case, we will have had almost no GDP growth for the first half of 2014.
Why have the strategists gotten it so wrong with their bond market predictions? (Mea Culpa – include me in that camp). One explanation is that they are looking only at the US and ignoring the weakness emanating out of Europe. The second explanation is that inflation just cannot be found – the rally in the dollar has depressed commodity prices and there is little to no upward pressure on wages. This also might help explain why the Fed is considering hitting some bids with its paper once QE ends.
Another corporate inversion story: Burger King is apparently in talks to buy Canadian-based Tim Horton’s. Note Walgreen’s decided to scrap their plans for moving their headquarters and the stock got demolished.
The takeaway from Jackson Hole? Labor markets need to heal more before the economy can weather higher interest rates. Wage growth is flat right now. In order to get to the Fed’s 2% target on inflation, we would need to see wage growth of around 4%, because productivity-driven increases are non-inflationary. This just goes to show how far we have to go. That said, the economic staff at the Fed has taken down its estimate of the potential non-inflationary GDP growth, so there might not be as much slack as people think.
Filed under: Morning Report | 12 Comments »
Posted on August 22, 2014 by Brent Nyitray
Markets are lower this morning on no real news. Bonds and MBS are flat.
Dull Summer Friday with no economic news. Janet Yellen is scheduled to hold a press conference at 2:30 EST, so there is the possibility of something coming out that could move bonds.
The Washington Post has a breakdown on the Bank of America / DOJ settlement. Although the headline amount is $17 billion, it looks like they will actually pay closer to $12 billion. Of the homeowner relief, they may run out the clock on principal modifications and drag them out, as JP Morgan is doing.
Nonvoting St Louis Fed President James Bullard argues there is less slack in the labor market than the Fed’s statements imply. He argues that it is the unemployment rate and payroll growth that matters, and that the labor force participation rate doesn’t add much information and is outside the purview of monetary policy. He is probably correct in that regard – I don’t really see how 25 basis points one way or another on the Fed Funds rate is going to affect the long-term unemployed. That said, I don’t think they move meaningfully until we start seeing wage inflation. That doesn’t rule out a symbolic increase in the Fed Funds rate sometime next year. Separately, Charles Plosser thinks we should raise rates this year.
Filed under: Morning Report | 7 Comments »
Posted on August 21, 2014 by Brent Nyitray
Markets are higher after another sub 300k initial jobless claims number. Bonds and MBS are flat.
Existing home sales rose to a 5.15 million annual pace, according to NAR. Median Home Prices are up 4.9% to $222,900. Distressed sales made up 9% of all sales, the lowest percent since 2008. First time buyers inched up to 29%, and all-cash buyers ticked down to 29%. Days on Market increased to 48.

In other economic data, the Index of Leading Economic Indicators ticked up to .9% from an upward-revised .6% in June. The Philly Fed Manufacturing Index was strong at 28.
There was nothing earth-shattering in the FOMC minutes. One thing did jump out at me, and it was the fact that they lowered their estimate for the potential GDP growth rate. They revised their GDP forecast downward and also said that unemployment was closer to its natural rate. This effectively lowered the “speed limit” of the U.S. economy, and in a way, waves the white flag over the plight of the long-term unemployed. Of course there is probably not much monetary policy can do for the long-term unemployed in the first place, but that is a separate issue. I guess the Fed is seeing wage growth somewhere (not sure where, aside from skilled labor), and they think we are closer to seeing inflation flare up for the whole economy. The punch line is that, at the margin, rates may be going up sooner than anticipated.
Speaking of inflation, thanks to the recent rally in the US dollar, commodity prices are getting slammed. Oil is down 13% in the last two months, natural gas is down 20%, corn is down 17%, and bonds are rallying. Not seeing where the inflation is going to come from. Fun fact: Spanish 10 year bond yields are now lower than the US 10 year. Remember the PIIGS of the European Sovereign Debt Crisis? Their bond yields are generally in line with ours: Portugal is 3.26%, Italy is 2.59%, Ireland is 1.88%, Greece is 5.78% and Spain is 2.39%. Kind of amazing when you think about it. The point is that you can’t look at US rates in a vacuum – worldwide sovereign yields are rallying, and it is pulling US yields lower as well.
Bank of America settles with the DOJ for $17 billion. BOA’s purchase of Countrywide will probably go down in history as one of the most ill-advised mergers ever, along with Time Warner’s purchase of AOL, and Warren Buffet’s purchase Johns Manville’s asbestos liability stream. Separately, while the government dropped its criminal case against Angelo Mozillo, they are still going after him in a civil case.
Filed under: Morning Report | 26 Comments »


 Brent Nyitray
 Fairlington Blade
 Let the mutherfuker burn!
 jnc4p
 Kevin S. Willis
 Michigoose
 lmsinca
 markinaustin
 Arcanaut
 novahockey
 quarterback
 ScottC
 yellojkt