Bites and Pieces: The Book

Hi all,

I was searching through some old comment threads to track down a particular response of Scott’s awhile ago. In the course of doing that, I saw a lot of interesting Bites & Pieces posts. Some of which I’d completely forgotten about.

I was thinking about going through them and compiling the Bites & Pieces into one record for ATiMers, past and present. Perhaps an exercise for when I’m in Sequesterville. We are forbidden by law from doing anything work related while on furlough, so I may as well make some use of my time.

∂ß

Morning Report – Life after Fan and Fred 02/25/13

Vital Statistics:

  Last Change Percent
S&P Futures  1521.4 6.8 0.45%
Eurostoxx Index 2688.7 58.6 2.23%
Oil (WTI) 94.04 0.9 0.98%
LIBOR 0.287 -0.002 -0.52%
US Dollar Index (DXY) 81.11 -0.368 -0.45%
10 Year Govt Bond Yield 1.98% 0.02%  
RPX Composite Real Estate Index 194.5 0.2  

Markets have a risk on feel this morning on no real news.  Elections are being held in Italy, with Bersani on track to win. Italian sovereign yields have tightened 20 basis points in response. Bonds and MBS are down.

Sequester week. Bob Woodward had a column over the weekend that said, WH protestations aside, that the sequester was Obama and Lew’s idea in the first place. The WH is releasing all sorts of gloom and doom scenarios about what will happen if sequestration happens. Republicans seem to be content to allow the cuts to happen. FWIW, I do not believe the markets care one way or the other about the impending sequester. 

The Chicago Fed National Activity Index showed growth moderated in January, falling to -.32 from a revised +.25 the previous month. Production related indicators explain most of the weakness, although employment and consumption also were negative contributors. The 3 month moving average is still in positive territory, indicating that economic growth continues to be moderately above trend.

The Bernank will be testifying in front of Congress this week. These things tend to be partisan dog-and-pony shows where the questioners are more interested in getting the Fed Chairman to validate their worldview than they are in seeking actual answers.  Democrats will undoubtedly be pushing for Bernake to say that sequestration will be an economic nightmare, while Republicans will be pushing for him to say that spending and the debt pose a problem. Democrats will also be looking for support for raising the minimum wage. Republicans will probably want to drill down a bit on the end of QE. 

The Bipartisan Policy Center has released a report on the future of housing and the GSEs. With the government guaranteeing 90% of all mortgages these days, there is a push in Washington to get the private sector more involved. They envision phasing out Fan and Fred and replacing them with a “public guarantor,” who has a re-insurance role, stepping in only when private insurers are unable to make good on the loan. They also propose that the government get involved with providing affordable rental housing. 

Boston

I just had to get Bon Jovi off the front page.


Is anybody going to be in Boston in a couple of weeks?  I fly in on Friday, 3/8, and don’t have to be out to Woods Hole until the next day; where’s a good place to stay/eat?  I’ve been through Boston several times now, so know how to use their version of the Metro, but haven’t found a hangout I like yet.

Sorry. Really.

Look, I’m sorry. But this was on the radio yesterday morning, it’s been on a loop in my head since then. And the only way to get it out is to give to someone else.

FY2013 CR & 02/21/2013 Open Thread

New NYT piece with some good info on the next stage of the budget fight, the continuing resolution to fund the government through the rest of FY2013 (i.e. through September 30, 2013).

“Taking steps to avoid a full government shutdown at the end of March, the House Appropriations Committee as soon as next week will introduce legislation to keep the government financed through Sept. 30, the end of the fiscal year, but do nothing to stop the pending cuts.”

…

“The Senate next week will consider competing Democratic and Republican proposals to stop the automatic cuts. The Democratic plan would institute a 30 percent minimum tax rate on incomes over $1 million, cut farm subsidies, and institute military cuts delayed until most United States troops have returned from Afghanistan. Neither plan is expected to win the 60 votes needed to overcome a filibuster

Instead, attention will shift to the next deadline, March 27, when financing for the government runs out.

The House bill would maintain financing at presequester levels, $1.043 trillion, with detailed spending instructions for defense programs devised to give the Pentagon more flexibility. But a provision in the spending bill will say that all levels are subject to automatic cuts to be meted out by the White House Budget Office.”

http://www.nytimes.com/2013/02/21/us/politics/gop-resisting-obama-on-tax-increase.html?pagewanted=2&_r=1&gwh=E1189D5B5E182F1909E62B46AA43A452&ref=politics

If the House is really going to let the baseline be set at pre-sequester levels for the CR, this could constitute a cave for the Republicans. I.e. the sequester was actually in effect for about 1 month tops and now spending is going to be held flat at the old levels.

Update: Good piece by Karl Rove on the various options. I agree with his proposal:

“My own recommendation is that House Republicans should pass a continuing resolution next week to fund the government for the balance of the fiscal year at the lower level dictated by the sequester—with language granting the executive branch the flexibility to move funds from less vital activities to more important ones.”

http://www.rove.com/articles/450

President’s Day Open Thread – 02/18/2013

Open thread for links, etc.

New York considers passing a law making previous employment condition a basis for a discrimination lawsuit when an applicant is denied a job. What could go wrong?


Morning Report – Housing Market Outlook 02/15/13

Vital Statistics:

  Last Change Percent
S&P Futures  1518.0 -0.5 -0.03%
Eurostoxx Index 2632.2 -3.2 -0.12%
Oil (WTI) 96.64 -0.7 -0.69%
LIBOR 0.29 0.000 0.00%
US Dollar Index (DXY) 80.52 0.066 0.08%
10 Year Govt Bond Yield 2.01% 0.01%  
RPX Composite Real Estate Index 192.7 -0.4  

Markets are flattish on no real news. The Empire State Manufacturing Survey showed improvement in NY State for the first time in months. Bonds and MBS are flat.

Elizabeth Warren is fighting to keep the CFPB from being accountable to Congress. Senate Republicans are pushing to have the Bureau subject to annual appropriations and installing a 5 member board to increase transparency and accountability. Liberals are pushing for a straight up and down vote on Richard Cordray, who was installed through a recess appointment. 

Dr. Cowbell was on Bloomberg TV this morning pushing for the Fed continue ZIRP as long as possible, in order to sustain the US housing recovery.  He blames Japan’s lost decade on premature tightening by the Bank of Japan. He made is usual push for infrastructure spending and said we don’t have a debt problem. Of course the Fed is keeping the bond vigilantes at bay. Can they do so forever? 

Freddie Mac has released their 2013 Economic and Housing Market Outlook. Like Krugman, they note the nascent strength in housing and estimate that it could add .5% to GDP this year.  They see the 30 year fixed rate mortgage at 4% by Q413, with unemployment at 7.5% and housing starts at 1 million. They forecast that originations will fall by 15% this year as refis drop from a 75% share to a 40% share.  

Senate Democrats unveiled a plan to delay the sequester by replacing the non-defense discretionary spending cuts with tax increases and maintaining defense cuts. Of course it has zero chance of going anywhere –  it is more of a demagoguing opportunity for the President and an attempt to give the Heisman to an idea that was his to begin with.  It is increasingly looking like there will not be a deal on the sequester, so it will either (a) happen, (b) get delayed for a year, or (c) happen and then get fixed in the continuing resolution. 

Note:  The MR will be spotty next week as I will be on the Left Coast.

Morning Report: QRM vs QM 02/14/13

Vital Statistics:

  Last Change Percent
S&P Futures  1515.2 -2.0 -0.13%
Eurostoxx Index 2637.2 -19.7 -0.74%
Oil (WTI) 97.3 0.3 0.30%
LIBOR 0.29 0.000 0.00%
US Dollar Index (DXY) 80.52 0.426 0.53%
10 Year Govt Bond Yield 2.05% 0.02%  
RPX Composite Real Estate Index 193.1 -0.4  

Markets are weaker this morning in spite of better than expected initial jobless claims and couple of new mergers (Berkshire Hathaway buying Heinz, and US Airways / American Airlines). The Eurozone economy weakened. Bonds and MBS are flat.

In the State of the Union, President Obama referred to “overlapping regulations” and called for streamlining the mortgage process.  The housing industry is hoping that means that the Qualified Residential Mortgage rule (promulgated by the banking regulators) and the Qualified Mortgage Rule (promulgated by CFPB) will become consistent with each other.  The sticking point is that the QRM rule is much more strict than the QM rule (QRM: 20% down, 36% DTI), vs QM (43% DTI). Bankers and consumer groups hope to have the down payment rule removed, and would ultimately like to see the QRM rule to match the QM rule.  It seems that there is some bipartisan consensus on this.

Speaking of the SOTU, Obama’s agenda drew little support from Republicans, who “called it dead in the water.”  John Boehner objected that his plan raises the price of employment and noted that when you increase the cost of something, you get less of it.  Mitch McConnell referred to it as “liberal boilerplate that any Democratic lawmaker could have given at any time in recent memory.”  John Thune noted that Obama would have a hard time getting Democrats to go along with portions of it.  Six Senate Democrats seeking re-election next year in states that supported Mitt Romney are going to be hard pressed to vote fore new tax revenues beyond what has already been approved.  At the end of the day, it will depend on whether Obama chooses to demagogue or deal. On the minimum wage, one Republican said it would have a chance if it was accompanied by a business package of tax credits and expensing rules to help small business.  Paul Ryan noted that Obama chose not to politicize immigration reform, which means that something can be done there.

Sen Tom Coburn, R-OK says the sequestration cuts are going to happen. I still think it is much ado about nothing.  Some facts:

Spending Side:

  • Total Sequestration cuts:  $85 billion
  • Requested increase in the budget from FY12 – FY13: $75 billion
  • Net change in spending: ~ $10B (or about 6 basis points of GDP)
Revenue Side:
  • Payroll tax Holiday expiration:  $160 billion
  • Tax hike on the rich:  $40 billion
  • Obamacare tax hikes $42 billion
So we have added $242 billion in new revenue this year (which apparently won’t hurt the economy) yet we are wringing our hands over the fact that the government is being asked to make do with what it got last year, which, at 24% of GDP, is pretty much a post-WWII high. Call me an optimist, but I don’t think anyone outside of the Beltway is even going to notice if the sequestration cuts happen. 

St Louis Fed Head James Bullard gave an upbeat presentation at Arkansas State University, noting that the Euro sovereign debt crisis seems to have calmed down and that some of the uncertainty in the US economy has been dissipating. The most important news came with the Q&A with reporters – he is not ready to call for an end to QE, and would defer any decision-making until this summer to see if the economy continues to improve. 

Morning Report – CoreLogic Market Pulse -2/13/13

Vital Statistics:

  Last Change Percent
S&P Futures  1518.8 2.6 0.17%
Eurostoxx Index 2656.9 8.1 0.30%
Oil (WTI) 97.85 0.3 0.35%
LIBOR 0.29 -0.002 -0.68%
US Dollar Index (DXY) 79.98 -0.125 -0.16%
10 Year Govt Bond Yield 2.00% 0.02%  
RPX Composite Real Estate Index 193.5 0.3  

Markets are up slightly after retail sales came in as expected. Ex auto and gas, they disappointed. However, there was some fear that the Jan 1 tax hikes would curtail consumer spending.  At least this data point shows it hasn’t.  Although to be fair, a +.1% increase is nothing to write home about. Mortgage applications fell. 

CoreLogic’s latest Market Pulse previews 2013. They predict that the refi boom is over, but it will be some time before the purchase market comes back. They note that 2012 census data indicates that household formations increased by 1 million, which is getting back to normalcy.  As I have said before, there is a lot of pent-up demand here, as the low household formation numbers of the last 5 years have been driven by economic weakness, not demographics. They do forecast that margins may get compressed as lenders fight over a declining amount of activity. That said, you can’t turn a refi shop into a purchase shop overnight. They also do an interesting analysis of the expected effect of QM loans. Near term, it will probably increase the profile of the GSEs.  Longer term, it will greatly increase performance characteristics.  Anyway, lots of good stuff in here.  RTWT.

27% of borrowers who refi are shortening their terms, according to Freddie Mac.  Cash-out refis account for just 16% of refinances, while cash in refis have jumped to 39%.  Ironic that consumers are getting more conservative when the Fed is using every tool in its toolbox to get consumers to do the exact opposite. 

Looks like the sequestration cuts are going to happen.

Morning Report – S&P swings back 02/12/13

Vital Statistics:

  Last Change Percent
S&P Futures  1513.0 -0.1 -0.01%
Eurostoxx Index 2631.2 8.6 0.33%
Oil (WTI) 97.59 0.6 0.58%
LIBOR 0.292 -0.001 -0.34%
US Dollar Index (DXY) 80.28 -0.031 -0.04%
10 Year Govt Bond Yield 1.97% 0.00%  
RPX Composite Real Estate Index 193.2 -0.1  

Markets are flattish as the G-7 countries promise not to target currency rates with economic policies. Barclay’s is cutting 3,700 jobs. The President gives his state of the union address tonight, and it will focus on the economy and job creation.  Bonds and MBS are flat.

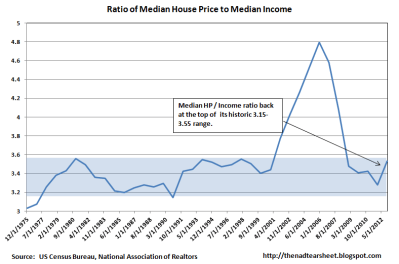
The National Association of Realtors reported that the median price of an existing home rose 10% in Q411 to 178,900 from 162,600 in Q411. That puts the median house price to median income ratio roughly at 3.53x, which is towards the top of its historic 3.15 – 3.55x range. This begs the question:  Is housing overvalued?  Perhaps, but wages have gone nowhere for 6 years.  Perhaps this time, wages catch up.

Chart:  Median House Price to Median Income Ratio:
 

The National Federation of Independent Businesses released its Small Business Optimism survey, and while it increased, it was still a dismal reading. On the plus side, more small business owners are hiring than firing. Capital Expenditures are increasing, although they are still in maintenance mode. Overall, the report suggests that sentiment is improving, albeit from very low levels.

McGraw Hill (owner of Standard and Poors) comes out swinging against the DOJ in their latest earnings release. They point out that the US cherry-picked a few emails, and that alone is only evidence of an atmosphere of “vigorous debate” but not wrongdoing.  They note that they were downgrading CDOs with 2006 vintage RMBS a year and a half before Lehman failed (which actually co-incides with the beginning of the financial crisis, IMO).  I remember the credit markets beginning to freeze in the summer of 2007, which was being called a “buyers strike.”  Finally, they note that virtually everyone missed the housing bubble, and the fact that their actions proved to be insufficient in hindsight does not prove intentional misconduct at S&P.

The state of Nevada is taking steps to reduce shadow inventory by buying distressed pools of mortgages and working them out to reduce principal.  They will purchase homes at 70% of appraised value and re-work the loan or foreclose and re-sell the property.  It will be administered by a non-profit entity. It will be funded with receipts from the National Mortgage Settlement. Once the loan has been seasoned as a re-performer, it will be sold back into the market and the money recycled.