Morning Report – Jobs day 03/08/13

Vital Statistics:


Last

Change

Percent

S&P Futures 

1547.8

3.4

0.18%

Eurostoxx Index

2744.5

42.6

1.40%

Oil (WTI)

91.3

-0.2

-0.27%

LIBOR

0.281

0.001

0.36%

US Dollar Index (DXY)

82.41

-0.045

-0.05%

10 Year Govt Bond Yield

2.06%

0.05%


RPX Composite Real Estate Index

194.9

-0.3


Markets are higher this morning after a positive jobs report. Payrolls increased by 236k in Feb, higher than the 165k forecast. January was revised down. The unemployment rate fell to 7.7% from 7.9%, however the labor force participation rate fell as well, which means that number isn’t as great as it initially appears.  Bonds are getting clocked, with the 10-year solidly above 2% again. MBS are down as well.

The rally in the stock market and rebounding house prices has returned US wealth to its pre-crash levels. Of course the main driver has been the stock market, not real estate, so don’t expect this to get us back to pre-crisis levels of consumer spending.  Still, its a start.

The Fed has released the results of its stress tests for the banks. The stress test is a scenario of 12.1% unemployment, a 50% drop in the stock market, and a 20% drop in real estate.  They predict that Tier I capital would fall from 11.1% to 7.7%, which is still above minimum standards.  

Morning Report – Regulating from the Ivory Tower 03/07/13

Vital Statistics:

  Last Change Percent
S&P Futures  1541.8 2.7 0.18%
Eurostoxx Index 2690.5 10.6 0.40%
Oil (WTI) 90.67 0.2 0.27%
LIBOR 0.281 0.001 0.36%
US Dollar Index (DXY) 82.41 -0.045 -0.05%
10 Year Govt Bond Yield 1.96% 0.03%  
RPX Composite Real Estate Index 194.9 -0.3  

Markets are slightly higher after initial jobless claims came in lower than expected at 340k. Productivity fell as unit labor costs increased at a faster clip than expected. The ECB kept rates unchanged. Bonds and MBS are lower.

The Fed released the Beige Book yesterday, a sort of 10,000 – foot view of the economy. The words “modest” and “moderate” were used a lot. Residential Construction increased in most districts with the exception of Kansas City. Low inventories were squeezing prices higher in most districts. Banks reported that credit standards are beginning to loosen, and that very few mortgages are being held on their balance sheets. 

The CoreLogic Home Price index increased 9.7% in January, the biggest increase since April 2006. Excluding distressed sales, they increased 9.0%. They anticipate a similar gain of 9.7% YOY for Feb, with a .3% month on month drop. This year’s seasonal slowdown has barely registered, which portends well for the summer selling season. Only Illinois and Delaware failed to report gains. 

Now that the sequestration crisis is out of the way, it looks like the threat of a government shutdown late this month has gone away as well.  The House passed a bill to fund the government through the rest of the year at sequestration levels. The Senate will make its own tweaks to soften some of the spending cuts, but there is a bipartisan optimism that we won’t have a shutdown. Separately, the President met with Congressional leaders in an attempt to figure out if there is room for a grand bargain on a package of tax increases and entitlement cuts. Lest the market think the all-clear has passed, we still have the debt ceiling to deal with in late summer.

The Mortgage Bankers Association responded to FHFA Head Ed DeMarco’s plan to rationalize and eventually replace the GSEs. “Proposals of this magnitude need a transparent process to engage with stakeholders, articulate objectives and demonstrate that stakeholder concerns have been evaluated and addressed… The Administration, Congress, and regulators need to engage with other stakeholders to move the ball forward.  Until this happens, the uncertainty in the markets will persist and a full recovery of the housing market will remain elusive.”  The Obama administration still regulates from the ivory tower and refuses to consult with the private sector.  It happened in Dodd-Frank and it is happening again. I guess the concern over regulatory capture is a valid concern, but remaking the financial sector or the real estate markets without input from the people who actually do this stuff for a living is bound to have major unintended consequences.

One of the bigger issues regarding the new framework involves how to handle Federal guarantees.  The government believes it has been underpricing (in other words, G-fees are too low) and it wants to increase them so they approach the pricing for PMI. One side effect is that the mortgage insurers, once given up for dead, are back. 


Morning Report: Party like it’s 1999 03/06/13

Vital Statistics:

  Last Change Percent
S&P Futures  1544.0 6.9 0.45%
Eurostoxx Index 2698.8 15.8 0.59%
Oil (WTI) 90.51 -0.3 -0.34%
LIBOR 0.28 -0.002 -0.53%
US Dollar Index (DXY) 82.2 0.114 0.14%
10 Year Govt Bond Yield 1.94% 0.04%  
RPX Composite Real Estate Index 195.2 0.1  

Party like its 1999. Markets are stronger after the Dow set a record high yesterday. The S&P 500 has about 40 points left to hit a record as well. NASDAQ, well.. about another 60% needed there. No real market-moving news this morning.  Mortgage applications rose 14.8% last week as rates fell. Bonds and MBS are victims of the “risk on” trade and are moving lower. 

The ADP February Employment Report estimated jobs increased by 198k last month, higher than the Street estimate of 170k. This probably means the street estimate for non-farm payrolls scheduled to be released on Friday is low at 160k. The increase was mainly in services. On the good-producing side, construction drove the increase. Coupled with the consumption numbers we have seen, it appears that the real economy is taking the Jan 1 tax increases in stride. Perhaps the sequester will end up being a nonevent as well.

Altos is forecasting home prices will rise 10% in 2013, which puts them at the high end of estimates. They cite three big indicators all pointing to higher prices:  First, the percent of homes with price reductions is falling, and below a normal market.  A normal reading is 38%, which makes sense – you overprice and if no one bites, you go lower.  A weak market would have price reductions in the 40% – 50% range, while a hot market would have about 15%.  We are currently at 28%, somewhere between “normal” and “hot.”  Blame professional investors and low inventory. Second, the price of newly-listed properties is on the upswing.  Third, median days on the market is falling.  Quickly. 

So what happened to this massive glut of supply that was supposed to hit the market?  Well, first of all, new home construction has been anemic. Yes, housing starts have been increasing at a pretty good clip, but we are still not cracking a million per year pace, and 1.5 million a year has been the historical norm. Second, now that prices are increasing, many homeowners who are under no pressure to sell are deciding to hang on a little longer. Finally, the government is doing everything it can to stimulate demand (through FHA lending, QE, etc) and decrease supply (through HARP, HAMP, and other refi programs to keep people in their homes). So far, 2013 is shaping up to be a year of high-ish price appreciation in the context of restricted supply.

Morning Report. Volcker: “There’s a lot of liquor out there now.” 03/05/13

Vital Statistics: 

  Last Change Percent
S&P Futures  1531.2 5.5 0.36%
Eurostoxx Index 2659.6 39.8 1.52%
Oil (WTI) 90.65 0.5 0.59%
LIBOR 0.281 -0.002 -0.71%
US Dollar Index (DXY) 82.08 -0.115 -0.14%
10 Year Govt Bond Yield 1.89% 0.02%  
RPX Composite Real Estate Index 195 0.2  

Stocks are higher this morning on no real news. China re-affirmed its growth target of 7.5% GDP. European ministers opened the way for looser budget policies after the Italian election results. In spite of that, Euro sovereigns are generally stronger this morning. Generally, the market has a “risk on” feel to it, and bonds / MBS are lower.

Acting FHFA Chairman Ed Demarco laid out the plan for dealing with the GSEs. Fannie and Fred would be merged, slowly dissolved and a new entity would take their place. The new entity would be owned and funded by Fan and Fred, but would have its own CEO and Chairman and be in a physically separate location. Left undecided is exactly what role the government will have in the mortgage market. The government seems to be leaning in the direction of focusing on low income / VA products, and acting as a re-insurer.  That said, it is up to Congress to figure out what the the exact role will be. The securitization arm could be nationalized, turned into a utility, or privatized.

The GSEs owe the government something like $120B and it is estimated that it would take another $200 – $250 billion to capitalize them enough so that they could stand on their own.  The government is in a pickle on this one. On one hand, if the government nationalizes Fan and Fred, all of their debt becomes sovereign debt, with the attendant effects on our debt / gdp ratios. On the other hand, there is no way to raise $350B in the private markets. And the chances of getting a $350B appropriation for the GSEs in this Congress is probably too much to ask as well.  Given that the government backs 90% of all new mortgages it is probably safe to say they won’t make any major changes until private financing takes some of the load. 

Ex Fed Chairman Paul Volcker is warning that removing the central bank stimulus will be difficult and the temptation will be to stay too long.  “You can make a mistake and go too quick, but the much more frequent mistake is you go too slow, because its never popular to take the so-called punch bowl away or to weaken the liquor.” Of course after the equity bubble burst, the Fed kept the punch bowl out so long that the real estate market went on a 5 year bender and then wrapped the car around a tree. Almost on cue, Janet Yellen, as the good co-dependent / enabling wife, is out there saying that the “potential costs of asset purchases definitely need to be monitored over time and she did not see any that would cause me to advocate a curtailment.” Meanwhile, the stock market is approaching all-time highs, the VIX is at 14, and S&P 500 earnings have been dropping every quarter since Q212…

Bites and Pieces: Eat Your Sprouts

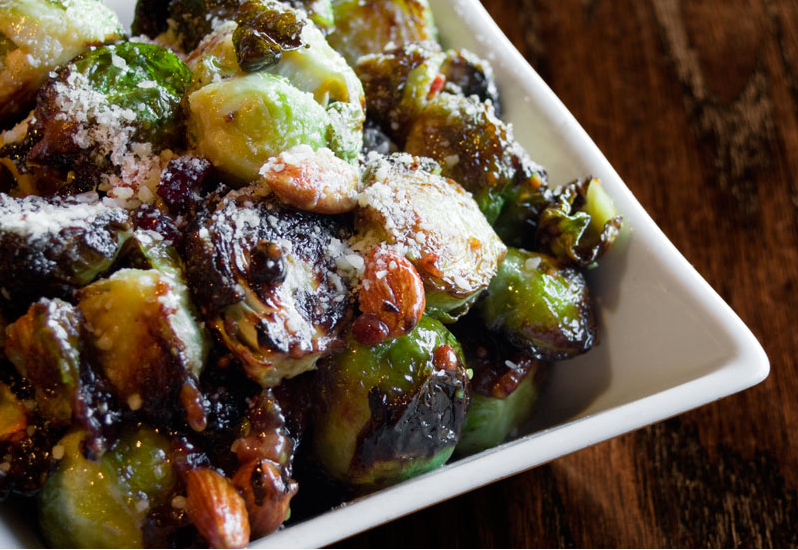
Brussels sprouts have a well-deserved reputation amongst children for being one of the nastier things they’re forced to choke down. They manage to combine insipid flavor with a mealy texture. You can imagine my surprise when my wife came back from a trip gushing over these amazing Brussels sprouts she’d had. She went to a place in Kansas City called PizzaBella. They roast Brussels sprouts with pancetta, cranberries, almonds, and vinaigrette. Looks a lot more appetizing than cream of Brussels sprouts, no?
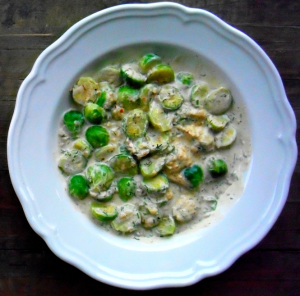
Creamed Brussels Sprouts
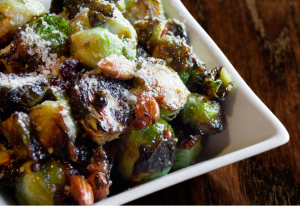
Creamed Brussels Sprouts

PizzaBella Brussels SProuts

Sprouts from Pizza Bella

Brussels sprouts have been a fixture in our household ever since. You can find plenty of recipes out there for roasted Brussels sprouts. Here’s an example from the good folks at Epicurious (originally published in Gourmet magazine).

Roasted Brussels Sprouts

Ingredients

1 pound of Brussels sprouts, halved

2 oz. of diced pancetta

1 garlic clove, minced

½ tablespoon olive oil

salt and pepper to taste

Method

Combine everything and spread in a single layer in a baking pan. Roast in 450 degree oven, stirring after about ten minutes, until sprouts are browned on the edges and tender. Add a bit of water to the pan when done to get the brown bits . Serve warm.

Not bad. One could add the cranberries and almonds and get reasonably close to that served up by PizzaBella. I find a bit of sweetness works well in this sort of dish, so some pomegranate juice adds a nice touch. Still, one isn’t going to approach what you get from a good pizza oven at home. I wanted proper caramelization and wasn’t going to get that from the oven alone.

Enter my cast iron pan. If I want a good steak, I sear it on both sides and put it in the oven until it’s medium rare. [If I want a great steak, I’ll put it in a low temperature oven until medium rare and then sear it.] So, I sear the cut sides of the Brussels sprouts, toss in the other goodies, and then finish in the oven. It’s a pain to halve and place the Brussels sprouts, but the center gets pretty mealy by the time whole sprouts are cooked.

Caramelized Brussels Sprouts with Almonds, Cranberries, and Pomegranate

Ingredients

1 pound of Brussels sprouts, halved

¼ cup of olive oil

¼ cup of slivered almonds

¼ cup of sweetened, dried cranberries (Craisins)

½ cup of pomegranate juice

salt and pepper to taste

Method

Heat the oven to 400 degrees. Put a case iron skillet over med-high heat and add olive oil. When the olive oil is shimmering (not smoking), add the Brussels sprouts, cut side down. Cook until they develop a good brown crust, several minutes. Add the cranberries and almonds (if using) and use a metal spatula to get the Brussels sprouts off the pan and mix briefly. Pour in the pomegranate juice and put into the oven until the sprouts are just cooked through. Serve with a bit of grated Parmesan cheese.

Some variation on this has been my go to dish until recently, when I started playing with unusual ingredients for different cuisines. I tried my braised squid concept, using an Indian recipe for chicken with tomatoes, yogurt, ginger, garlic and the usual spices. We had a big bag of Brussels sprouts in the kitchen and I decided to try cooking them with an Indian flare. And so here we have it.

Curried Brussels Sprouts

Ingredients

½ pound of Brussels sprouts, halved

¼ cup of ghee (I used two tablespoons each of clarified butter and canola oil)

½ cup chopped onions

1 teaspoon minced ginger

1 teaspoon minced garlic

¼ teaspoon red chili powder

½ teaspoon ground coriander

½ teaspoon ground cumin

½ teaspoon ginger powder

1 teaspoon ground cinnamon

Method

Heat the oven to 400 degrees. Put a cast iron skillet over med high heat. Add the ghee until shimmering. Add the onions and cook until browned. Add the ginger, garlic and spices and cook until the fat begins to separate. You might need to add a bit of water, a technique known as bhunao.

Place the Brussels sprouts, cut side down, and cook for several minutes. Scrape the Brussels sprouts from the bottom of the pan with a metal spatula and toss slightly. Put the pan in the oven and cook until the sprouts are tender, about ten minutes. I’ll post a separate B&P update for the curried squid with coconut/saffron rice.

Since starting this post, I tried a third variation. The first two are good, but go into the category of anything tastes good if you add enough butter. I wanted to make sprouts that might be a bit healthier. Well, that and I was out of butter. But I did have cheese! I also had some leftover sliced and spiced apples from an apple pie that I’d made. As a slice of cheddar cheese is a classic topping for apple pie, I had my inspiration.

 Brussels Sprouts with Apples and Cheese

Sprouts no cheese Sprouts and Cheese
Ingredients

½ pound of Brussels sprouts, halved

2 tablespoons of vegetable oil (I used canola)

1 Granny Smith apple

1 tablespoon sugar

½ teaspoon cinnamon

¼ teaspoon ginger

¼ teaspoon allspice

Optional: ½ cup of grated cheddar cheese

Method

Peel and slice the apple, then toss with sugar and spices. Set aside.

Heat the oven to 400 degrees. Put a case iron skillet over med-high heat and add vegetable oil. When the oil is shimmering, add the Brussels sprouts, cut side down. Cook until they develop a good brown crust, several minutes. Add the sliced apples and use a metal spatula to toss everything together. Put into the oven for ten minutes.

Optional: After five minutes, sprinkle shredded cheese over the sprouts and apples and return pan to oven for another five minutes.

Note: use whatever combination of spices you prefer for apple pie. I actually used some leftover sliced apples from an apple pie. I had tossed the apples with lime juice to prevent them from darkening until I assembled the pie. You can also toss in some minced ginger and garlic if you like.

∂ß

Morning Report – The new normal?

Vital Statistics:

  Last Change Percent
S&P Futures  1514.3 -2.2 -0.15%
Eurostoxx Index 2616.9 0.2 0.01%
Oil (WTI) 90.76 0.1 0.09%
LIBOR 0.283 -0.001 -0.35%
US Dollar Index (DXY) 82.31 -0.004 0.00%
10 Year Govt Bond Yield 1.84% 0.00%  
RPX Composite Real Estate Index 194.9 0.2  

Markets are slightly lower this morning after China imposed new measures to slow its housing bubble. There isn’t much in the way of economic data this week with the exception of the jobs report, which was moved to this week.  Bonds and MBS are flat.

While the unemployment rate stays stubbornly in the high 7s, there are signs under the surface that things are getting better.  The median duration of joblessness fell to 16 weeks in January from 25 weeks in June 2010. American aged 45-55 experienced the biggest turnaround, and this would address one of the biggest achilles heels to the economy:  that many people in their prime earnings years are on the bench, which crimps spending.  Nobel Laureate Dale Mortensen views this as evidence that the US labor market will not enter hysteresis, or permanently higher joblessness, which happened in Europe in the 80s. 

Is slower economic growth the “new normal?” There are a few explanations why the economic recovery has been so slow.  The first is simply bad luck. A series of exogenous events (the Euro crisis, crises in Washington, the Japanese tsunami) keep delivering blows to the economy just as it is getting going.  The second is the view of Kevin Warsh, which holds that bad policy decisions in the aftermath of the financial crisis – overregulation and a focus on short-term stimulus measures) have left the economy weakened.  The last is the view of the Keynsians, who argue that the stimulus was not enough, we need to do more, and as long as the bond market is willing to lend to us at sub 2% rates, we should borrow as much as we need to upgrade our infrastructure and hire millions of unemployed workers in the process. 

FWIW, I believe that all of these explanations have a kernel of truth, but miss the big picture – that we are recovering from an asset bubble, and the de-leveraging that follows takes a long time to work through. When people borrow en masse to fund asset purchases, the debt remains even if the asset falls in value. That debt has to be dealt with, and someone has to eat the losses. While Washington would love to figure out a way to short-circuit this process, there isn’t a good way to do it.  Much of the policy debate in Washington has centered over who should shoulder the costs, but you can’t make them go away. And until they are dealt with, they will act as a drag on the economy.

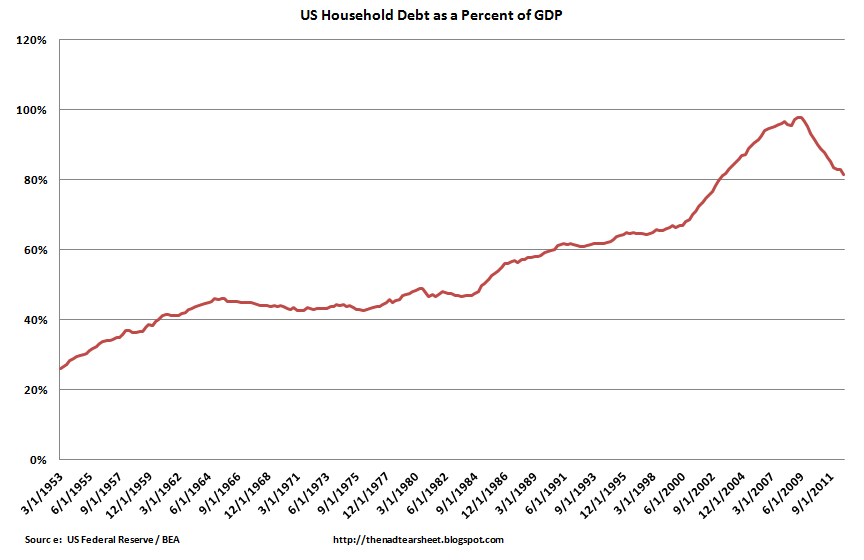
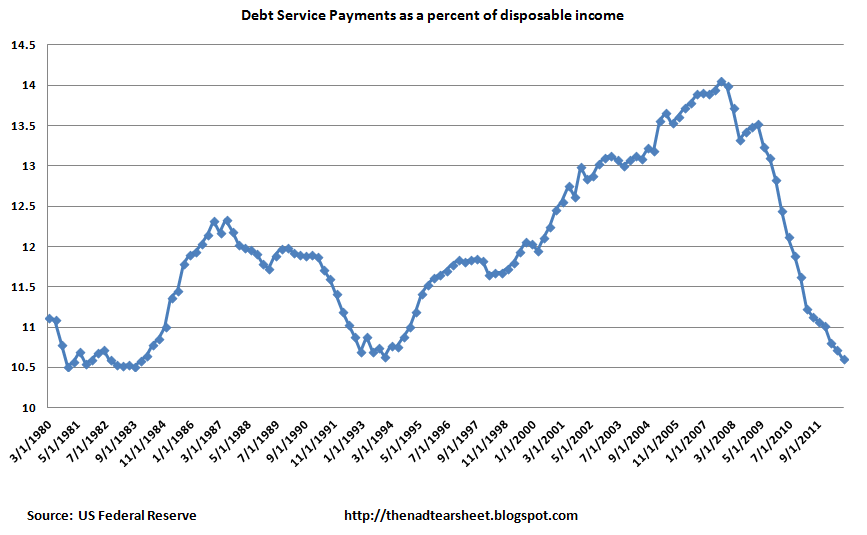
Luckily, corporate America is awash in cash.  They are done deleveraging.  The banks are still working their way through it, and no one really knows where they are marking some of their dodgier paper. Households are a mixed bag.  Debt service (the amount of principal and interest payments) is at multi-decade lows, however the total amount of debt is not. We have some ways to go here. The recovery will be made on two fronts – debt will be slowly paid down, while real estate prices will continue to rise.  And that is why the Fed is doing QE – to (officially) cut down debt service payments, and to (unofficially) help goose the real estate market.

Chart:  US Household debt as a percent of GDP:

Chart:  Debt Service Payments as a multiple of disposable income


But ZIRP and QE isn’t “free.” Unintended consequence of ZIRP # 547,624 – a bubble in student loan paper. Sallie Mae just sold $1.1 billion of securities backed by private student loans (in other words, not backed by the Federal Government) and the riskiest tranches were 15x oversubscribed. This year alone, dealers sold $5.6 billion of student loan backed securities, with an average yield of 1.48%.  And we have only issued about a billion dollars worth of jumbo securitizations since the bubble burst?  I find it absolutely amazing that we can securitize unsecured loans made to students majoring in underwater basket weaving, but we can’t securitize a stated income loan. Is it Dodd-Frank and its open questions regarding “skin in the game” for issuers?  If it is, I suspect the private label market will come back in a hurry once the regulators figure out what they want to do. 

Morning Report – CT Hoarders Tax. Really?

Vital Statistics:

  Last Change Percent
S&P Futures  1504.0 -9.3 -0.61%
Eurostoxx Index 2590.3 -43.3 -1.64%
Oil (WTI) 90.78 -1.3 -1.38%
LIBOR 0.284 -0.003 -1.04%
US Dollar Index (DXY) 82.3 0.349 0.43%
10 Year Govt Bond Yield 1.84% -0.03%  
RPX Composite Real Estate Index 194.7 0.5  

Stock markets are weaker this morning after disappointing economic data out of Asia and Europe. Consumer spending grew .2% in January, the first post tax-hike reading on consumption. Bonds continue to rally, and MBS are flat.

Today is sequester day. For mortgage originators, that means cuts at HUD could affect you. FWIW, I met with several HUD people last week who told me that the sequester will not affect them at all.  They have increased their headcount by something like 30% over the past couple of years and are slotted to grow that number another 20%.  They aren’t worried.  

That said, Shaun Donovan is warning that the sequestration cuts could lower the availability of FHA loans. Given that the refi boom is probably over, FHA mortgages will probably drop anyway, which means that even if capacity drops a little, demand is probably going to drop more, which will offset the effects of the sequester.

It turns out that JP Morgan’s announcement of 13000 layoffs in the mortgage division is not concentrated in origination, it is in workouts.  As the number of delinquencies decline, less resources are needed to handle mods and defaults. 

Richard Cordray spoke to the Credit Union National Association regarding the Qualified Mortgage Rule and other issues. He urged lenders to extend more credit, saying that they are “leaving money on the table” by not lending to “low risk borrowers who want to refinance.”  He also urged banks not to concentrate solely on lending to QM borrowers.  Of course QM doesn’t really provide all that much protection, and the banks know that the CFPB is also working hard to elongate foreclosure timelines. Such is the cognitive dissonance of the CFPB – they want the banks to lend, while at the same time raising their costs if the loan goes bad. 

One of FDR’s worst ideas was the undistributed profits tax, which taxed retained earnings in an effort to get businesses to hire and pay dividends.  This was controversial even in FDRs administration and certainly played a big role in the 1937 “depression within a depression.”  Well guess what, it is back, at least in the state of Connecticut, which is considering a bill (called a “hoarders tax”) that would try and force CT-based corporations to use their retained earnings to hire people or pay a tax. Of course the details haven’t been filled in and it is one of those bills that is meant to make a point, but still… If I am a new business considering where to locate, I would think hard about scratching CT off my list. 

Morning Report – 4Q GDP upward revision 02/28/13

Vital Statistics:

  Last Change Percent
S&P Futures  1516.7 0.9 0.06%
Eurostoxx Index 2616.7 4.9 0.19%
Oil (WTI) 92.98 0.2 0.24%
LIBOR 0.287 0.000 0.00%
US Dollar Index (DXY) 81.58 -0.024 -0.03%
10 Year Govt Bond Yield 1.88% -0.02%  
RPX Composite Real Estate Index 194.2 0.2  

Markets are flattish after 4Q GDP was revised upward, but less than forecast.  4Q GDP has been revised upward to + .1% from -.1%.  Initial Jobless Claims came in at 344k. NAPM Milwaukee came in BTE at 56.5. Bonds and MBS are up on the news. 

The US GDP number was disappointing (the Street was at + .5%) and a drop in defense spending was a big factor.  Don’t forget 3Q GDP came in at + 3.1%, well in excess of the current 1.5% trend.  The government’s fiscal year ends in September, and there is a “use-it-or-lose-it” dynamic that goes on.  In other words, if an agency doesn’t spend their entire budget, it will be cut next year.  So even if they don’t actually need to spend the money, they will. The net effect is that government spending tends to accelerate in Q3 and then fall in Q1. You can see this in Table 1 of the official press release.  Punch line:  Take both 3Q and 4Q GDP numbers with a grain of salt. Of course, there is a battle royale going on between the right and the left about how to frame this whole issue as everyone deals with the sequester, which makes the signal to noise ratio miniscule.

Tidbits from the Bernank’s House Testimony yesterday:  A “significant majority” of the FOMC is supportive of current policy.  The Fed would prefer that US fiscal solutions be less front-loaded. They note some progress in the labor market and haven’t seen any significant problems in market functioning. He also gave some insight into the planned exit strategy:  to let the assets run off and then drain reserves.  He said it is a “reasonable guess” that unemployment will get to 6% by 2016.

It is getting easier to raise money in the housing market. There should be an uptick in IPOs for homebuilders this year as there is still a chasm between ease of financing in the private and public markets.  While yield pigs will jump on bond issues from the recently dead, non-public entities still struggle to get access to construction loans. The homebuilders are pretty rich at the moment, sporting P/Es around 30 or so.

Jack Lew was confirmed as Treasury Secretary.  His job will be the pit bull defending government spending and pushing for tax hikes. How this affects the dollar I have no idea. 

Morning Report – Its raining money 02/27/13

Vital Statistics:

  Last Change Percent
S&P Futures  1493.5 1.1 0.07%
Eurostoxx Index 2581.6 11.1 0.43%
Oil (WTI) 92.45 -0.2 -0.19%
LIBOR 0.287 0.001 0.17%
US Dollar Index (DXY) 81.73 -0.137 -0.17%
10 Year Govt Bond Yield 1.85% -0.03%  
RPX Composite Real Estate Index 194 0.0  

Markets are flattish this morning on no real news. Italian Sovereign Yields are slightly lower after the sell-off of the last two days.  Mortgage Applications fell 3.8% last week. Durable Orders dropped 5%, which was a disappointment, but most of that looks to be due to Boeing and their battery problem.  Strip out Boeing, and orders were up 6.3%, which is a signal that businesses are starting to spend on CAPEX.  Fed Chairman Bernake will address the House Financial Services Committee today.  Bonds and MBS are rallying. For those that follow technicals, it looks like the 10 year has broken out of its bear trend of the last 4 months. 

The Bernank spoke in front of the Senate Banking Committee yesterday and seemed to tamp down speculation that the Fed intended to end QE any time soon. Remember the December minutes seemed to indicate that there was a consensus forming that purchases of MBS and Treasuries would end sometime this year.  This accounts for the 15 basis point rally we have seen in the 10 year over the past few days. He also urged the government to find a way to kick the sequester can down the road and replace it with more gradual cuts, while at the same time playing down the “fiscal armageddon” predictions.  

Bernake assured the Committee that the Fed was monitoring the unintended consequences of low interest rates and said that the risks of new bubbles were offset by companies using low interest rates to lock in low borrowing costs for a long period. Almost on cue, Bloomberg has a story regarding this exact issue, where the yield pigs are feasting on junk bonds, which “trade like dot coms.” As an aside, Radian (remember them?  the mortgage insurer left for dead in the depths of the crisis?) They just priced a convert deal, 2 1/4s up 25. Its raining money out there..

Jamie Dimon said yesterday that banks are accumulating more capital than regulators require and will not know what to do with it in two years.  “Lend it” is the obvious answer, but if you can lock up long term capital in the bond market for less than your dividend yield, what are you going to do as a CFO?  

The jumbo market is coming back. While still nowhere near pre-crisis levels, jumbo origination is up 60% from last year. While still hard to get, the loans are priced aggressively, at about a 23 basis point spread to conventionals.  A pick up in jumbo activity may well foreshadow the return of the private label market.

Morning Report – Case-Schiller 02/26/13

Vital Statistics:

  Last Change Percent
S&P Futures  1490.8 3.6 0.24%
Eurostoxx Index 2586.8 -65.1 -2.45%
Oil (WTI) 92.23 -0.9 -0.95%
LIBOR 0.287 0.000 0.00%
US Dollar Index (DXY) 81.85 0.180 0.22%
10 Year Govt Bond Yield 1.87% 0.01%  
RPX Composite Real Estate Index 194.1 -0.5  

Markets are higher after yesterday’s bloodbath.  Yesterday’s sell-off was blamed on Italian election results which caused a 32 bp sell-off in Italian sovereigns.  They have traded another 50 basis points wider this morning. The Bernank will testify before the Senate Banking Committee today.  Bonds are higher, continuing yesterday’s furious rally. The 10-year has tightened by 13 basis points and is trading at 1.87%.  MBS are flat.

The S&P Case-Schiller index of home prices rose 6.8% YOY and .88% MOM in December. The only MSA with negative growth was New York.  Separately, FHFA reported that prices increased .6% MOM in December. They note that while the foreclosure pipeline is still high, the actual number of homes available for sale is very low and falling. 

Altos has a piece on why inventory is so low. First, they cite low housing starts. From 1957 – 2002, we averaged 1.5 million units a year.  Since the bubble burst, we have been hitting around 700k. Quickly ramping up housing construction is difficult. Second, there is psychological effect of sellers who now see the light at the end of the tunnel.  Prices are rising again, and they are hoping to get out flat. Finally, the government has emphatically sided with home owners over home buyers. They are pulling out all the stops to keep inventory off the market through foreclosure mitigation and refinance opportunities for underwater homeowners.  This has the net effect of restricting supply, which is good for existing homeowners, but not so much for first time homebuyers who want in. The net result:  2013 home price appreciation should be very strong. 

In confirmation of the above, the Despot reported a 13.9% increase in 4Q sales, with comps up 7%. While they attribute some of the growth to Sandy repairs, they mainly cite the improving residential real estate market. 

In a sign that the refi boom may be over, JP Morgan plans on cutting headcount in mortgage banking by 13k – 15k in an effort to cut $3B in expenses by the end of 2014. They see cutting 3,000 – 4,000 jobs in consumer banking this year, almost entirely by attrition.  The hits keep coming….

Bob Corker is saying the ball is in the White House’s court in order to confirm CFPB acting Chairman Richard Cordray.  A January court decision that Obama’s recess appointments to the NLRB were unconstitutional is giving Republicans a chance to press for changes to CFPB in order to bring more of it under Congressional control.  They are arguing for a 5 member bipartisan board, and for the budget to be subject to the normal appropriations process.