Morning Report – dissecting the jobs report 1/13/14

Vital Statistics:

S&P Futures 1832.4 -5.3 -0.29%
Eurostoxx Index 3107.0 2.8 0.09%
Oil (WTI) 91.7 -1.0 -1.10%
LIBOR 0.239 -0.003 -1.14%
US Dollar Index (DXY) 80.72 0.063 0.08%
10 Year Govt Bond Yield 2.86% 0.00%
Current Coupon Ginnie Mae TBA 105.5 0.8
Current Coupon Fannie Mae TBA 103.8 0.1
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.46
Stocks are down small this morning while bonds continue to hold onto Friday’s gains. There is no important economic data this morning with the exception of the budget report sometime later on today.
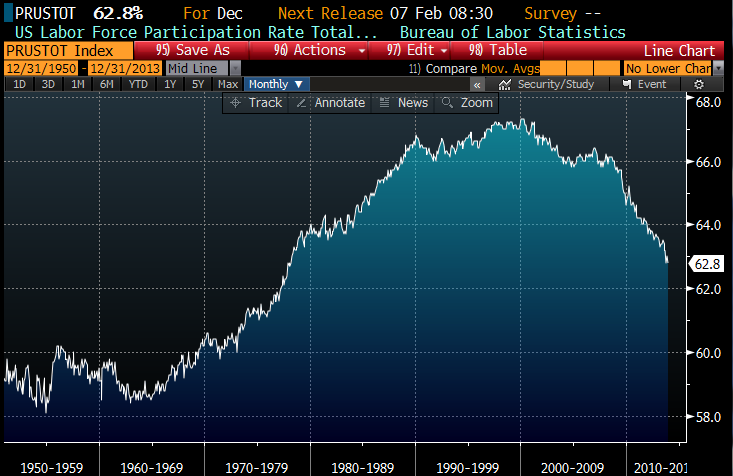
The stock market seems to be taking Friday’s jobs report as sort of a one-off, while bonds seem convinced that it signals something bigger. The most disappointing statistic in the report was the decline in the labor force participation rate to 62.8%, which means last month’s rebound was just a blip. One worrisome stat – the biggest decline in the labor force participation rate came in the 45 – 55 year old cohort. In other words, people in their prime spending years. I personally know a lot of people who were rounding the final turn towards Candy Castle and then drew the candy cane card.
This week begins earnings season, with the big banks reporting. J.P Morgan and Wells report tomorrow, Bank of America is on Wed, Citi is Thursday, and Suntrust is Friday. I’m sure we will hear about all of the woes in the origination business. From what I am seeing, margins have to be terrible for them, and a combination of lower volume and lower margins is a toxic cocktail.
Tomorrow morning we will get retail sales, which will be an important data point, particularly for estimates of Q4 GDP. Later on this week we will get housing starts and building permits. It will be interesting to see whether November’s 1.1 million print was a fluke or evidence of further strength in the housing market.

Saturday Open Thread 1/11/2014

Unlike last weekend it looks like the weather is swinging the other way (at least here in the mid-Atlantic area)–fog and rain here today and tomorrow and then warming up into the 50s early in the week. I’m guessing we have some very confused plant life out there!

Playoffs start in earnest in the NFL, and (since my Packers and the Eagles both lost last weekend) I’m reduced to hoping the Seahawks make it into the Super Bowl.

Happy weekend, all!

Morning Report – mixed jobs report 1/10/14

Vital Statistics:

S&P Futures  1837.4 4.4 0.24%
Eurostoxx Index 3111.5 21.2 0.69%
Oil (WTI) 92.63 1.0 1.06%
LIBOR 0.242 0.000 0.00%
US Dollar Index (DXY) 80.8 -0.207 -0.26%
10 Year Govt Bond Yield 2.90% -0.07%  
Current Coupon Ginnie Mae TBA 104.7 0.2  
Current Coupon Fannie Mae TBA 103.4 0.5  
RPX Composite Real Estate Index 200.7 -0.2  
BankRate 30 Year Fixed Rate Mortgage 4.54    
Markets are stronger after a mixed jobs report. Payrolls expanded at an anemic 74k in December (versus the Street expectation of 197k, and the unemployment rate came in lower than expected, falling to 6.7%. Alcoa kicked off 4Q earnings season with a miss. Bonds and MS are rallying on the news.
 
Headline statistics from the report:
  • Payrolls + 74k vs 197k expected
  • Unemployment rate 6.7% vs 7% expected
  • average hourly earnings + .1% MOM, + 1.8% YOY
  • Average workweek 34.4 hours, down .1 hour
  • Labor force participation rate 62.8% down from 63%.
The low payroll number was blamed on weather, which may explain the moves in the market. Stocks initially sold off hard and then rallied back. That said, even if you exclude the weather related effects, payroll growth was still sluggish. The labor force participation rate moved right back to its lows. The participation rate is back to levels we haven’t seen since the late 70s. To put that in perspective, roughly half of the gains in the labor force participation rate that began in the 1960s with women entering the labor force have been given back. We still have a lot of wood to chop before we get back to a semblance of normalcy. One other observation – ADP has been lousy at predicting the jobs number lately. They had the number at 238k. 
 
Chart: Labor Force Participation Rate 1950 – Present


The jobs report probably does not change the stance of the Fed, and I would expect another $10 billion reduction in QE at the Jan FOMC meeting. 
 
The Mortgage Bankers Association is forecasting $1.2 trillion in origination for 2014, the lowest level in 14 years. Banks will continue to fire people and there is still overcapacity in the system. I wonder what assumptions about cash purchase percentages they are using…

Morning Report – Spinning the Fed’s losses 1/9/14

Vital Statistics:

S&P Futures 1836.9 4.4 0.24%
Eurostoxx Index 3119.8 9.1 0.29%
Oil (WTI) 92.79 0.5 0.50%
LIBOR 0.242 0.001 0.52%
US Dollar Index (DXY) 81.05 0.026 0.03%
10 Year Govt Bond Yield 2.97% -0.02%
Current Coupon Ginnie Mae TBA 104.5 0.0
Current Coupon Fannie Mae TBA 103.3 0.0
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.52
Markets are up this morning as initial jobless claims drop to 330k. Of course last week contained the New Year’s holiday so it is tough to read too much into this number. Alcoa kicks off fourth quarter earnings season after the bell. Bonds and MBS are up small.
There was nothing earth-shattering in the FOMC minutes which were released yesterday afternoon (the bond market basically yawned at the whole thing). Things were more or less characterized as expanding “moderately”, with a few “modests” thrown in as well. Manufacturing expanded “briskly” which was a first. The Fed did mention the issue of possible capital losses on its portfolio, and particularly how that would affect the reputation of the Fed. They talk about how spin the losses – basically telling people that you need to look at the whole picture, not just the Fed’s p/l. In other words, the Fed may end up passing losses to Treasury, which will increase the deficit, but you have to take into account the fact that this process helped the economy, which increased tax revenues. Guess dynamic scoring is permitted for the Fed but not for anyone who proposes a tax cut.
Retailers are reporting same-store sales this morning, so far it looks looks like a mixed bag with Costco and Macy’s beating estimates, while apparel retailers like Limited Brands missing.
It is official: the FHFA has delayed the increase in G-fees and the new new LLPAs. Luckily for lock desks, the FHFA will give 120 day’s notice if they decide to change things. Borrowers are probably going to save 3/8 of a point with this. The NAR is onboard with this move.

Morning Report – 73:1 leverage 1/8/14

Vital Statistics:

S&P Futures 1830.6 -0.1 -0.01%
Eurostoxx Index 3107.9 -3.1 -0.10%
Oil (WTI) 93.86 0.2 0.20%
LIBOR 0.24 -0.002 -0.70%
US Dollar Index (DXY) 81.04 0.203 0.25%
10 Year Govt Bond Yield 2.99% 0.05%
Current Coupon Ginnie Mae TBA 104.4 -0.2
Current Coupon Fannie Mae TBA 103.3 -0.2
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.5
Stocks are flattish after the ADP Employment change came in better than expected at 238k jobs. The Street was at 200k and the estimate for Friday’s number is 195k. Bonds clearly didn’t like the number, with the 10 year yield around 2.99%.
Mortgage applications rose 2.6%  last week, although the holiday makes any sort of week-over-week comparison difficult. Later on today we will get consumer credit and the minutes of the FOMC meeting.
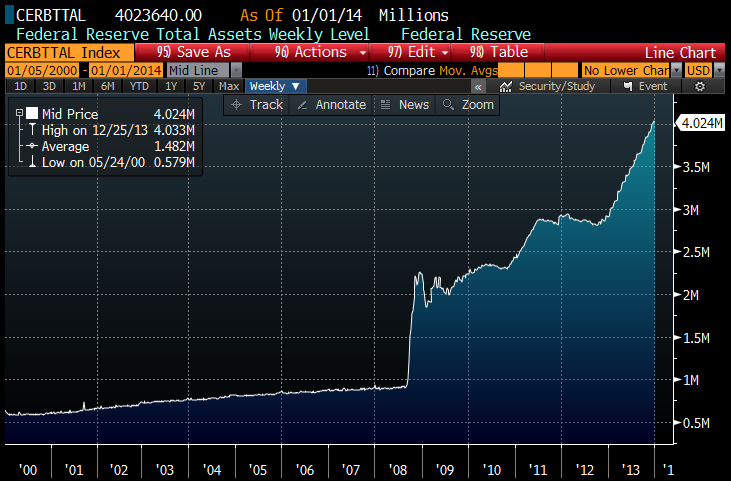
When I discussed Janet Yellen’s new role at the Fed and also showed a chart of the Fed’s balance sheet, I forgot to mention the other important side of things – the equity. Turns out the Fed announces these things weekly. And right now, we have a $4.02 trillion balance sheet supported by $55 billion in equity. For those keeping score at home, that works out to be 73:1 leverage, or about 2.6 times the leverage that blew up Long Term Capital Management. The Fed is long duration and levered 73:1 in a rising interest rate environment. And they are still building up the balance sheet, just at a slower pace than before. Everyone hopes Janet can stick the landing, but this is no sure bet.

56 out of 350 metro areas returned to or exceeded their last normal levels of economic and housing activity, according the the NAHB. More than 35% of all the markets are withing 90% of previous norms. Where does your MSA stack up? Find out here.
State of the unemployment extension: Yesterday, the Senate had a test vote that passed a 3 month extended unemployment benefits extension, however several of the Republicans who said “yea” would vote “nay” if there weren’t paid for. Of course we have the House which would probably extend benefits if they are paid for with spending cuts.

Morning Report – Welcome Janet and Mel

Vital Statistics:


S&P Futures  1827.6 6.9 0.38%
Eurostoxx Index 3094.6 25.4 0.83%
Oil (WTI) 93.82 0.4 0.42%
LIBOR 0.242 0.003 1.15%
US Dollar Index (DXY) 80.7 0.051 0.06%
10 Year Govt Bond Yield 2.95% -0.01%  
Current Coupon Ginnie Mae TBA 104.3 0.0
Current Coupon Fannie Mae TBA 103.3 -0.5
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.53

Markets are higher this morning on no real news. The trade gap narrowed on lower oil imports. Bonds and MBS are up small.

3 days to QM…

Janet Yellen was sworn in as the next Federal Reserve Chairman. She will officially take office Feb 1, and is tasked with slowly extricating the Fed’s footprint from the economy and bringing its balance sheet back to historical normal levels. Note that the vote was actually closer than the Bernank’s (56-26) reflecting the political polarization happening in Washington and the Fed.

Mel Watt was sworn in as FHFA Director yesterday. In a statement issued by FHFA Watt said, “I am honored to serve as Director of the Federal Housing Finance Agency. Today’s housing finance system is one of the keys to our economic recovery and I am grateful for the opportunity to help develop a strong foundation for moving this system forward for the benefit of all Americans at this critical point in our nation’s history.” You can read the “for the benefit of all Americans” to mean that he is going to target lower income lending. Mel is a CRA guy to the bone.

The fight over unemployment extension seems to boil down over whether to pay for it or not. Democrats are against setting the precedent that extended unemployment benefits be “paid for” and are at the point where they believe no more non-defense spending can be cut. Republicans are coalescing around the “extend benefits, but find some other spending to cut” position.

Morning Report – Mel the “enigma?” 1/6/14

Vital Statistics:

S&P Futures 1831.2 5.7 0.31%
Eurostoxx Index 3080.1 5.7 0.19%
Oil (WTI) 94.1 0.1 0.15%
LIBOR 0.239 -0.001 -0.21%
US Dollar Index (DXY) 80.87 0.083 0.10%
10 Year Govt Bond Yield 2.98% -0.02%
Current Coupon Ginnie Mae TBA 104.1 0.1
Current Coupon Fannie Mae TBA 103.1 0.1
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.55
Markets are higher this morning on no real news. Bonds and MBS are up small.
This week will have a couple big items – the FOMC minutes and the jobs report. The big question with the minutes will concern whether tapering is in fact on autopilot. Ben Bernanke indicated in the press conference that it more or less is on autopilot, but we will want to read the minutes to get some more clarity. Given that the mystery over whether the Fed will begin tapering is over, the jobs report will probably not have that much of an impact, unless it is extraordinarily strong. Finally, Janet Yellen will be confirmed this week, which should be a nonevent.
This week also kicks off earnings season, with Alcoa reporting after the bell on Thursday. Given the huge run-up we have seen in the stock market, companies better deliver. FWIW, perma-bull Jim Paulsen is cautious going into 2014.
Bloomberg has a piece on the enigma that is Mel Watt. The only thing we know for sure is that he has suspended the g-fee increases and the LLPAs for the moment. Since he has yet to be officially sworn in, he is playing things close to the vest. I don’t know why people would call him an “enigma.” Mel couldn’t even bring himself to come out against the eminent domain policies that some localities are pursuing. That says it all, IMO. At the end of the day, Mel Watt is a liberal CRA guy. All you need to know about how he will conduct policy is to see him through that lens. He wants credit to be easier for low-income borrowers. He likes government involvement in the mortgage market. Whether that means Fannie and Freddie continue in their current form or not is an open question. But at the end of the day, he is going to err on the side of more government involvement, not less. Whether that makes the Fannie Mae prefs a buy is another question.

Saturday Open Thread–Polar Vortex Edition

It’s set to be a cold, cold weekend as the NFL playoffs begin.  One news story had it thusly:

This “polar vortex,” as one meteorologist calls it, is caused by a counterclockwise-rotating pool of cold, dense air. The frigid air, piled up at the North Pole, will be pushed down to the U.S., funneling it as far south as the Gulf Coast.

Ryan Maue, of Tallahassee, Fla., a meteorologist for Weather Bell, said temperature records will likely be broken during the short yet forceful deep freeze that will begin in many places on Sunday and extend into early next week. That’s thanks to a perfect combination of the jet stream, cold surface temperatures and the polar vortex.

“All the ingredients are there for a near-record or historic cold outbreak,” he said “If you’re under 40 (years old), you’ve not seen this stuff before.”

And three of the wildcard games are being played outdoors, which will separate the men from the boys (as it were):

Philadelphia: The Eagles host the Saints with an 8:10 p.m. Eastern kickoff on Saturday, and it will be cold: The forecast calls for an overnight low of 21 degrees, with a 20 percent chance of precipitation, and wind at 5-10 mph. Those conditions should favor the Eagles, who went 4-4 at home this season, winning their final four at Lincoln Financial Field, and already proved that they can play well in bad weather when they beat the Lions at home last month, in one of the snowiest games in NFL history. The Saints have been a bad road team all season (they went 8-0 at home but just 3-5 on the road), and Drew Brees and Co. will have a tough task on their hands dealing with the elements.

Cincinnati: The Bengals host the Chargers with a 1:05 p.m. Eastern kickoff on Sunday, and although it won’t rival the Freezer Bowl when these two teams met in the playoffs 32 years ago, it will be cold: The forecast for Sunday in Cincinnati calls for a daytime high of 34 degrees and an 80 percent chance of snow. (The game will end before it turns bitterly cold and dips below zero on Sunday night in Cincinnati.) With a Southern California team coming to town, the bad weather is good news for the Bengals, who were 8-0 at home in the regular season. The Chargers, who were 4-4 on the road, may be in for an unpleasant Sunday.

Green Bay: There’s cold, and then there’s really, really cold: The Packers host the 49ers with a 3:40 p.m. Central kickoff on Sunday, and it’s going to be brutally cold. The National Weather Service has issued an advisory that warns of “An Arctic outbreak” with “near record temperatures and dangerously cold wind chills.” Temperatures at Lambeau Field could rival those of the famous 1967 Ice Bowl, when game time temperatures of 15 degrees below zero made for the coldest game in NFL history. The forecast calls for a high of 5 degrees below zero and an overnight low of 20 degrees below. The Packers, who went 4-3-1 at home this season, are more accustomed to cold temperatures than the 49ers, who went 6-2 on the road this season. But neither team is accustomed to cold like this.

I wish you all a happy and warm weekend. . . Go, Pack!

Morning Report – Disappointing vehicle sales 1/3/13

Vital Statistics:

S&P Futures 1830.5 3.9 0.21%
Eurostoxx Index 3074.7 14.8 0.48%
Oil (WTI) 95.11 -0.3 -0.35%
LIBOR 0.24 -0.003 -1.24%
US Dollar Index (DXY) 80.72 0.089 0.11%
10 Year Govt Bond Yield 3.00% 0.01%
Current Coupon Ginnie Mae TBA 103.8 -0.2
Current Coupon Fannie Mae TBA 102.9 -0.1
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.55
Markets are higher this morning on no real news. Bonds and MBS are flattish. A snowstorm in the Northeast has many traders at home, so I don’t expect a lot of movement today. The Bernank speaks at 2:30 EST. Can’t imagine he is going to steal any of Janet’s thunder, but you never know.
It is looking like December domestic vehicle sales are not coming in as strong as hoped. Many analysts attributed the disappointment to bad weather.
The ISM New York index of business conditions fell, but is still at the high end of its range. It looks like most retailers deferred releasing comp store sales to next Thursday, so that will be an important data point for the state of the consumer.

Morning Report – Hello Hercules 1/2/14

Vital Statistics:

Last Change Percent
S&P Futures 1836.4 -4.7 -0.26%
Eurostoxx Index 3086.9 -22.1 -0.71%
Oil (WTI) 97.66 -0.8 -0.77%
LIBOR 0.243 -0.003 -1.32%
US Dollar Index (DXY) 80.69 0.581 0.73%
10 Year Govt Bond Yield 3.02% -0.01%
Current Coupon Ginnie Mae TBA 104 0.1
Current Coupon Fannie Mae TBA 103.1 0.1
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.55
Markets are down to kick off the new year. Bonds and MBS are down. Initial Jobless Claims came in at 339k, a little lower than expected. We are scheduled to get hit with a big snowstorm this afternoon in the Northeast, so I would imagine bonds are going to become a little more illiquid this afternoon.
Some more bullish economic data – the Dec ISM manufacturing index came in a little better than expected at 57, and construction spending increased 1% month-over-month, topping expectations.
The buy-and-rent business is getting tougher. Part of the reason why the origination business has been so tough is that the most aggressive buyers these days are cash institutional buyers. Depending on who you ask, cash buyers are anywhere from 40% to 50% of buyers these days. Historically they have been closer to 20%. So even if existing home sales stay the same, the number of homes with mortgages on them could increase 45% or so if we went back to normal cash / mortgage percentages.