Morning Report – The Rent vs Buy decision revisited 4/23/14

Vital Statistics:

Last Change Percent
S&P Futures 1872.0 -1.9 -0.10%
Eurostoxx Index 3191.5 -8.2 -0.26%
Oil (WTI) 101.6 -0.2 -0.19%
LIBOR 0.229 0.000 0.07%
US Dollar Index (DXY) 79.76 -0.150 -0.19%
10 Year Govt Bond Yield 2.70% -0.01%
Current Coupon Ginnie Mae TBA 105.2 0.1
Current Coupon Fannie Mae TBA 104.2 0.1
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.28


Markets are lower this morning as earnings reports continue to pile in. So far, it is looking like most companies are meeting or beating estimates. Bonds and MBS are up.
The Markit US Manufacturing PMI slipped in April. It seems like big revisions have been the order of the day lately, so I wouldn’t fall out of my chair with shock if that preliminary number was revised upward. Like I said before, this could be the year that “recovery summer” stops being a running joke.
That said, new home sales came in at 384k, well below the last month’s 450k pace. Abysmal, abysmal number. The XHB (homebuilder ETF) is getting slammed right now. You can’t blame this one on the weather. Maybe the builders, who have been increasing home size and prices, have finally hit the point where the consumer is saying “uncle.” Shortages of buildable lots and skilled labor continue to be an issue.
Mortgage applications fell 3.3% last week (unsurprising as it was a short week). Both purchases and refis fell. Refi percent fell to 51.3%, and we are seeing ARMs increase – up to 8.5% of all loans.
Hatteras (a mortgage REIT that specializes in ARMs) reported that its leverage ratio increased. ARMs have always been on the illiquid side to begin with, but it looks like they increased their dollar roll position, which put even more pressure on front month TBAs. TBAs (To-Be-Announced) are generic mortgage backed securities, and their price in the market is the starting point of a rate sheet. So if TBAs are in demand, mortgage rates are falling, and if they are out of favor, mortgage rates are rising. In this case, Hatteras has been selling the front-month TBAs and buying the out-month TBAs. So this puts pressure on the front month TBA, which means ARM rates are slightly higher than they otherwise would be. Of course this trade has to be reversed at some point, so ARM pricing could get a bit better in the future. I realize this is kind of “inside baseball”, but it is always good to keep in mind how the buyers of mortgage backed securities (the ultimate lenders here) are positioned.
In the “what passes for analysis” category these days category, the Washington Post (yes that bastion of commercial logic) opines that owning a house is a lousy investment. The author talks about how stocks are so much better over the long term (conveniently, the S&P 500 is at all-time highs, and real estate has gotten pounded over the past six years), and concludes that owning your own home is a stupid investment and you are better off renting. This is a classic case of “in the sciences, knowledge is cumulative, and in the financial markets it is cyclical.” The author (who may be too young to remember) must imagine that inflation is forever vanquished, never to return again. If inflation ever comes back, stocks will get clobbered (as they did from 1965-1982 – the last secular bear market) as will bonds. But your house will go up in value with inflation, and the value of your liability (a 4% 30 year fixed mortgage) will fall. Inflation is a debtor’s best friend, and the Fed is pulling out all the stops trying to create it. At some point, it will succeed. And if you rent, you get to enjoy annual rent increases. If you bought, you have locked in your monthly payment for 30 years.

Morning Report – Existing Home Sales still weak 4/22/14

Vital Statistics:

Last Change Percent
S&P Futures 1867.5 3.1 0.17%
Eurostoxx Index 3192.4 36.6 1.16%
Oil (WTI) 102.9 -1.5 -1.45%
LIBOR 0.229 0.003 1.22%
US Dollar Index (DXY) 79.83 -0.113 -0.14%
10 Year Govt Bond Yield 2.74% 0.02%
Current Coupon Ginnie Mae TBA 105.2 0.0
Current Coupon Fannie Mae TBA 104 -0.1
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.27


Markets are higher this morning on a blizzard of earnings reports and a couple major M&A transactions in the pharma space. Bonds and MBS are down.
The FHFA Home Price Index rose .6% month over month in February and is up just shy of 7% for the year. The FHFA Index only looks at homes with a conforming mortgage, so it is more of a central tendency index than, say Case Shiller.
Existing Home Sales were basically flat in March, coming in at 4.6 million. The median home price was up 7.4% year over year. Days on Market fell to 55 days from 62. First time homebuyers increased to 30% of transactions and all cash deals increased to 33%. For LOs that are discouraged by the death of the refi business, there is a bright side to these numbers. Investors are becoming less of a force in the market and the first time homebuyer is becoming more of one. Historically, existing home sales have been in the 5.2 million range. If we get back to historical run rates and all cash buyers go back to their historical levels of 20%, that means the gettable purchase business will increase 35%. (5.2 million * 80% with a mortgage) = 4.16 million gettable loans. Current situation: 4.6 million * 67% = 3.08 million.
Chart:  Existing Home Sales:

Image

Morning Report – NVR disappoints 04/21/14

Vital Statistics:

Last Change Percent
S&P Futures 1862.5 4.6 0.25%
Eurostoxx Index 3155.8 16.6 0.53%
Oil (WTI) 104.4 0.0 0.05%
LIBOR 0.226 -0.002 -0.88%
US Dollar Index (DXY) 79.89 0.042 0.05%
10 Year Govt Bond Yield 2.70% -0.02%
Current Coupon Ginnie Mae TBA 105 -0.6
Current Coupon Fannie Mae TBA 104.1 0.2
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.36


Markets are higher this morning on no real news. Bonds and MBS are up.
The Chicago Fed National Activity Index came in at .2, in line with expectations. The Index of Leading Economic Indicators rebounded to .8. Perhaps this year will be the end of the “recovery summer” running joke.
Thursday’s big increase in rates were a bit of a head-scratcher, given that there were no big economic reports on Thursday. Chalk it up to low liquidity in the markets as senior traders took the day off and instructed their junior traders to stay out of the way.
Lots of earnings this week, with some of the market heavyweights reporting. On Thursday, we will hear from homebuilders D.R. Horton and PulteGroup. Hopefully they will give some insight on how the spring selling season is shaping up.
Washington-DC based homebuilder NVR reported lower than expected earnings, partially based on a reversal of some previously recognized tax deductions.  Orders fell 5%, while backlog was down 3% on a unit basis but up 4% on a dollar basis. Gross margins increased to 18% as average selling prices rose 5%. NVR doesn’t do conference calls, so we’ll have to wait until Thursday to get some more color on the market environment. The stock is down 6.5%.
Ocwen is putting all future mortgage servicing deals on hold, after attracting the scrutiny of the New York Attorney General’s office. Everything is on hold until people figure out what Schneiderman wants.

Good Friday Post

Fresh thread since Brent’s taking *another* day off.

Jeez, banker’s hours.

Morning Report – Recovery Summer on the horizon? 4/17/14

Vital Statistics:

Last Change Percent
S&P Futures 1856.0 3.2 0.17%
Eurostoxx Index 3149.1 9.9 0.31%
Oil (WTI) 103.9 0.2 0.16%
LIBOR 0.226 -0.002 -0.88%
US Dollar Index (DXY) 79.7 -0.104 -0.13%
10 Year Govt Bond Yield 2.66% 0.03%
Current Coupon Ginnie Mae TBA 105.7 -0.2
Current Coupon Fannie Mae TBA 104.3 -0.1
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.41


Markets are higher this morning as earnings continue to come in and for the most part the look good. GE and Goldman reported better than expected earnings this morning, although Google disappointed last night. So far (and it is very early) it looks like the market’s fears of a bad earnings season look unfounded. I think the biggest worry was going to be the banks, and so far, so good.
Markets will be closed tomorrow, and bonds close early today.
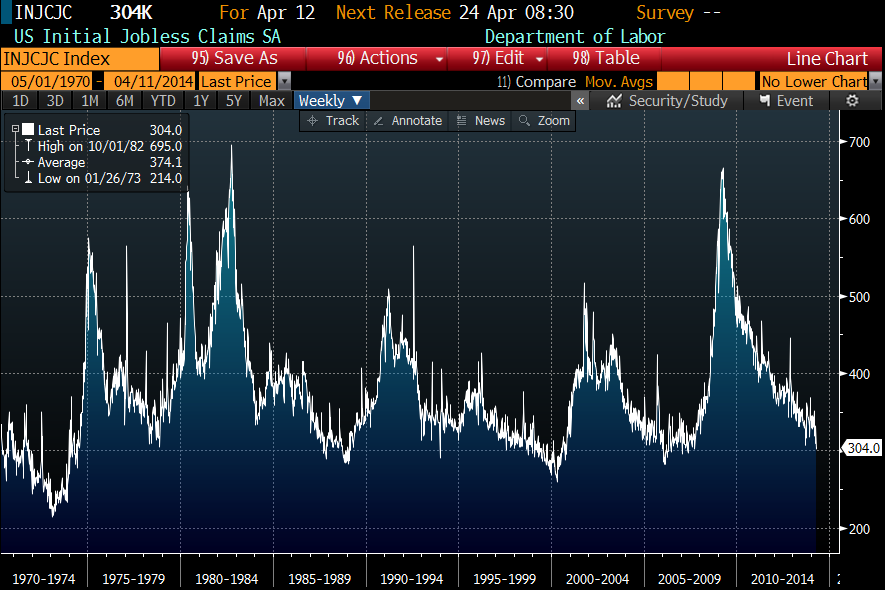
Initial Jobless Claims came in at 304k, which is a strong number historically. What is “normalcy” in initial jobless claims? Going back to 1970, it is about 375k. Here is a chart of initial jobless claims going back to 1970, so you can get some historical perspective:

Image

The Fed released the Beige Book yesterday. Overall, it shows activity increasing since last month, which isn’t surprising – the big question is whether it is a rebound from weather-related weakness or something sustainable. Certainly some of the manufacturing data we saw recently (industrial production, capacity utilization) seems to imply the latter. I think people don’t appreciate the industrial production reports that came out yesterday – the headline numbers for March were great on their own, but the upward revisions to February numbers were huge.

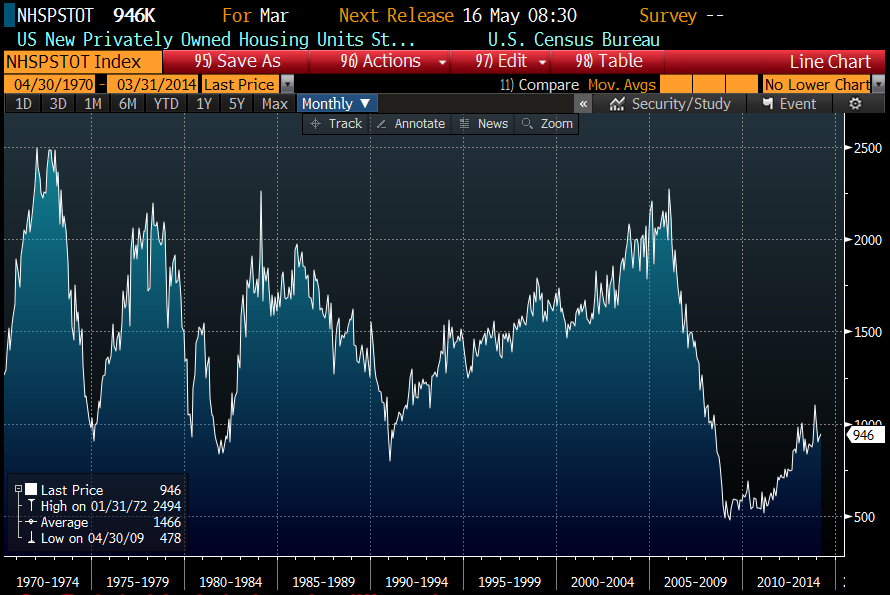
On the labor front, wage pressures remained contained, except for the Dallas district. Most districts are reporting labor shortages in skilled labor. On the negative side, food prices are rising, and rising food prices plus stagnant wages can be an economic damper. The main takeaway is that the economy seems to be accelerating and it is looking like it is more than just a rebound from weather-related weakness. That said, the weakness in housing starts continues to be a head-scratcher. We are still at levels that represent the bottoms of previous recessions. Any excesses of the bubble were corrected long ago.

Image

I suspect that a sudden increase in household formation is going to catch the builders absolutely flat-footed. Once the job market improves for young college grads, there is going to be a stampede for starter homes.
Yet one more data point that things are improving: banks are increasing their business lending. The big banks reported an 8.3% increase in commercial loans outstanding compared to a year ago. This is part of the reason why the bank earnings are not as bad as feared – business lending is replacing lost mortgage banking income. This portends an expansion in capacity, and almost by definition, hiring.
Recovery summer may finally come this year. Kind of messes with the whole “sell in May and go away” theory, doesn’t it?

Morning Report – Housing Starts disappoint

Vital Statistics:


  Last Change Percent
S&P Futures  1847.7 8.1 0.44%
Eurostoxx Index 3126.3 34.8 1.13%
Oil (WTI) 104.6 0.8 0.82%
LIBOR 0.228 0.002 0.66%
US Dollar Index (DXY) 79.7 -0.104 -0.13%
10 Year Govt Bond Yield 2.64% 0.01%  
Current Coupon Ginnie Mae TBA 105.7 -0.1  
Current Coupon Fannie Mae TBA 104.4 0.0  
RPX Composite Real Estate Index 200.7 -0.2  
BankRate 30 Year Fixed Rate Mortgage 4.26    


Markets are higher this morning as earnings are coming in better than expected. Bonds and MBS are down small.
 
Mortgage Applications rose 4.3% last week, the first increase in a month. Both purchases and refis rose.
 
Industrial Production rose .7% in March, and capacity utilization rose to 79.2%, the highest since mid-2008.
 
Housing starts came in at a 946k pace in March, lower than the 970k street estimate. Building Permits were 990k, again south of expectations. Single family starts were up half a percent, while the volatile multi-fam segment fell 6.4%. Activity rebounded in the Northeast, but the South and West were down. 
 
Speaking of the builders, according to the NAHB, homebuilder sentiment improved slightly in April from a downward-revised March reading. So far, it is looking like the Spring selling season is going to be nothing special, as ongoing tight credit conditions and capacity constraints keep a lid on optimism. 
 
Believe it or not, some places in the country are finding they have to raise wages in order to attract talent. Mark Zandi, chief economist at Moody’s says there are spot labor shortages that will probably broaden out over the next year as the job market steadily improves. 

Morning Report – A tale of two housing markets TAX DAY ’14

Last Change Percent
S&P Futures 1827.8 3.3 0.18%
Eurostoxx Index 3128.9 -2.7 -0.09%
Oil (WTI) 103.3 -0.8 -0.72%
LIBOR 0.226 -0.002 -1.01%
US Dollar Index (DXY) 79.84 0.113 0.14%
10 Year Govt Bond Yield 2.65% 0.00%
Current Coupon Ginnie Mae TBA 105.6 -0.1
Current Coupon Fannie Mae TBA 104.4 0.0
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.3


Markets are up small on no real news. Bonds and MBS are flat
Inflation at the consumer level remains well-behaved, increasing at .2% month-over-month in March. On an annual basis, they rose 1.5%.
The latest CoreLogic Market Pulse is out, and it has some good stuff in it. One of the things we have noted before is that there really is a tale of two markets – the high end, which is doing great, and the low end which is not. If you listen to the builders, you will see that average selling prices for new homes have been increasing at a mid-teens rate. This is not apples-to-apples appreciation, it is that the growth is in the larger segments. Apparently the average square footage of a new home has increased 200 square feet since 2008.
The first time homebuyer has had a most difficult time, graduating college with a mountain of student loan debt and dismal job prospects. That may be changing, however as Barclay’s has pointed out. College graduates are beginning to have a little more success on the jobs front, and this should usher in the return of the first time homebuyer, who really has been dormant since the bubble burst six years ago.
Mortgage lending is hitting a 17 year low, as rates increase. According to the MBA, here are the dynamics at work: Mortgage rates jumped in mid-2013 as the Fed signalled tapering was at an end. This pushed up cash purchases to 40%, which helped fuel price increases, but also squeezed more Americans out of the market. This is the foundation for lower lending for the rest of the year.

Morning Report – The week ahead 4/14/14

Vital Statistics:

Last Change Percent
S&P Futures 1822.0 10.3 0.57%
Eurostoxx Index 3128.3 11.8 0.38%
Oil (WTI) 103.7 0.0 -0.01%
LIBOR 0.229 0.002 0.97%
US Dollar Index (DXY) 79.82 0.365 0.46%
10 Year Govt Bond Yield 2.65% 0.02%
Current Coupon Ginnie Mae TBA 105.8 -0.1
Current Coupon Fannie Mae TBA 104.5 -0.1
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.24


SPUS are higher this morning after Thursday and Friday’s bloodbath. Bonds and MBS are down small.
Retail Sales came in better than expected, and the previous month was revised upward by a pretty large amount. March sales came in at +1.1% (vs .9 expected) and February was revised upward from .3% to .7%.
We have a short week coming up with markets closed on Friday. In terms of economic data, the big day will be Wednesday, when we get housing starts and building permits as well as industrial production and capacity utilization. After that, expect a lot of position-squaring ahead of the 3 day weekend.
Earnings season really begins this week, with a lot of heavyweights reporting. This morning we got Citi, and later this week we will hear from Bank of America, Google, General Electric, and Goldman.
Ever since Mel Watt took of FHFA, he has been pretty silent about what he is looking for, and how he wants to treat the GSEs going forward. At the end of the day, Watt is an affordable housing CRA guy to the bone and won’t do anything that jeopardizes that.

Morning Report – dismal mortgage banking stats 4/11/14

Vital Statistics:


  Last Change Percent
S&P Futures  1818.9 -8.2 -0.45%
Eurostoxx Index 3106.2 -46.7 -1.48%
Oil (WTI) 103.4 0.0 0.03%
LIBOR 0.226 -0.001 -0.26%
US Dollar Index (DXY) 79.52 0.140 0.18%
10 Year Govt Bond Yield 2.61% -0.04%  
Current Coupon Ginnie Mae TBA 106 0.1  
Current Coupon Fannie Mae TBA 104.7 0.2  
RPX Composite Real Estate Index 200.7 -0.2  
BankRate 30 Year Fixed Rate Mortgage 4.26    


Markets are lower again this morning after the market sold off heavily yesterday. Bonds and MBS are up. 
 
The producer price index came in at .5%, showing inflation remains tame.
 
LOs, if you have anyone on the fence about locking or who wanted to do a loan but was balking at the rate, give them a call. A 2.61% 10 year yield isn’t going to last long.
 
JP Morgan missed earnings estimates last night, and the only way to describe the mortgage arm is dismal. Mortgage Origination volumes were down 68% from the prior year and 27% from the prior quarter. The business lost $58 million on a pre-tax basis. J.P. Morgan is forecasting a pretax loss of about $100MM – $150MM in the second quarter, and a pre-tax loss for the entire year. The stock is down a couple of bucks (about 3.5%) pre-open
 
Well Fargo, on the other hand beat earnings estimates, however the stock is flat pre-open. Wells originated $36 billion in Q1, down from $50 billion in Q4 and $140 billion a year ago. Gain on sale margins fell to 1.61% from 1.77% last quarter and 2.56% a year ago. 

Morning Report: FOMC minutes soothe the markets 4/10/14

Vital Statistics:


Last Change Percent
S&P Futures 1863.6 -1.2 -0.06%
Eurostoxx Index 3168.4 -14.4 -0.45%
Oil (WTI) 103.3 -0.3 -0.33%
LIBOR 0.227 -0.001 -0.22%
US Dollar Index (DXY) 79.52 0.036 0.05%
10 Year Govt Bond Yield 2.67% -0.02%
Current Coupon Ginnie Mae TBA 105.8 0.1
Current Coupon Fannie Mae TBA 104.4 0.1
RPX Composite Real Estate Index 200.7 -0.2
BankRate 30 Year Fixed Rate Mortgage 4.44


Markets are flattish after initial jobless claims came in lower than expected and import prices rose. Bonds and MBS are up small.
Stocks and bonds took off on the release of the FOMC minutes yesterday. The Fed considered a more explicit commitment to keep rates low until inflation reaches their target. This additional hurdle for raising rates cheered the markets and stocks went out on their highs. “A few” members (probably Plosser) thought the Fed Funds rate should increase soon, but the rest of the Committee disagreed, saying that the evidence the hawks cited was inappropriate to focus on at the zero bound. The takeaway is that the forecast of a June 2015 rate hike is looking more and more like an outlier and if inflation stays below the target rate of 2%, the Fed may consider holding rates at zero until inflation its 2%. Which, if China indeed hits the wall and its real estate bubble bursts, could be a long time. Start thinking about where the next bubble is going to be.
Remember Greece? The fiscal ne’er-do-well of Europe that got cut off from the bond market? Well, guess what? They just raised 4 billion euros of 5 year paper, with a bid to cover ratio of 5:1. The rate they paid? 4.75%. People have such short memories….. Or it is just the fact that since rates are so low, people have to reach for yield. Either way, once rates start going up, it is going to be a bumpy ride, IMO.
One other point about Greece – they did clean up its public spending issues a bit and trimmed its debt (the dreaded austerity that liberal economists love to hate). That is the difference between not being able to finance your government at all and being able to borrow at under 5%. Note to Paul Krugman. The bond market always gets the last word. Always.
Unintended consequence of Dodd-Frank? Turning non-judicial states into judicial ones anyway. Lenders are choosing to go through the court process, even if it takes more time, in order to reduce the potential liability under the new foreclosure laws (especially in states like California).
The CFPB is holding a forum on the mortgage closing process on April 23. It will be livestreamed on their site. Find out what sins we are apparently committing in the closing process.