Morning Report – More Zillow / Trulia 7/29

Markets are higher this morning as earnings reports continue to come in. Bonds and MBS are up as well.

Consumer Confidence improved dramatically in June, according to the Conference Board. The present situation index rose from 86.3 to 88.3, but the expectations index rose from 86.4 to 92.7. In other words, the increase is being driven more by expectations of the future, which may or may not come to pass. Consumer confidence is back to October 2007 levels, where the first indications of the financial crisis were beginning to be felt. This was the beginning of the buyer’s strike where the big buyers of structured product were saying no mas and banks were beginning to lug paper they couldn’t move.

The S&P Case-Shiller index dropped 31 basis points in month-over-month in May, but is still up 9.34% on an annual basis. This is the seasonally-adjusted number. The non-seasonally adjusted number rose 1.1%. This is the first month-over-month drop since real estate bottomed in early 2012. Prices are back to summer 2004 levels. San Francisco, Tampa, and Chicago led the way with price appreciation.

case-shiller20

Mortgage REIT giant American Capital Agency reported good second quarter numbers. They reduced their leverage by shrinking their balance sheet, which is a bearish signal on MBS. Of course everyone knows rates are going up, but you don’t want to lighten your exposure until it is imminent. Interestingly, they cite the favorable supply / demand relationship with MBS, which seems to be unaffected by the Fed’s tapering. This speaks to how lousy origination volumes have been this year.

Will the Zillow / Trulia merger do to real estate brokers what Expedia did to travel agents? That is the fear of many, although Zillow adamantly denies that is where it is going. “We sell ads, not houses.” said Spencer Rascoff, CEO of Zillow. That may be true, but given the sheer size of broker commissions, it is probably inevitable that technology will cut in on their business model. Still, this is a merger of #1 and #2 and it could get blocked on antitrust grounds. If the NAR pushes the regulators to block the deal, it might be curtains. FWIW, the risk arbitrage community thinks this one is a long shot, with the arbitrage spread trading at 9.25% gross. This is very, very wide. On a back of the envelope basis, it looks like arbs are giving this one a 1 in 3 chance of blowing up.

Educational Exception to Copyright: from Volokh

Fourth Circuit strikes down

Virginia ban on same-sex

marriage

July 28 at 2:57 PM
In a 2-1 decision in Bostic v. Schaefer, a panel of the Fourth Circuit has invalidated Virginia’s ban on same-sex marriage. The majority opinion was written by Judge Henry Floyd (an Obama nominee, but previously a George W. Bush choice for the district court) and joined by Judge Roger Gregory (Clinton nominee). It’s the second post-Windsor appellate court, after the Tenth Circuit, to strike down an exclusion of gay couples from marriage. Judge Paul Niemeyer (George H.W. Bush) dissented, the second appellate court judge to do so since Windsor. The case was argued by Ted Olson, who recently co-authored a book with David Boies about their challenge to Proposition 8.

The Fourth Circuit majority held that the ban violated gay couples’ fundamental right to marry. Specifically, the majority placed heavy reliance on both Windsor and Lawrence v. Texas as establishing the equal validity of gay couples’ intimate and relational choices:

Lawrence and Windsor indicate that the choices that individuals make in the context of same-sex relationships enjoy the same constitutional protection as the choices accompanying opposite-sex relationships. We therefore have no reason to suspect that the Supreme Court would accord the choice to marry someone of the same sex any less respect than the choice to marry an opposite-sex individual who is of different race, owes child support, or is imprisoned. Accordingly, we decline the Proponents’ invitation to characterize the right at issue in this case as the right to same-sex marriage rather than simply the right to marry.

In what has become fairly common, the panel closed its decision with broad thoughts on the underlying issue of same-sex marriage. But this time the court explicitly used the word “segregation” to describe the exclusion of same-sex couples from marriage:

We recognize that same-sex marriage makes some people deeply uncomfortable. However, inertia and apprehension are not legitimate bases for denying same-sex couples due process and equal protection of the laws. Civil marriage is one of the cornerstones of our way of life. It allows individuals to celebrate and publicly declare their intentions to form lifelong partnerships, which provide unparalleled intimacy, companionship, emotional support, and security. The choice of whether and whom to marry is an intensely personal decision that alters the course of an individual’s life. Denying same-sex couples this choice prohibits them from participating fully in our society, which is precisely the type of segregation that the Fourteenth Amendment cannot countenance.

The idea that laws limiting marriage to opposite-sex couples are a form of segregation is historically loaded, especially for a court sitting in the heart of the old Confederacy. Analogies to the black civil rights movement, and in this context specifically to anti-miscegenation laws and second-class status, have become a staple of gay-rights political and legal arguments. Rarely have they gained quite this explicit an endorsement from a prominent court.

The dissenting opinion is a foretaste of the response to the fundamental-rights argument that we will likely hear in the Supreme Court from (at least) four Justices. It proclaims neutrality on the policy question but leans on judicial restraint in the definition of fundamental rights:

This analysis is fundamentally flawed because it fails to take into account that the “marriage” that has long been recognized by the Supreme Court as a fundamental right is distinct from the newly proposed relationship of a “same-sex marriage.” And this failure is even more pronounced by the majority’s acknowledgment that same-sex marriage is a new notion that has not been recognized “for most of our country’s history.” [citation omitted] Moreover, the majority fails to explain how this new notion became incorporated into the traditional definition of marriage except by linguistic manipulation. Thus, the majority never asks the question necessary to finding a fundamental right — whether same-sex marriage is a right that is “deeply rooted in this Nation’s history and tradition” and “implicit in the concept of ordered liberty, such that neither liberty nor justice would exist if [it was] sacrificed.” [citations omitted]

We don’t know yet whether Virginia will seek review by the entire appeals court before seeking review in the Supreme Court, which would slow down the process. The 10th Circuit case seems to be on a fast track, with state officials eschewing en banc review. It’s likely that more circuit courts will speak to this issue in the coming months, including possible opinions from the 5th and 6th Circuits.

UPDATE: North Carolina’s attorney general, Democrat Roy Cooper, has announced his office will no longer defend the state’s prohibition on gay marriage: “Since the US Supreme Court ruled in the Windsor case, all the federal courts have rejected these arguments each and every time. So it’s time for the State of North Carolina to stop making them.” (HT: Chris Geidner)

Dale Carpenter is the Distinguished University Teaching Professor and Earl R. Larson Professor of Civil Rights & Civil Liberties Law at the University of Minnesota Law School. He teaches and writes in the areas of constitutional law; the freedoms of speech, association, and religion; and sexual orientation and the law.

Bites & Pieces: The Goose Got Loose (Mexican Birria)

Hi all,

The Goose got loose on Friday and came down here for dinner. I decided to ask her for her favorite protein (beef or lamb), starch (rice), and veg (tomato or cuke this time of year). The selections seemed to cry out for a curry. Rogan Josh with basmati rice, a masala tomato salad and a nice raita would do the trick. Then I got to researching an upcoming trip to San Diego. I had this great dish and watned to try it again, but couldn’t remember what it was called. I wound up using Urban spoon and searching on Mexican restaurants in Chula Vista. Bingo! I saw a place called Birrieria Don Rafa, checked out its address and knew I had found it.

What is Birria? It’s a stew (thank you, Hank Azaria). It’s related to molé in that one makes a paste from rehydrated chiles. Instead of ladling a bit of molé sauce onto the meat, one braises the meat in the sauce until it breaks down. Beef, goat or lamb are all traditional. So I shifted the menu to south of the border. Cook some black beans, some nice yellow rice, and prepare a cucumber/tomato salsa. And, of course, birria.

So, now that I knew what I wanted to make, the question was how to do it. After looking through various recipes, I combined a couple. There’s a cooking and life blog called the Almost Fearless Kitchen. I liked her method and explanation. I also checked out recipes from a favorite source, Pati Jinich. She used to have a show on WETA called Pati’s Mexican kitchen. Turns out that she doesn’t have a recipe for birria, but her barbacoa recipe appealed to me. So, I combined aspects of the two recipes. I promised Goose to get her my “recipe” (hah!), so I thought I’d post it here as well. I want to make this again, so writing it down is useful to me as well.

Both recipes had aspects that I liked. Almost Fearless had a nice explanation for using several different peppers. Building layers of flavor and all that. I liked the additional liquid in Pati’s approach and didn’t feel a need to strain the paste. Just add additional liquid and let it all rock. I wound up over-salting the dish a bit, but the Goose likes her salt. As I couldn’t take the day off, I got up early to prep the sauce, brown the meat and toss everything in the slow cooker.

http://kitchen.almostfearless.com/birria-the-mexican-stew-that-cures-anything/

http://www.patismexicantable.com/2012/02/lamb_barbacoa_in_adobo/

Almost Patti’s Birria

Ingredients

Carne: 4 pounds of meat (see notes)
Chiles: 6 guajillo chiles, 6 ancho or mulato chiles, 12 cascabel chiles (see notes)

Spice blend:
1 teaspoon oregano
1 teaspoon pepper
1/4 teaspoon cloves
1/4 teaspoon cumin
1/4 teaspoon cinnamon
1/2 teaspoon thyme
1/2 teaspoon ground all spice
1 teaspoon salt

Paste additions:
1/4 cup cider vinegar
1/2 cup chopped onion
1 medium tomato, cut into quarters (or eighths if you’re ambitious)
10 garlic cloves

3 bay leaves
1 onion
Salt to taste (I used 4 tbsp of coarse sea salt)

Notes:

I used two pounds of bone in lamb shanks and two pounds of goats meat. Both are traditional in birria, though I doubt using both is. A good chuck roast would work pretty well too. You’ll want an inexpensive cut that breaks down while braising.

I couldn’t find cascabel chiles at the local market (Global Foods, which finally came in to replace a departed Giant). So, I picked up some mulatos and pasillos. Something I like about this dish is that you can adjust the heat level pretty easily by changing your selection of chiles. Just be sure to use a combination.

Method

1. Toast the chiles

Remove the seeds from the chiles (you’ll want gloves for this if you want to touch anything sensitive later in the day) and toast them in a pan. I tossed them into the toaster oven at 350 for about 10 minutes.

2. Rehydrate the chiles

Add 2 cups of boiling water to the chiles and let sit for 20 minutes. Pati called for adding 5 cups of water to the toasted chiles and putting on a burner for 15 minutes. 2 cups of this water are used to make the paste. Fearless called for adding a cup of boiling water to the chiles. I liked the simplicity of adding boiling water to the chiles and have a nice electric kettle. I was going for more liquid and liked Fearless’s approach, so I just added 2 cups of boiling water to the chiles to rehydrate them.

3. Make the paste

Throw the chiles and their water along with the spices into a blender. I used some whole spices, so ground everything up in a retired coffee grinder. Add the vinegar, onion, tomato, and garlic gloves. Blend everything until you get a smooth puree.

4. Brown the meat.

Oven braise method: Pre-heat the oven to 350 F. Put a heavy bottomed pot or dtuch oven over medium heat. Meanwhile, cut the meat into 1” – 2” chunks. Add a tablespoon or so of oil to the pan. Once it’s shimmering (not smoking!), add the meat in a single level. You might need to do this in batches. Cook the meat until browned on several sides and remove to a bowl. Once all the meat is browned, return any meat set aside to the pot. Cover with water or low sodium stock, add the paste and bring to a light boil. Cover and put in the oven. Cook until the meat is tender and breaking down.

Slow cooker method: Put a pan suitable for browning meat (luv luv luv my cast iron pan for this) over heat. Meanwhile, cut the meat into 1” – 2” chunks. Add a tablespoon or so of oil to the pan. Once it’s shimmering (not smoking!), add the meat in a single level. You might need to do this in batches. Cook the meat until browned on several sides and put in the slow cooker. Once all the meat is browned, cover with water or low sodium stock, add the paste and put the slow cooker on high. Once the dish is up to a boil, turn the slow cooker to low and go do something useful. Come back in about 8 – 10 hours. If the meat isn’t falling off the bone tender, turn the heat back up to high and cook until ready.

Once this puppy is ready, serve over rice and have sides available. Rice, black beans, minced white onion, cilantro, salsa, and tortillas. They’re all good baby.

Morning Report – Big week coming up 7/28/14

Markets are higher this morning on overseas strength. Bonds and MBS are down.

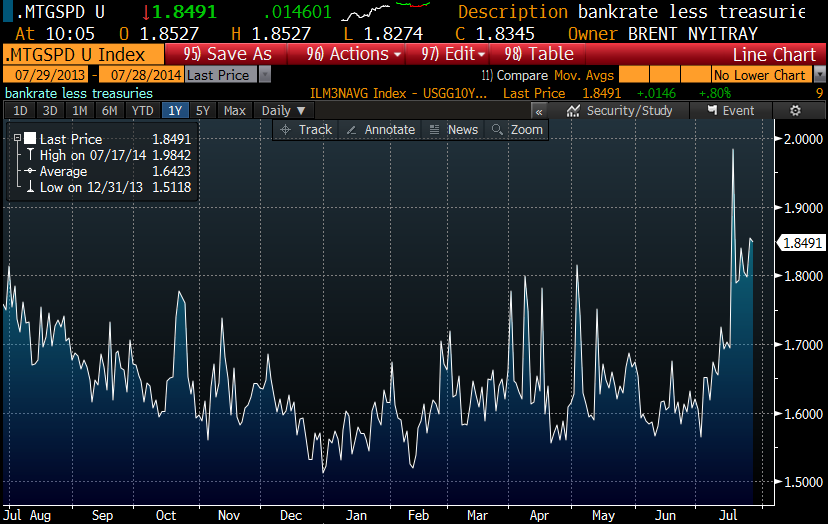
Pending Home Sales fell 1.1% month over month in June, a sign that the real estate market continues to struggle to get up off the mat in many areas of the country. Limited credit and wage growth continue to be issues. That said, mortgage rates continue to increase even in the face of a flat bond market, which could signal credit is easing. Here is a chart of the Bankrate average 30 year fixed rate mortgage minus the 10 year bond yield:

Mortgage spreads

In other economic data, the Markit Composite PMI came in at 60.9, a very strong number. The services PMI came in at 61. The Street forecast for the ISM PMI is 56 (for both services and manufacturing), so there is another possibility of an upside surprise there. The economy is getting better.

Big week coming up with economic data. On Wednesday, we will get the advance estimate for second quarter GDP and the results from the FOMC meeting. Friday is a big day – we will get the jobs report, ISM, and personal spending / personal income. This is a lot of data in one day, and markets will be thin as many desks will be half-staffed. This is a recipe for volatility. The lack of action in the bond market has bred complacency – don’t get caught napping – I wouldn’t be floating ahead of this Friday.

I don’t expect any fireworks with the FOMC meeting – there will be no economic revisions until September, and the meaningful stuff (how to conduct policy after QE, how to prep the markets for rate hikes) won’t make it into the FOMC statement. Separately, Dallas Fed Head Richard Fisher wrote an opinion piece in the Wall Street Journal pressing the Fed to not only end QE but to also start shrinking its balance sheet by not re-investing maturing bonds back into the market. Even that might not be enough. FWIW, he is skeptical of the Yellen framework for bubbles which is that “low interest rates don’t cause speculative bubbles, and we can deal with bubbles through banking regulation.” People have gotten used to the hawks being ignored. As the economy recovers, that will change.

It is official: Zillow is buying Trulia. It would be the marriage of the #1 and #2 online real estate listing sites, so it will attract antitrust scrutiny. Trulia will remain an independent brand and Zillow is following a similar strategy to Barry Diller’s IAC/Interactive corp, where competing brands co-exist as some appeal to different market segments than the other.

Guess the marching orders went out over the weekend: The Administration want to end these inversion transactions, and everyone from Jack Lew to Dr. Cowbell are singing from the same sheet of music. The message: Take away this loophole now, and then let’s focus on corporate tax reform later. It is clear what is going on: The Administration fears a Republican Senate will mean vastly different negotiations regarding corporate tax reform. Republicans are going to want to trade closing loopholes for lowering rates, so Obama wants to get a few “free” tax hikes in (which is what “closing loopholes” really means). Of course Republicans are in no mood to throw Obama a freebie and he knows it, so this is just a means to create some talking points ahead of the midterm elections.

Check out our iServe app for iPhone and Android.

Morning Report – The Left continues to push Mel Watt to do principal mods 7/25/14

Stocks are lower this morning on no real news. Bonds and MBS are up.

Durable Goods orders rose .7% in June, topping expectations. Capital Goods ex air / defense rose 1.4%, although May was revised downward in a big way.

The left continues to push Mel Watt to do principal mods on loans held by Fannie Mae. Not sure it is going to happen, as it would undoubtedly trigger a wave of strategic defaults. Interesting that the couple mentioned in the article said they refinanced into a loan with “abusive” terms. A Fannie Mae loan was abusive? Or was this part of the American Dream Commitment, where Fannie partnered with the big subprime players like Countrywide, Irwin, Doral, etc. and agreed to buy their loans for their own balance sheet. Anyway, it looks like Mel Watt is giving the affordable housing advocates the Heisman and running out the clock on principal mods, much to the chagrin of the left.

Potential merger in the real estate data industry: Zillow and Trulia are examining a potential merger.

Good summary of earnings from the homeboys. Orders in units are flat / down (except for D.R. Horton), and ASPs are up. With home prices leveling out, that game isn’t going to last.

Morning Report – New Home Sales and China’s property bubble 7/24/14

Markets are higher this morning on decent earnings. Bonds and MBS are down.

Initial Jobless Claims came in at 284k, the lowest print since 2006. Consumer Comfort inched up in last week.

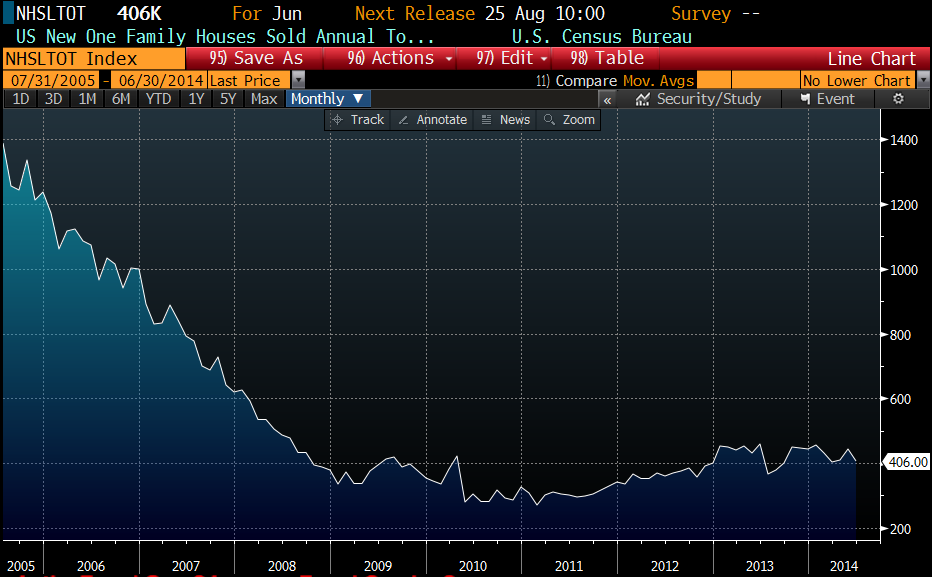
Remember that blockbuster new home sales number last month? 504,000 units? Revised down to 442k. June new home sales came in at 406k. I remember looking at the strong May number and trying to reconcile it with the weak numbers out of KB Home and Lennar, which were announcing earnings at the time. Turns out the new home sales number was bad. You can see how depressed new home sales are from peak levels almost 10 years ago.

New home sales bbg

D.R. Horton reported earnings this morning, as orders increased 32% in value and 25% in units. The cancellation rate was 24%, though. Interestingly, gross margins fell, which is the first we have seen. The builders have been able to increase prices faster than input costs have gone up. That said, there were some special items in that number so the year-over-year decrease could be misleading. The stock is down this morning.

PulteGroup also announced numbers this morning. Average selling prices rose 12% to $328,000, and gross margins came in at 23.6%, up 480 basis points year over year. Closings dropped 9% in units, however, so Pulte looks to be following the typical builder pattern of higher prices / lower units. PHM is down this morning.

China is in the midst of a skyscraper-building craze. This sort of thing is reminiscent of the 1920s, where the Chrysler Building and 40 Wall Street were neck and neck to build the tallest skyscraper. The Chrysler building won out by constructing the spire inside the building and then pushing it through the top at the very last minute. However their position as tallest was eclipsed by the Empire State Building in the years following. As a general rule, tallest skyscrapers tend to be associated with market tops. Think Chrysler and the Empire State Building prior to the Depression, the Petronas Towers in Kuala Lumpur ushered in the Asian Crisis. China has been going through a period like the US did in the subsequent WWI era – rapid growth and urbanization. They will probably have to go through a gut-wrenching bust like the Depression as well.

Note that China is the biggest international player in the US residential market, and is pushing up prices in Los Angeles, San Francisco, San Diego, New York, and Seattle as professional investors buy up properties sight unseen. Once the Chinese bubble bursts and things start getting ugly, look for these same investors to begin unloading properties in these cities. Remember in a crisis, you sell what you can, not necessarily what you want to.

From “The Economist” – an ethics test

Economics and ethics

Lying commies

The more people are exposed

to socialism, the worse they

behave

My other car is a Porsche

“UNDER capitalism”, ran the old Soviet-era joke, “man exploits man. Under communism it is just the opposite.” In fact new research suggests that the Soviet system inspired not just sarcasm but cheating too: in East Germany, at least, communism appears to have inculcated moral laxity.

Lars Hornuf of the University of Munich and Dan Ariely, Ximena García-Rada and Heather Mann of Duke University ran an experiment last year to test Germans’ willingness to lie for personal gain. Some 250 Berliners were randomly selected to take part in a game where they could win up to €6 ($8).

The game was simple enough. Each participant was asked to throw a die 40 times and record each roll on a piece of paper. A higher overall tally earned a bigger payoff. Before each roll, players had to commit themselves to write down the number that was on either the top or the bottom side of the die. However, they did not have to tell anyone which side they had chosen, which made it easy to cheat by rolling the die first and then pretending that they had selected the side with the highest number. If they picked the top and then rolled a two, for example, they would have an incentive to claim—falsely—that they had chosen the bottom, which would be a five.

Honest participants would be expected to roll ones, twos and threes as often as fours, fives and sixes. But that did not happen: the sheets handed in had a suspiciously large share of high numbers, suggesting many players had cheated.

After finishing the game, the players had to fill in a form that asked their age and the part of Germany where they had lived in different decades. The authors found that, on average, those who had East German roots cheated twice as much as those who had grown up in West Germany under capitalism. They also looked at how much time people had spent in East Germany before the fall of the Berlin Wall. The longer the participants had been exposed to socialism, the greater the likelihood that they would claim improbable numbers of high rolls.

The study reveals nothing about the nature of the link between socialism and dishonesty. It might be a function of the relative poverty of East Germans, for example. All the same, when it comes to ethics, a capitalist upbringing appears to trump a socialist one.

Morning Report – Who is paying for homeowner relief? 7/23/14

Stocks are higher this morning as second quarter earnings are generally better than expected. Bonds and MBS are flat

Mortgage Applications rose 2.4% last week, according to the Mortgage Bankers Association. Purchases rose.3%, while refis rose 4.1%. The MBA backs up the data we have seen from Bankrate- as the 10 year (and TBAs) have rallied over the past month, mortgage rates are flat, except for jumbos, which have dropped 7 bps over the past month. I suspect it is evidence that riskier loans are being done.

When the government settled with the big banks and demanded debt relief, most of the relief came from portfolio loans, but some did not. About 39% of Bank of America’s relief came from loans that were investor-owned – in other words, the money came from someone else’s pocket, not Bank of America’s. It looks like the number at JP Morgan was even higher – 44%. In other words, these banks got fined, but the investors (pension funds, 401ks, mortgage REITs) ended up paying the fine. Of course the best one was Ocwen, who provided $2 billion in relief. The catch? Ocwen is a servicer and simply passes on payments from borrowers to investors. They paid their fine with other people’s money. The Association of Mortgage Investors (AMI) is rightly calling foul. The government is not commenting, although it is stuff like this that partially explains why the private label market hasn’t come back yet. Once bitten, twice shy.

Split decision yesterday on Obamacare. Looks like this one might have to be settled at the Supreme Court. Separately, the IRS destroyed hard drives in the targeting probe. Lots of partisan bickering to pedal into campaign donations before midterm elections. Democrats and Republicans pretty much despise each other at this point. Such is the political climate as Congress goes on break.

Morning Report – More unintended consequences of ZIRP 7/22/14

Stocks are higher this morning as earnings reports pour in. Bonds and MBS are flat.

Existing Home sales rose 2.6% month over month to an annualized 5.04 million pace, according to NAR. The median home price rose to $223.3k (up 4.3% YOY), while the average price rose to $269.1 (up 3.1% YOY). Distressed sales accounted for 11% vs 15% a year ago, while the first time homebuyer slipped a point to 28%. All cash deals were basically flat at 32%, and days on market rose from 37 to 44. The housing market is becoming more balanced as inventories are increasing and prices are leveling off.

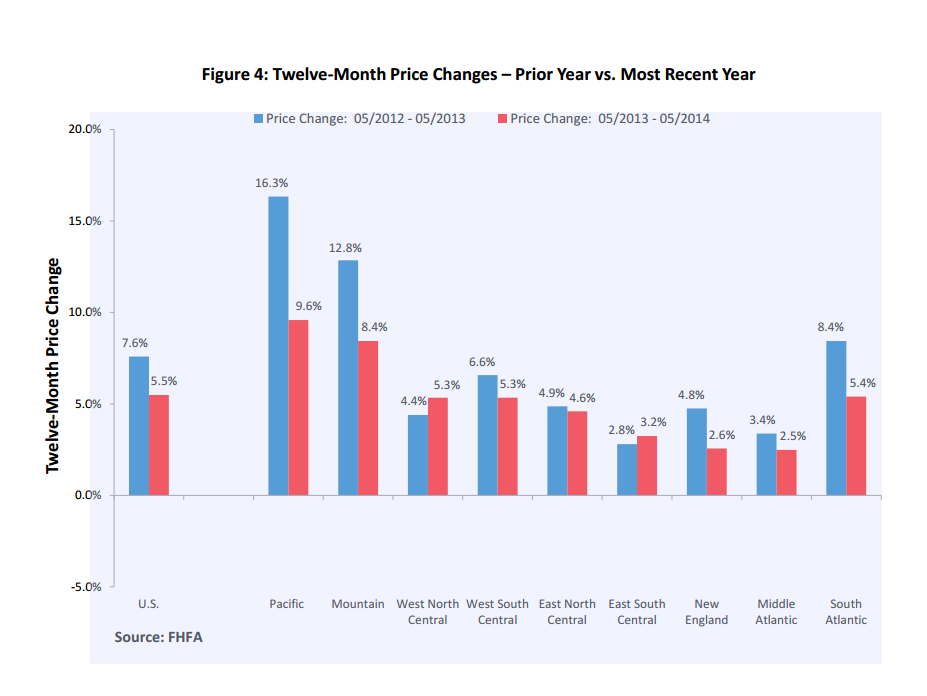
Home prices rose .4% in May, according to FHFA. This is up 5.5% year-over-year. Remember the FHFA index only looks at homes with conforming mortgages, so it is a narrower index than Case-Shiller. The West Coast performed the best, and the Midwest / Mid-Atlantic performed the worst.

FHFA HPI Geographic

The Consumer Price Index came in at .3%, bang in line with expectations. Ex-food and energy, it rose .1%. On a year over year basis, the CPI headline number increased 2.1% and ex food and energy it was 1.9%, more or less where the Fed would like to see the inflation numbers. Note that the Fed prefers to use PCE (Personal Consumption Expenditures) not CPI.

A good backgrounder on Bloomberg about returning vets and VA loans. The VA’s share of new mortgages is at a 20 year high. The stat that jumped out at me was this: VA loans accounted for 8.1% (just under $20 billion) of mortgages made in the first quarter. Last year, VA’s share in Q1 as 6.9% and 10 years ago it was under 2%. The record was 28% in 1947. VA and FHA are tailor made for the first time homebuyer, who wants to buy, but feels shut out of the market.

Speaking of first time homebuyers, here is another article discussing how the economy is depressing birth rates, which would influence household formation numbers. Classic catch-22: The economy needs the housing sector to at least get back to historical norms, but the first time homebuyer is the key to that and they won’t get in until the economy improves.

As a follow-up to yesterday’s comment about the Fed and their belief that (a) low interest rates don’t cause bubbles, and (b) bubbles can be prevented by smart regulation, the appetite for second-lien junk is increasing. Formula One is paying L+6.75 for a $1 billion covenant-light junior loan. Second lien paper is yielding about 9%, while first-lien is yielding about 5.3%. Interestingly, the better credit spreads are widening, while the junkier stuff is tightening. This is of course the unintended consequence of ZIRP, and the biggest risk for 2015 / 2016. The markets are blithely assuming the Fed can start raising rates without any negative consequences for the economy. The economy shook off the end of QE, so there is reason for hope, but I wouldn’t rule out someone big blowing up as rates start increasing, and it will be the junkiest stuff that gets hit the hardest.

Morning Report – What fair lending laws really do 7/21/14

Markets are lower this morning on no real news. Bonds and MBS are up small.

Earnings season kicks off in earnest this week, with a lot of market heavyweights reporting. With the stock market at record highs, it is vulnerable if companies start missing or guiding down for the second half of the year.

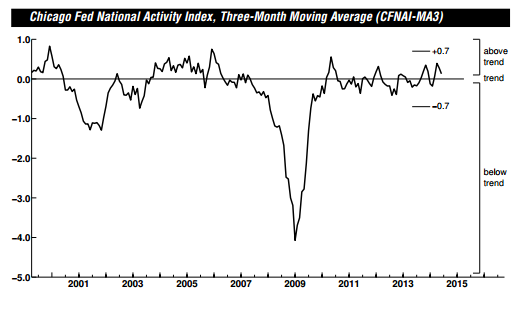
The Chicago Fed National Activity Index decreased to .12, lower than estimates. May was revised downward as well. Production indicators were flat, however employment was a big positive contributor. This index is notoriously volatile, so it makes sense to look at the 3 month moving average, which has been declining over the past couple of months.

Chicago Fed Natl Activity Index

As bonds have rallied these past couple of week, mortgage rates have gone up. The spread between the Bankrate 30 year fixed rate mortgage and Treasuries has blown out. Not sure why this is happening – TBAs have been rallying with bonds, so it isn’t necessarily MBS related. It could simply be something funky with the data which will get corrected. Another possibility is that mortgage bankers are moving out on the risk curve and doing loans they would have turned down a year ago.

Mortgage spreads

Jamie Dimon’s comments about ending FHA loans raises questions about how it can meet its CRA goals. If it doesn’t do FHA loans, it will have to portfolio some more CRA loans. Jamie Dimon said on the conference call regarding fair lending quotas: “Yes, if you don’t do any FHA, that hurts you a little bit. But to do FHA and lose billions of dollars, that’s a whole different level of shareholder irresponsibility.” Implicit in that statement is the idea that CRA loans are losers and a cost of doing business. Which flies in the face of the standard fair lending talking points that banks are avoiding perfectly good loans out of racism. The truth is that the fair lending advocates are forcing banks to subsidize low income borrowers. Who pays? Everyone else who has a mortgage. It would be nice if the government was intellectually honest about CRA loans – saying we want low-income people to get mortgages, we don’t want banks to fully charge the borrower for the added risks they represent, and we don’t want to pay for it. So we will force other borrowers to subsidize these loans. The government is simply being generous with other people’s money.

Speaking about talking points, one of the big ones out of the Fed is their belief that bubbles are (a) not caused by too-low interest rates and (b) regulation of banks can prevent them from taking risks they shouldn’t be taking. This theory is being tested as we speak, in the high yield market. The issue is that when rates are super-low, investors HAVE to move out on the risk curve to make any money. The demand is there. Think about it this way: if you are an insurer or pension fund, the actuarial tables couldn’t care less that money is free. You still have to hit your return bogey. And if you can’t do it in low-risk products, you’ll have to do it in high risk products.