Morning Report – Is the labor market at a tipping point? 8/11/14

Markets are higher this morning on easing international tensions. Bonds and MBS are flat.

Not a lot of economic data this week – the highlights will be industrial production and capacity utilization on Friday and retail sales on Wednesday. Earnings season is winding down, with mainly the retailers left.

Goldman Sachs looked at student loan debt and the Millennial generation to determine how much student loan debt inhibits home ownership. It looks like $50,000 worth of debt is the tipping point – young adults with more than that in debt have a homeownership rate that is estimated to be 8 percentage points lower than graduates with less than $50,000 in debt. The conclusion of the study is this: The benefits of a college degree outweigh the costs, provided the degree helps boost income, and the student loan debt is not too large.

Bloomberg has a good backgrounder on the changing dynamics of the labor market. The balance of power is shifting more towards employees from employers. The missing piece of the puzzle has been wage inflation, and we may finally be at that point. Separately, eHarmony, the dating site, is getting into the career business.

Confounded by the rally in bonds this year. You are not alone.

Ellie Mae is buying AllRegs for $30 million in cash.

Stonegate reported second quarter numbers last week. Originations grew 37% versus Q1 and were up 59% year-over-year. These are not “apples-to-apples” numbers are Stongate bought Medallian and Nationstar’s wholesale business. Gain on sale margins increased 23 basis points.

Morning Report – Bond market continues to rally 8/8/14

Markets are higher this morning on no real news. Bonds and MBS are higher on international tensions. The 10 year bond yield is sporting a 2.3 handle this am.

Nonfarm Productivity rebounded to +2.5% in the second quarter. The first quarter was revised downward to – 4.5%. Unit Labor Costs rose .6%, while the prior quarter was revised upward from +5.7% to + 11.8%. BLS attributes the increase in costs to the downward revision in productivity and and a big upward revision in compensation from .4% to 4.8%. Not sure why BLS’s initial numbers were so far off.

Gutsy call on the bond market: Komal Sri-Kumar is predicting the 10 year will be trading with a 1 handle in six months. He thinks international tensions will be a drag on consumer confidence and he even suggests the Fed could re-start QE in 2015.

FWIW, economists are predicting 2.9% GDP growth in Q3 and 2.6% growth in Q4.

Wholesale sales and Wholesale inventories both came in lower than expected.

Morning Report – Why the recovery has been so tepid 8/7/14

Markets are higher on earnings and a low initial jobless claims number. Bonds and MBS are down small.

Today is the first Thursday of the month, which means same store sales from the retailers. So far it looks like they are coming in a bit better than expected.

Initial Jobless Claims came in at 289k, the lowest level in 8 years. Bloomberg’s weekly consumer comfort index fell to 36.2.

Mortgage delinquencies fell to 6.04% in the second quarter, according to the MBA. Foreclosures fell to 2.49%.

Fannie Mae earned $3.7 billion in Q2, of which all went to Treasury. They modded 32,000 loans in the quarter as well. Delinquencies dropped to 2.05%.

The next global economic headache is the bursting of China’s real estate bubble and the potential for a protracted slowdown. There is a “buyer’s strike” going on and so far developers are not lowering prices yet. So inventory builds. Inventory is 23 months worth of sales in the top 20 cities. To put that number into perspective, 6 months is considered normal, at least in the US. This is generally how busts begin. If it becomes “the one” then trophy properties in the US, particularly the West Coast will become vulnerable.

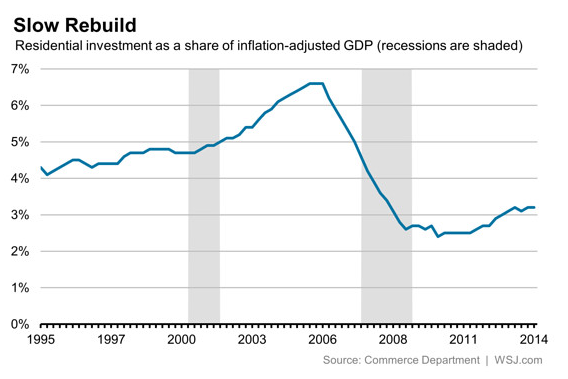
The WSJ has a good piece on the weakness of housing, particularly housing construction. As we know, housing starts have been mired below 1 million units for what seems like forever. Normalcy is around 1.5 million units historically. When you look at residential construction’s contribution to GDP, it is been about 2.5% – 3%, much lower than its pre-bubble level of 4% to 5%. Not only that, but residential construction usually leads an economy out of recession. I had hoped this would be the year starts got back to normalcy, but the homebuilders have seemed content to increase the top line through price hikes, not volume increases.

Residential construction as a percent of GDP

Morning Report – Bonds signalling a slowdown? 8/6/14

Stocks are lower after some bearish economic news out of Europe. Bonds and MBS are rallying. The 10 year bond is right at its May highs.

Mortgage Applications increased 1.6% last week, according to the MBA. Purchases fell 1.3% while refis increased 3.8%. It looks like overall mortgage rates increased 3 basis points or so over the week, while the 10 year was flat. Refis accounted for 55% of all loans, the highest percentage since May.

Wells is getting even more aggressive in the jumbo space. Minimum FICOs for a fixed rate jumbo have been lowered to 700 from 720. They also now do cash-out refis on jumbos and are buying jumbos on second homes on a correspondent basis. This is why the jumbo space is so competitive – banks can subsidize the jumbo mortgage and use that as an opening to pitch other bank services to the customer, particularly asset management.

Walgreen’s has decided to not pursue the tax inversion trade after intense political pressure from Washington. They will still purchase the remaining part of Alliance Boots, but will keep their headquarters in Chicago. This change will cost the company about a billion in excess taxes. If I was an arb, I would be nervously looking at my Abbvie / Shire position, and my Covidien / Medtronic positions, which are blowing out this morning.

Corporate inversions are going to be a political football going into midterms. First of all, nobody likes them. Companies don’t really want to do them, but they have to honor their fiduciary responsibilities. Politicians on both sides of the aisle despise them. The tax code is going to be changed to prevent them in the future. However, Republicans don’t feel much need to negotiate now, as they are pretty much guaranteed to keep the House and may in fact take the Senate. So their negotiating power can only get bigger. The Administration is pushing the “fix the inversion part of the tax code first, and then let’s do full tax reform later” argument. Of course Obama knows that he is going to have to trade closing loopholes for lower rates, so he wants to sneak in a freebie before negotiations start. That is a nonstarter for Republicans. Which gives Obama an opportunity to demagogue the issue and paint Republicans as defenders of corporate tax dodgers as the consolation prize.

Arbs are already reeling as Rupert Murdoch withdrew his offer for Time Warner last night. Fox also announced a big buy back, so arbs are getting killed on both sides of the trade. Tough, tough day to be in the risk arbitrage business…

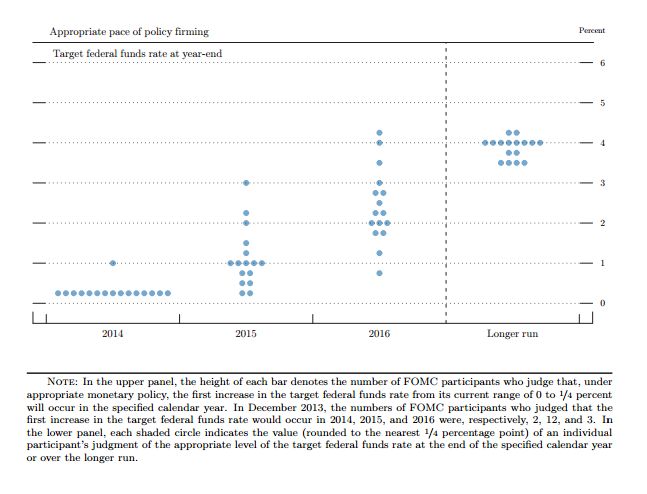
Watch the data. The latest ISM numbers were quite strong, and Dallas Fed President Richard Fisher is predicting that rates will have to increase sooner than it projected in the June dot plot if this economic strength continues. Remember the Fed’s “dot graph” – the dots for a tightening will move up. Fisher also said that the debate among the central bankers is “coming in my direction.” Bottom line – for the last 6 years you have been able to dismiss the hawks. The ground is shifting.

fed funds dot graph

Counter-argument: The bond market is warning about a slowdown. At least one market strategist thinks the 10 year is heading to 2.2%. True, when the stock market and the bond market disagree, you usually want to side with the bond market. However, you have to keep in mind what is happening overseas and the concept of relative value. The German 10 year Bund yield has hit fresh lows – 1.104%. When rates are falling overseas, they will inevitably drag US Treasuries with them, simply due to relative value. FWIW, I don’t think the US bond market is signalling weakness in the US economy. Nor does Goldman.

Morning Report – Strong ISM numbers 8/5/14

Markets are lower on no real news. Bonds and MBS are down small.

The ISM Non-Manufacturing Index increased to 58.7 in July, a strong number. In fact, this is the highest reading since inception (with the caveat the index started in Jan 2008). Employment ticked up again, and new orders are accelerating. Prices are not increasing.

Factory orders increased 1.1% as well, but the IBD / TIPP economic optimism index declined.

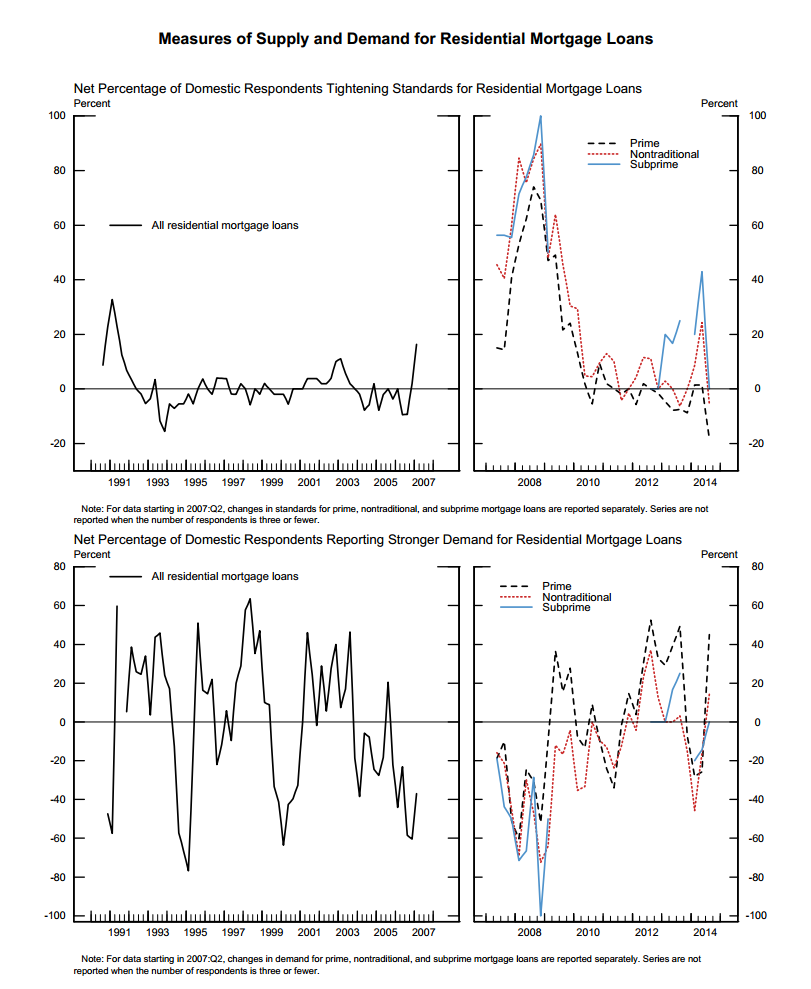
The Fed Senior Loan Officer Survey is out, and it discusses non-QM lending. The majority of banks reported that the rule had no effect on prime conforming mortgages (unsurprising since if it is conforming, it is QM compliant), but about half the respondents indicated QM reduced approval rates on applications for prime jumbo loans and non-traditional mortgages. That said, it is clear from the charts below that credit is easing, and demand is picking up.

Fed SLO

Yet another unintended consequence of financial regulation – closing costs for mortgages have increased 6% YOY and in some places are up 20% +.

Home prices are up 1% month-over-month, and are within 13% of their April 2006 peak, according to CoreLogic.

The out-of-office email reply, deconstructed.

Obama to business: Stop complaining!

Morning Report 8/4/14

PLACEHOLDER FOR BRENT.  BRENT, PLEASE EDIT.


The rest of you can use it as an open thread, or not.

If It Saves One Life

This is something I’ve been thinking about for a long time.  I doubt any of the rest of you are interested in this phenomenon but I’ve found it to be very true in my own experience.  Once tragedy strikes, especially one we believe could have been prevented, we tend to change our minds about numerous things.  That old saying “if it saves one life it’s worth it”, which the guy quoted below actually says at the end of his testimony, and most of us know is not a very legitimate tool to use to bring about change, suddenly has meaning.

When I think back to the Health Care debate and why it was so important to me, Daniel’s story about his sister’s death, matched my own perception of that debate at the time because of my niece’s death.  During the years I fought for health care reform I met hundreds of people whose stories were similar to my own.  And honestly, they weren’t all hot-headed progressives (and I’m not either although I do get hot-headed about health care inefficiencies).  Most of them were simply hard working Americans who had a terrible story to tell about a health care system that had failed.

I think this is one of the reasons so many of the provisions in the ACA are popular while the bill itself isn’t.  Some of us can imagine what it would be like to not have these new regulations or know someone who is benefiting from them now.  And so even though the bill is a mess in so many ways, they’re grateful for it in other ways.  It’s interesting to me that the polling is so skewed.

Anyway, my point really is just that while I really am not impressed with the bill that became the ACA, either during it’s development or now, I still can’t help but be grateful that someone elses family won’t have to suffer the same terrible loss that we suffered.  That brings it down to the most personal level which is exactly what Daniels is talking about.  This is when, right or wrong, people look to their government for help…………………most of us don’t really have anywhere else to go to find the same kind of resolution to an injustice.  If the ACA had been in effect at the end of 2007 chances are very likely my niece would be alive today………………that’s a really life altering scenario to think about.

There’s a part of me that wishes things were different because I know it’s not necessarily fair to the rest of you who make it through life without this kind of event or are able to separate your logical and principled selves from needing or desiring any kind of assistance yourself.  The idea that a man like Daniel, could now be attempting to influence a debate about background checks tells me all I need to know about reality.

WASHINGTON — Elvin Daniel, 56, is a card-carrying member of the National Rifle Association, an avid hunter and a self-described “constitutional conservative” from a small town in Illinois. He became an unlikely witness for the Democrats on Wednesday at the first-ever Senate Judiciary Committee hearing on gun violence against women.

Daniel choked back tears at the hearing as he recounted the story of his sister, Zina, who was shot and killed by her estranged ex-husband in 2012. After her ex slashed her tires and physically threatened her, Zina had obtained a restraining order against him, which should have prohibited him under federal law from buying a gun. But he was able to purchase a gun online, where private sellers are not required to conduct background checks.

“Now I’m helping to care for my two nieces who lost their mother and who will have to grow up without her,” Daniel told the committee. “I’m here today for Zina and for the stories like Zina’s that happen every day because of the serious gap in our gun laws that continue to put women’s lives in danger.”

American women account for 84 percent of all female gun victims in the developed world, and more than a quarter of female homicide victims in the U.S. are killed by an intimate partner.

The two bills being considered in the Senate, introduced by Sens. Amy Klobuchar (D-Minn.) and Richard Blumenthal (D-Conn.), would strengthen federal gun prohibitions for convicted domestic abusers and those deemed by a judge to be a physical threat to a woman. Klobuchar’s bill would include physically abusive dating partners and convicted stalkers in the category of persons who are prohibited from buying or possessing a gun. Blumenthal’s bill would ban guns for those who have been issued a temporary restraining order by a judge for domestic violence.

All the provisions being discussed are supported by a majority of Americans, according to a recent HuffPost/YouGov poll. But gun limits are difficult for Congress to pass, even when they are broadly supported by voters, due to the strong opposition of the well-funded and well-organized gun rights lobby. A popular bill that would have closed gaping holes in the federal background checks system fell just short last year of the 60 votes it needed to overcome a Republican filibuster.

The NRA is already fighting Klobuchar’s bill, claiming that it “manipulates emotionally compelling issues such as ‘domestic violence’ and ‘stalking’ simply to cast as wide a net as possible for federal firearm prohibitions.”

“If we can save just one life, that would be worth everything we’re going through,” Daniel said. “And I know we can save more than one life.”

Daniel’s Testimony and More is from Huffingpost which I realize is a very partisan source.  I read about it somewhere else but now can’t find the source.  At least it’s not Reuter’s Scott…………………LOL

Here’s a little less partisan one but still not the one I was looking for.

Morning Report – Deluge of data 8/1/14

Stocks are lower this morning after yesterday’s bloodbath. Bonds and MBS are up.

The jobs report came in weaker than expected. Payrolls increased by 209,000, and the two-month payroll revision was +15,000. The unemployment rate ticked up to 6.2% and the labor force participation rate rose to 62.9% from 62.8%. However hourly earnings were flat and average weekly hours were flat as well. The lack of wage pressure cheered the bond market, which is clawing back yesterday’s losses. FWIW, the employment cost index showed a .8% increase in wages yesterday (benefits are calculated separately), so the lack of wage growth as reported by BLS is surprising.

By the way, for the bond market to start worrying about wage inflation, you will need to see increases in average wages of about 4%, not the 2% inflation target. Why? Productivitiy, which is running about 2% (notwithstanding the lousy print in Q1). Wage inflation that is offset by productivity increases is not inflationary. So, when you think about the US needing 4% wage growth just to get to the Fed’s inflation target, you can see we have a long way to go.

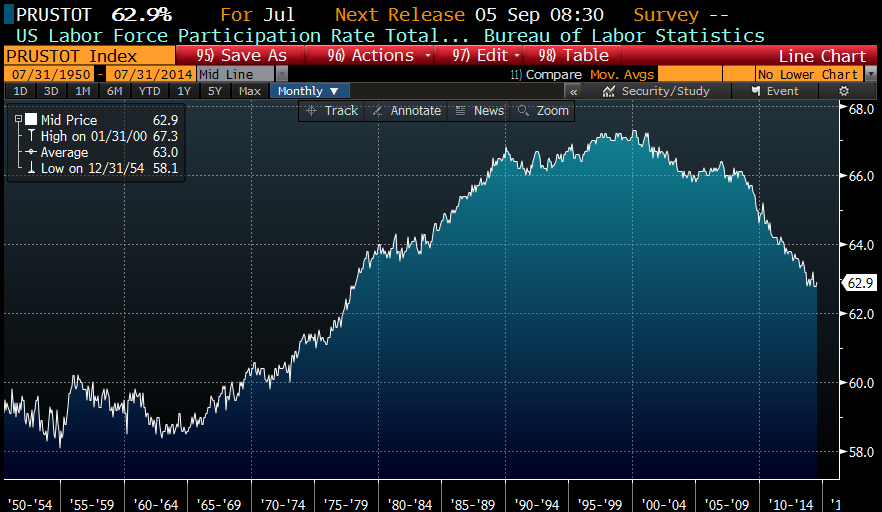
Still, we aren’t going to see a robust economy until the labor force participation rate gets back to normal levels. As you can see from the chart below, about half of the increase in the labor force participation rate that was attributable to women entering the workforce starting in the 1960s has been given back. That low number represents excess capacity that isn’t being captured with the headline unemployment number. Which is why wage growth is so hard to come by (the other reason being technology).

Labor force participation rate bbg

Personal Spending rose .4% in June, and Personal Income rose .4% as well. The core personal consumption expenditure index rose 1.5% year-over-year, still below the 2% target the Fed would like to see.

The ISM numbers came in stronger than expected, showing that manufacturing continues to do well, A 57.1 number would correspond to GDP growth of 4.6%. Of course manufacturing doesn’t dominate the economy (and employ people) like it used to, but it is still a good, strong number.

Finally, construction spending slipped 1.8% in June after increasing an upwardly-revised .8% in May. Resi construction fell .2% month-over-month but is up 7.1% year-over-year.

Morning Report – Calm before the storm

Markets are lower this morning after some earnings misses. Bonds and MBS are down. Argentina missed a bond payment

Initial Jobless Claims climbed back above 300k last week, however Challenger’s announced job cuts number increased 24%. The ISM Milwaukee index rose to 63.87. However the Chicago Purchasing Managers index slumped by 10 points in July, coming in way below expectations.

The FOMC statement was slightly more hawkish than previous statements as the Fed edges more towards normalization. Bonds rallied slightly on the statement, but gave it back towards the end of the day.

Tomorrow is a big day with the jobs report and the ISM report. Plus, it is a summer Friday, which means thinly-staffed desks and probably some added volatility. I would not want to be floating going into tomorrow’s numbers.

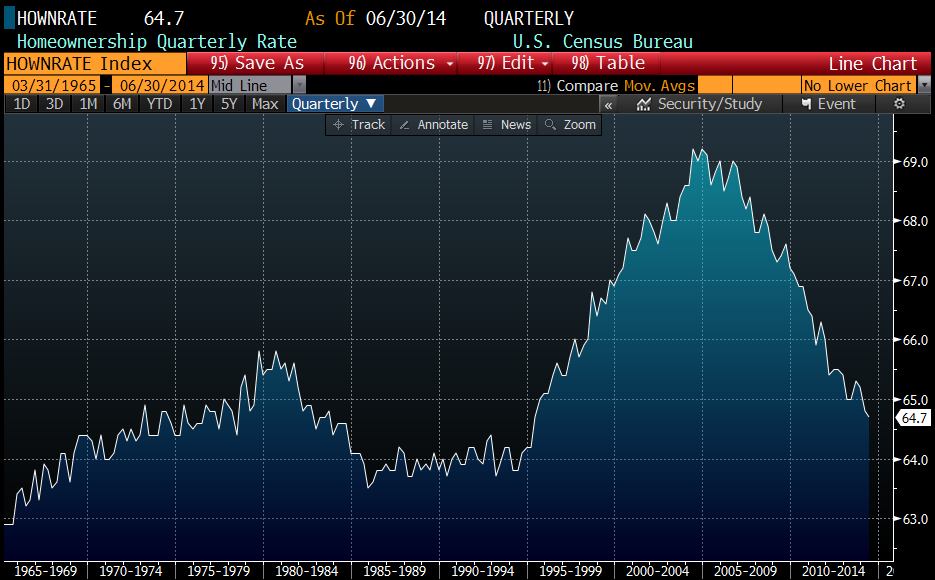
The homeownership rate in the US fell again last quarter, to 64.7%, the lowest rate in almost 20 years. Separately, the rental vacancy rate fell to 7.5%. The Millennial generation is still stuck renting because they are lugging high levels of student loan debt and are facing a tight credit environment for the first time homebuyer.

Chart: Homeownership rate 1965 – Present
homeownership rate bbg

Morning Report – Big GDP number 7/30/14

Markets are higher this morning on a strong GDP numbers. Bonds and MBS are selling off.

We will get the FOMC rate decision this afternoon. Since there are no economic forecast revisions and no press conference, I expect it to be a non-event with an announcement of another decrease in asset purchases and no change in interest rates. The interesting stuff probably won’t make it into the press release and we will have to wait for the minutes.

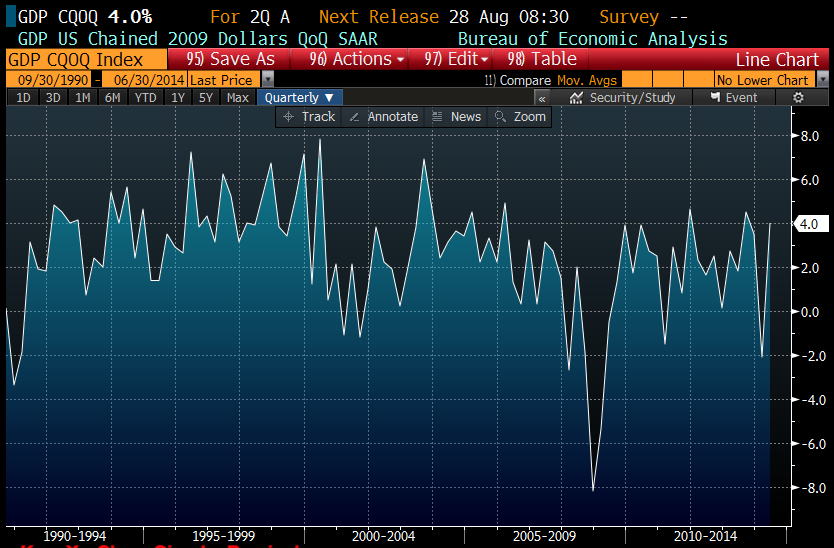
The advance estimate for second quarter GDP came in at 4%, a strong rebound from the revised -2.1% pace in Q1. The Street was at 3%. People were expecting a strong Q2 number as the first quarter number was depressed due to the weather and activity undoubtedly was pushed into Q2. Personal consumption came in at 2.5%, again a better than expected number. I would caution that the advance estimates of GDP have been WAY off lately – the advance estimate for the first quarter was +0.1% and the final number was -2.9% (subsequently revised up to -2.1% as the government made some baseline adjustments). Inflation came in at 2%..

The internals for the GDP number: big jump in consumption, especially durable goods and autos. Not surprising – the average age of a car in the US is something like 11.4 years, which is a record. Gross private domestic investment (in other words capital expenditures) rose by a lot. My suspicion is that was weather-driven. Government spending increased as well. Overall, the strong number should not have been a surprise given the strong data we have been seeing lately

Chart: GDP QOQ growth 1990 – 2014

GDP bloomberg

The ADP payroll number came in weaker than expected: 218k versus 230k. The Street is at 231k for Friday’s payroll number. Note that ADP uses a model to predict the number while BLS uses a sampling methodology. ADP’s number is designed to match the final BLS number, not the initial one, though it has been pretty spot-on the last couple months.

This strong economic data does kind of beg the question of whether the Fed is getting behind the curve. QE will probably end sometime this fall, but the Fed could find itself by the end of the year substantially at its inflation and unemployment targets, with rates still at zero percent and a balance sheet four times the size it should be. I think the Fed is fine with erring of the side of caution and doesn’t want to make the mistake the Bank of Japan did and tighten before the economy was hitting on all cylinders. I think the Fed will probably hold rates at or close to zero until we start seeing wage inflation. That will be the tell, IMO.

Mortgage Applications fell 2.2% last week as purchases rose .2% and refis fell 4%. Bonds were flat last week, and MBA has the average 30 year fixed rate mortgage flat at 4.33%, while Bankrate had it increasing from 4.27% to 4.33%.