Morning Report: The median house price hits a record 7/22/15

Stocks are lower as earnings have been generally disappointing. Bonds and MBS are up small.

Earnings season is off to a lousy start, highlighted by a miss from Apple. The stock is down 8% pre-open. IBM and United Technologies (which is selling its Sikorsky unit to Lockheed) reported disappointing earnings as well. The NASDAQ has been hitting records lately (it finally eclipsed its early 2000 high), but earnings are looking like a headwind.

Existing home sales rose 3.2% to a seasonally adjusted annual rate of 5.49 million units, the highest number in 8 years. Lawrence Yun, NAR chief economist, says backed by June’s solid gain in closings, this year’s spring buying season has been the strongest since the downturn. “Buyers have come back in force, leading to the strongest past two months in sales since early 2007,” he said. “This wave of demand is being fueled by a year-plus of steady job growth and an improving economy that’s giving more households the financial wherewithal and incentive to buy.”

Inventory remains tight as a drum, with 5.0 month’s worth of inventory, well below the 6.5 months that historically represents a balanced market. Time on market hit a record low of 34 days, down from 40 in May. The first time homebuyer represented 30% of sales, down from 32% in May and below its historical run rate of about 40%. All-cash sales fell to 22%, the lowest since December 2009.

The median house price rose to $236,400 a new record. Yes, we have surpassed the heights of the bubble years. That puts the median house price to median income ratio at a sporty 4.4x, well outside its traditional range of 3.15x – 3.6x and not far off its record of 4.8x. Either wage growth gets on its horse or further home price appreciation is going to be hard to come by.

Mortgage Applications rose 0.1% last week as purchases rose 1% and refis fell .5%. The 30 year fixed rate mortgage has been stuck at 4.23% for the last 3 weeks.

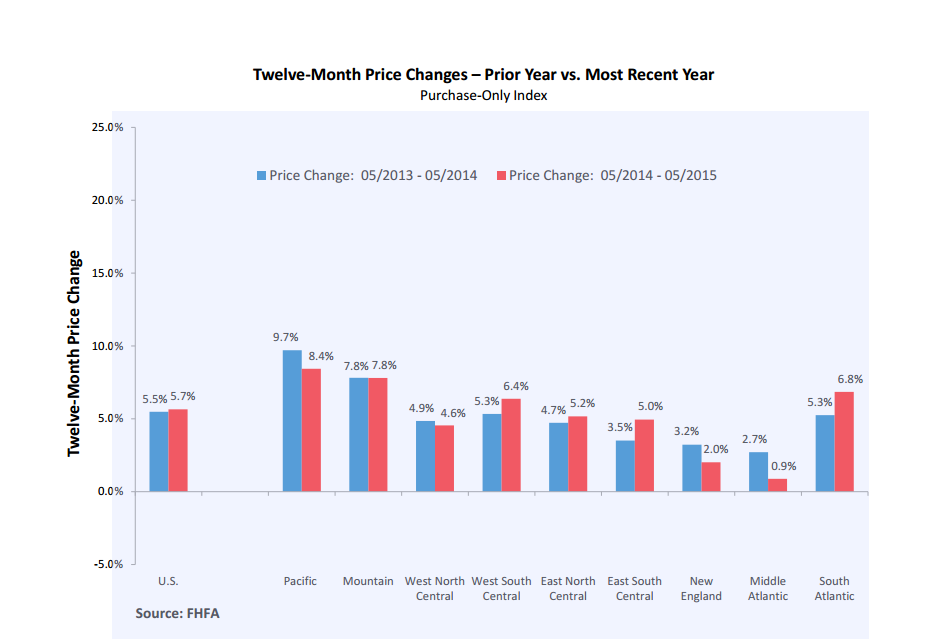
House prices rose 0.4% in May, according to the FHFA. On a year-over-year basis, prices are up 5.4%. Home prices are now about 1.8% from the peak in 2006. Note that this index only considers homes with conforming / government mortgages, so it excludes the jumbos and cash sales. While home price appreciation is accelerating nationwide, it is actually decelerating in the markets that have lagged the most – the Northeast and the Mid-Atlantic states. It has truly been a tale of two markets, with the red-hot West Coast and the ice-cold East Coast. That may be a result of increasing foreclosure activity in the Northeast / Mid-Atlantic judicial states.
Washington is looking for a way to fund infrastructure spending without raising the gasoline tax. It looks like at least one possibility would be to extend the 10bp Fannie Mae G-fee to 2025 from 2021. Banks may also see less dividend income on the shares of regional Fed bank stock they must hold.

Freddie Mac’s latest Housing Market Insight and Outlook is out, along with their forecasts for 2015 and 2016. 2015 GDP is forecast to be 2.2%, while 2016 is forecast to be 2.7%. The 30 year fixed rate mortgage is expected to be 4.0% for 2015 and 4.9% for 2016. Originations are expected to fall from 1.35T to 1.27T. They discuss why low downpayment loans are less risky now than they were in the bubble days.

Morning Report: Liquidity Issues Ahead? 7/21/15

Markets are lower this morning as earning pile in. Bonds and MBS are down small.

Dodd-Frank has severely neutered the market-making function of the banking system. When the Fed starts tightening and bonds sell off, the natural buyers of bonds (primary dealer banks) will no longer be able to dampen the moves by standing on the other side of the trade. The Fed is unconcerned about this, but we shall see what happens when rates start going up and the bond market starts falling faster than they are comfortable with.

Incidentally, Hillary will probably be forced to support a financial transactions tax, which is a tax on market-making as well. Basically it would slap a  tax on every stock trade, currency trade, and bond trade. Narrowing bid / ask spreads and a 90% drop in commission rates has basically eliminated the market-making functions (NASDAQ market makers, the specialists on the NYSE floor, block trading at banks) in the stock market. Machines are all that is left, and even they are not in the market-stabilization business. The next crash, they are going to suspend trading until things stabilize and there will be nothing but GTC (good till cancelled) buy orders for people to sell to. Washington should be careful what it wishes for.

As China’s economy cools off, and the US dollar rallies, we have seen commodities get absolutely slammed. Oil has been cut in half over the past year. Gold is in free-fall. Natural Gas is down big. This will keep a lid on inflation, and allow the Fed to keep rates lower longer.

Everyone knows that Chinese money has been behind the building boom in many large cities. This is actually driven by policy. Chinese investors who invest $500,000 and can prove that their investment created at least 10 jobs (not hard to do on a construction project) get permanent green cards. These are typically wealthy Chinese investors who are trying to get green cards for their kids and are not all that concerned about return on investment, which means dirt cheap financing for developers. Now, the government is thinking of making some changes. Obama would like these investors to put money in low-income housing, not luxury condos. Also, abuses in the program have led other to question it altogether. The program has bipartisan support so it probably isn’t going anywhere, but when you use policy as an economic lever you invariably create dislocations and marginal projects that don’t make economic sense. Something to watch.

Morning Report: Dodd-Frank 5 years on 7/20/15

Stocks are higher this morning after Greece made a payment to the ECB and re-opened its banks. Bonds and MBS are down small.

There is very little data this week – nothing today and tomorrow. We will get existing home sales on Wednesday and new home sales on Friday. Earnings season is in full swing and we will hear from heavyweights like Apple and IBM this week. Now that Greece and Chinese stocks seem to be stabilizing, I could see a gentle drift up in interest rates throughout the week.

Good housing numbers out of Census on Friday, with housing starts hitting 1.17 million and building permits hitting 1.34 million. Building Permits have risen by 200 units or so over the past two months, which portends an end to the tight supply we have been seeing in many real estate markets, which is causing bidding wars in some areas. The big improvement is largely in the Northeast, where permits are finally surpassing the levels in the West.

Chart: Building Permits: 1990 – Present

Interview with Chris Dodd and Barney Frank on Dodd-Frank 5 years later. Short summary: Dodd Frank is damn near perfect. A counter-take on it. Dodd-Frank did not end TBTF (too big to fail), however it does restrict credit, especially in mortgage banking (Barney Frank thinks D/F didn’t go far enough).

One of the unintended consequences of Dodd-Frank has been the pullback in liquidity in Treasury and corporate bond markets. Since Dodd-Frank prohibits proprietary trading, market-making has been pulled back as well, making Treasury markets more volatile, and according to studies has raised the interest rate the government pays on bonds by about 13 basis points or so. The side effect of this is that we will have more days like October 15, where Treasuries traded in a 36 basis point range as the market hit an air pocket during the day. What does this mean for LOs? Floating is going to be more dangerous.

Two Candidates That Will Not Get My Vote (nor that of Dave Ramsey). And it has nothing to do with politics. 7/16/15

I have long considered myself to be socially liberal and fiscally conservative (personally and politically). Personally, that means you live within your means and save up for the big stuff (cars, kids’ education, retirement). Politically, that means you pay for whatever government you want. You’re a small government conservative? Fine! Set taxes accordingly. You’re a big government liberal? Ditto! Make sure that current taxes cover current expenditures and capital expenditures are covered appropriately. If you sell off your toll highways to pay off a short term deficit, congratulations. You just took out a payday loan on the back of your taxpayers. With that as preamble, let us consider two case studies in fiscal liberals. Or, as Dave Ramsey would put it, freakin’ morons.
 
Ladies and Germs, I give you two candidates who could never get my vote.
 
On my right, let’s give a big hello to Marco Rubio. Republicans will regularly warn you that Social Security is a giant Ponzi scheme. Hence, you should prepare for funding your own retirement. I heartily agree with the latter portion of this and have socked away for retirement ever since I started making decent money in 2001. As Dave Ramsey says, live like nobody else now so that you can live like nobody else later. So, what did Senator Rubio do when he faced some cash flow problems. He cashed out his retirement funds! That’s roughly like borrowing money at 35% interest (10% penalty plus your tax rate). And what emergency did he face? Tell us, Marco:
 
“We wanted to have access to cash in the coming year both because I’m running for president but also my refrigerator broke down. That was $3,000. And I had to replace the air conditioning unit in our home,” the Florida Republican said on “Fox News Sunday.”
 
I hope you liked that fridge, Marco, because it just cost you $5000 ($5000 – 10% = $4500 * 2/3 = $3000). Senator Rubio evidently has no idea how to fill out a budget. I do sympathize, having just needed to replace our refrigerator (that we bought new when remodeling). As a fiscal conservative, I checked out the Fourth of July sales and picked up a very nice Samsung for a hair under $1,000 (with French doors no less). That $68,000 IRA that he cashed out probably would have grown to about $750,000 when he retired. But, hey, he’ll have a little mad money on the campaign trail.
 
To my left, a big round of applause for Martin O’Malley. What was his financial sin, you ask? He borrowed over $300,000 so his daughter could go to Georgetown. He utterly failed to save anything for his kids’ college education. When little snookums wanted to go to Georgetown like Grandpa, did he say, “Sorry baby girl, but we have an excellent university in College Park”? No! He went down to the bank and signed on the dotted line. And then he makes a campaign issue of student debt. Here’s a thought, Martin. If you can’t afford it, don’t buy it. I’d love to be tooling down the road in a Tesla right now. I don’t have the scratch, so I’ve got a 10 year old RAV4 (after our 15 year old Solara finally gave up the ghost).
 
Both Rubio and O’Malley are high earners and I’m sure will be able to make up the difference. However, for making two of the worst financial errors you possibly can, they’re dead to me. If you can’t be trusted with your own money, I’m sure as hell not going to trust you to be a responsible steward of my taxes.
 
BB

Morning Report: Housing Starts Tomorrow

Markets are higher this morning as Greece will get another shot of aid for its banks. Bonds and MBS are down.

The EU agreed in principle to a 7 billion euro bridge loan to Greece which will keep the lights on while Tsipras negotiates a bigger bailout loan. The deal still has to be approved by a number of countries, and the vote was actually more contentious that people were thinking it would be.

The Iran deal faces some opposition in Congress, but it will probably end up passing. I don’t see a major economic effect, aside from some pressure on North Sea Brent oil prices, which really only affects the East Coast. The rest of the country is based on West Texas Intermediate, and the two types of oil are not fungible. While the Republicans generally view the deal as a capitulation, the Democrats are split between the pro-Israel bloc and the far left bloc.

Initial Jobless Claims fell to 281k last week from 296k the week before. The Bloomberg Consumer Comfort Index slipped to 43.2 from 45.5 as well.

Janet Yellen continues her trek to the Hill today, and will appear before the Senate this afternoon. Yesterday’s testimony in front of the House was pretty uneventful. She didn’t deviate from the what she said after the June meeting – they want to get off the zero bound, but will be data-dependent.

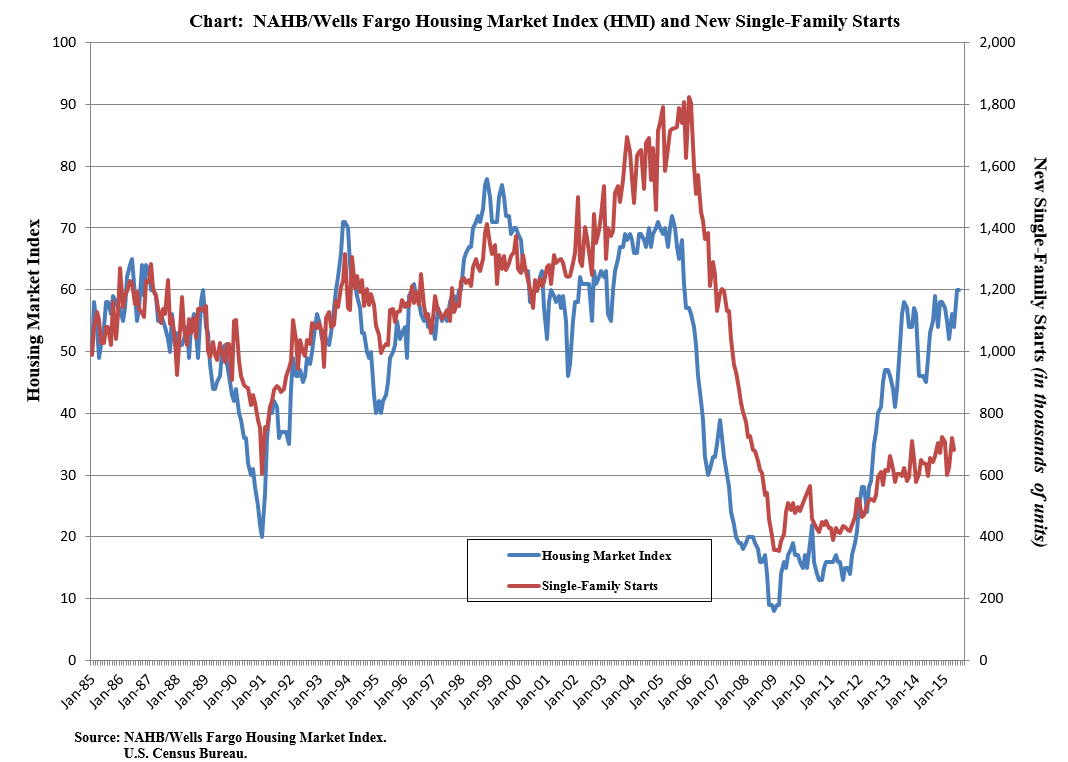
The NAHB Housing Market Index came in at 60, the strongest reading since early 2007. While builder sentiment has remained buoyant, it hasn’t really translated into housing starts. Typically, sentiment leads housing starts, and if the chart below is any indication, starts are lagging but need to catch up. I suspect they will as prices remain high and inventory remains tight. Note: we will get housing starts tomorrow morning. The Street is forecasting a 1.1 million run rate.

Morning Report: Janet Yellen testifying today

Stocks are flattish this morning as economic data and earnings pile in. Bonds and MBS are down.

Janet Yellen will testify in front of the House Financial Services Committee this morning at 10:00. Her prepared remarks are here. She is basically saying the economy is expected to re-accelerate after the Q1 weakness, and if that plays out as expected, the Fed will probably make the move off the zero bound later this year. The rest of the testimony will generally consist of Republicans trying to get her to say that government spending and taxes are too high, and Democrats trying to get her to say that income inequality is the biggest threat to our planet today.

Mortgage Applications fell 1.9% last week, as purchases fell 7.5% and refis rose 3.7%.

Inflation at the wholesale level came in a little hotter than expected – 0.4% on the headline number, and 0.3% on the ex-food and energy number.

Industrial Production rose 0.3% in June, a little better than the 0.2% expectation. Capacity Utilization rose to 78.4% from 78.2% last month. Manufacturing Production was flat. The Empire Manufacturing Index came in at 3.86. So manufacturing rebounded a little after a dismal start to the year.

Bank of America reported better than expected earnings this morning. Mortgage origination increased 40%.

Morning Report: Bank Earnings and Iran 7/14/15

Stocks are lower this morning after retail sales came in weaker than expected. Bonds and MBS are up.

Looks like we have a deal with Iran. Sanctions are lifted, but snap back if Iran violates any of the terms of the agreement. The immediate effect will to bring another 3 MM barrels of oil per day onto the market. Congress will have a vote on the deal.

Retail sales disappointed in June, with the headline number falling .3% versus expectations of a positive .3%. Ex autos and gas, they fell .2%, versus the .4% expectation. May strong numbers were revised down slightly. There appears to be some seasonal effects going on here (early Memorial Day “borrowed” sales from June) so don’t read too much into this number.

The NFIB Small Business Optimism Survey fell in June to 94.1 from 98.3. Weak sales and the political environment accounted for the decrease. Looks like hiring stopped in June.

Import prices fell .1% in June and are down 10% on a year-over-year basis.

Now that Tsipras has accepted the EU’s terms, he has to sell the idea back at home. Not going to be an easy task, but it will probably pass.

Hillary Clinton gave a speech yesterday on the economy, and it is more or less a grab-bag of assorted liberal ideas: increase the minimum wage, more aggressive enforcement of discrimination laws, paid family leave, free childcare, the usual.. She even went after Uber (who cheekily did a senior citizen promotion that day). It is clear she is feeling the #Bern and is worried about her left flank.

JP Morgan reported this morning that mortgage banking net income fell 20% in the quarter. Not a lot of color on mortgage banking in particular, however they are paying close attention to China (I’ll bet). The stock is up about 1 percent on the open.

Wells also reported this morning. Mortgage banking revenues fell 1% in spite of the fact that originations rose to $62 billion from $47 billion. Well’s market share fell to 13% from 28% three years ago.

Polygamy 7/14/15

Being of the school that hears the word polygamy and forthwith tires, imagining a competitive household in which it is revealed that under pressure at least one adult participant is nuts, I have never engaged in a discussion of multiple spousing.  And as a lawyer, I have never understood how an argument for polygamy as constitutionally protected could be made.  After all, there is no equal protection argument to be had.  But Kennedy’s loosy-goosy “due process” argument in the SSM case has perhaps opened a door a crack that could have remained slammed shut.  Certainly, Justice Roberts thought so.

So when I stumbled across this article in The Economist, I read it with interest and decided to share it here.

http://www.economist.com/blogs/democracyinamerica/2015/07/marriage-and-civil-rights?spc=scode&spv=xm&ah=9d7f7ab945510a56fa6d37c30b6f1709

I was struck by the author’s notion that it is libertarians who are actually pushing polygamy, and apparently liberals who oppose it.  I thought everybody opposed polygamy except some folks in Utah who have TV reality shows.

I felt vindicated by his citations of studies of the damage one can expect from polygamy, because they seem evident to me.

Nevertheless, I wonder what it will mean to say there is no right to polygamy, while never prosecuting cases and failing to remove children absent reported repeated physical abuse.  See:

http://www.nbcnews.com/id/23993440/ns/us_news-crime_and_courts/t/women-children-leave-polygamist-ranch/#.VaUFIJNVK1E

Frankly, that case was awful.  But that is what it has taken to enforce laws against polygamy in America.

Given three choices – recognizing polygamy, or banning polygamy with enforcement, or without enforcement – what do you think?


Morning Report: Greece capitulates 7/13/15

Markets are higher as it looks like the Greek situation looks resolved for the time being and Chinese stocks staged another rally. Bonds and MBS are down.

Endgame continues in Greece, where Prime Minister Alexis Tsipras has agreed to bailout terms, but now must sell the agreement to his own country. The summit agreement avoided a worst-case scenario for Greece, but many of the terms of the bailout have strings attached. Dr. Cowbell is despondent over the whole episode, as the Germans are really pushing Greece hard. Memo to Tsipras: Don’t bring up the Nazis when negotiating with the Germans.

Earnings season kicks off in earnest this week, with the big banks reporting. Note the Mortgage Bankers Association Mortgage Applications index is off about 16% during the quarter, so mortgage origination numbers could be light.

We have some big economic data this week, with retail sales tomorrow, industrial production on Wed, and housing starts on Friday. Bonds should still be at the mercy of international events however.

Janet Yellen spoke on Friday and said she expects the Fed to hike rates this year, however she cited weakness in the labor market as a reason for caution. I think the Fed is determined to make at least a symbolic move to get off the zero bound, but will tighten much more gradually than it did in the past. The exit from the post stock market bubble days was pretty dramatic, about 2 percentage points a year, or 25 basis points every meeting.

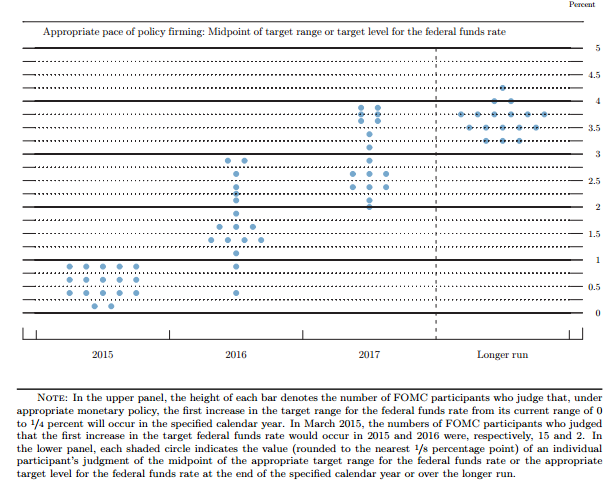
You can see from the dot graph from the June meeting that the FOMC is forecasting a slower liftoff, however we are still looking at a 350 basis point (roughly) tightening vs the 425 basis point tightening in 2004, which blew up the residential real estate bubble. Will this tightening campaign blow up the sovereign debt bubble? Or something else?

Rich State Poor State 2014 7/10/15

State

Dollars (millions)

Ratio to GSP

Revenue

Spending

Net

Revenue

Spending

Net

Alabama

23,789

61,806

-38,016

11.9%

31.0%

-19.1%

Alaska

5,449

7,502

-2,052

9.5%

13.1%

-3.6%

Arizona

40,530

58,723

-18,193

14.3%

20.7%

-6.4%

Arkansas

30,729

20,447

10,282

25.3%

16.8%

8.5%

California

369,193

236,560

132,633

16.0%

10.2%

5.7%

Colorado

52,003

35,559

16,444

17.0%

11.6%

5.4%

Connecticut

57,697

64,994

-7,296

22.8%

25.7%

-2.9%

Delaware

19,040

6,105

12,935

30.3%

9.7%

20.6%

District of Columbia

26,433

26,551

-118

22.9%

23.0%

-0.1%

Florida

154,353

150,037

4,316

18.4%

17.9%

0.5%

Georgia

79,566

55,473

24,093

16.7%

11.6%

5.1%

Hawaii

7,723

10,706

-2,983

10.0%

13.8%

-3.9%

Idaho

9,224

10,924

-1,700

14.4%

17.1%

-2.7%

Illinois

148,332

70,118

78,215

19.9%

9.4%

10.5%

Indiana

54,607

106,579

-51,973

17.2%

33.5%

-16.4%

Iowa

22,309

19,434

2,875

13.1%

11.4%

1.7%

Kansas

25,897

14,729

11,168

17.6%

10.0%

7.6%

Kentucky

30,128

71,522

-41,394

16.0%

37.9%

-21.9%

Louisiana

43,023

29,411

13,612

17.1%

11.7%

5.4%

Maine

6,902

10,525

-3,624

12.4%

18.8%

-6.5%

Maryland

59,614

62,445

-2,831

17.1%

17.9%

-0.8%

Massachusetts

100,161

68,024

32,137

21.8%

14.8%

7.0%

Michigan

71,184

69,061

2,123

15.8%

15.3%

0.5%

Minnesota

96,227

59,213

37,014

30.4%

18.7%

11.7%

Mississippi

11,011

21,879

-10,867

10.5%

20.9%

-10.4%

Missouri

61,512

44,587

16,925

21.6%

15.7%

5.9%

Montana

5,338

7,248

-1,910

12.1%

16.4%

-4.3%

Nebraska

23,885

11,335

12,550

21.3%

10.1%

11.2%

Nevada

16,579

14,629

1,949

12.6%

11.1%

1.5%

New Hampshire

11,044

8,513

2,531

15.4%

11.9%

3.5%

New Jersey

134,870

55,998

78,872

24.6%

10.2%

14.4%

New Mexico

8,758

21,212

-12,454

9.4%

22.8%

-13.4%

New York

250,618

145,994

104,624

17.8%

10.4%

7.4%

North Carolina

72,472

59,945

12,527

15.0%

12.4%

2.6%

North Dakota

7,585

56,969

-49,384

13.8%

103.3%

-89.6%

Ohio

129,901

73,441

56,460

22.3%

12.6%

9.7%

Oklahoma

32,611

25,341

7,270

17.8%

13.8%

4.0%

Oregon

28,409

28,482

-72

13.2%

13.2%

0.0%

Pennsylvania

126,374

182,015

-55,640

19.1%

27.5%

-8.4%

Rhode Island

13,888

8,373

5,514

25.3%

15.2%

10.0%

South Carolina

22,242

73,069

-50,827

11.7%

38.4%

-26.7%

South Dakota

6,734

6,033

700

14.7%

13.2%

1.5%

Tennessee

56,937

72,691

-15,755

18.9%

24.2%

-5.2%

Texas

265,336

147,338

117,998

16.1%

8.9%

7.2%

Utah

18,389

13,459

4,930

13.0%

9.5%

3.5%

Vermont

4,325

4,688

-363

14.6%

15.8%

-1.2%

Virginia

75,049

92,321

-17,272

16.2%

19.9%

-3.7%

Washington

67,813

51,083

16,730

15.9%

12.0%

3.9%

West Virginia

6,885

14,611

-7,726

9.1%

19.4%

-10.3%

Wisconsin

49,592

78,632

-29,040

16.9%

26.8%

-9.9%

Wyoming

4,892

3,560

1,331

11.1%

8.1%

3.0%

Total

3,047,160

2,649,893

397,267

17.6%

15.3%

2.3%