Morning Report: Inflation returns to the Fed’s target 2/19/16

Markets are lower this morning on no real news. Bonds and MBS are down.

Real Average weekly earnings increased 1.2% in January.

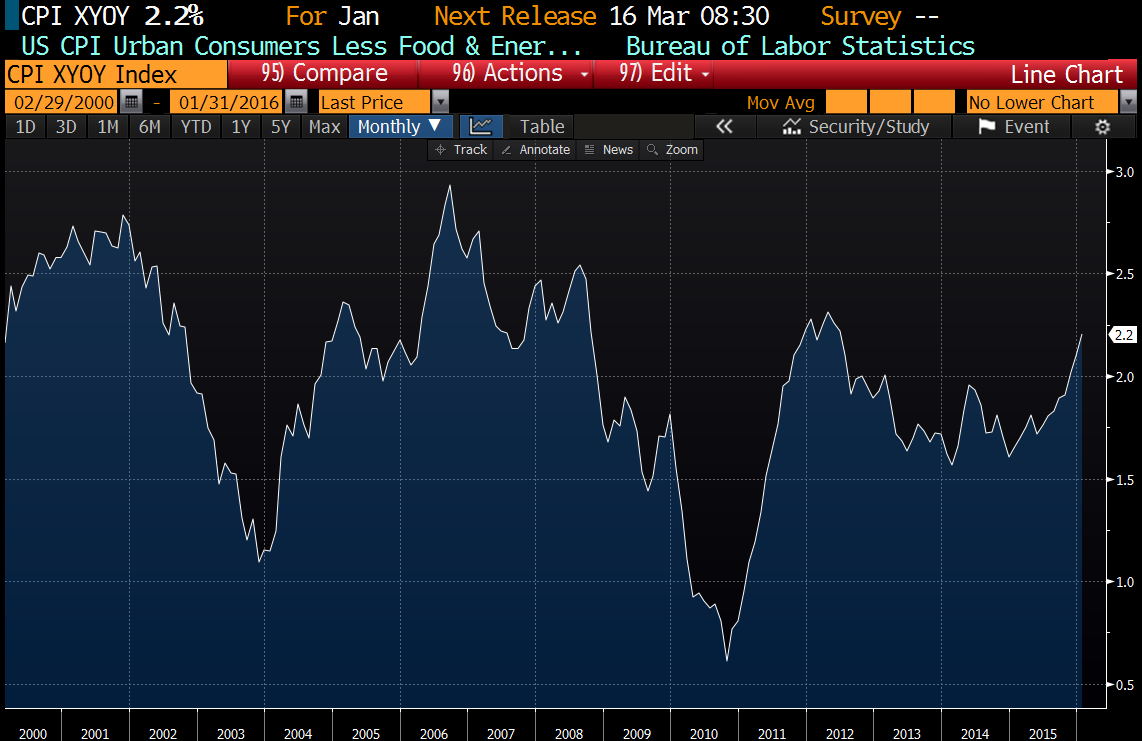
Inflation at the consumer level was flat month-over-month and up 0.3% YOY. Ex food and energy, it was up 2.2%, which is the highest level since June of 2012. This would indicate the Fed is actually getting there as far as its inflation target. That said, the Fed prefers to use the Personal Consumption Expenditure index, which is still below their target.

Chart: YOY inflation, ex-food and energy:
Good explanation of why the markets and the price of oil have become positively correlated. Old timers might remember back when an increasing oil price was a bad thing. Punch line: the banks have a lot of exposure to the energy patch and are lugging debt that made sense at $60 a barrel, but not at $30. That said, energy companies have issued $5 billion in equity secondary offerings this year, which is a surprise. The appetite is there, at least for some investors.

The thinking behind negative interest rates, explained. European economists give their take on it. Basically they work well in smaller. open economies as a lever to manipulate foreign exchange rates, but they aren’t all that effective for larger economies which are trying to boost inflation and growth. In other words, they might work for Denmark, but probably won’t do much good here. Japan recently went negative, so that will be a good test of that theory.

Housing affordability is getting a little better as rates fall. Unsurprisingly, the Rust Belt and the Northeast are the most affordable, while California remains the worst. Note San Francisco is proposing transfer taxes for luxury properties in order to address affordability. Between rich tech workers and Chinese investors, property prices in San Francisco are sky-high.

There is legislation afoot to eliminate the caps on VA loans, which will make them much more popular in high cost areas. Basically it will become a no money down jumbo. It has passed the House, and the prospects are good in the Senate and the WH.

Morning Report: FOMC minutes show Fed is preparing to back off on tightening 2/18/16

Stocks are higher this morning after oil continues its rally. Bonds and MBS are flat

Initial Jobless Claims fell from 269k to 262k., while the Philly Fed improved to -2.8.

The Bloomberg Consumer Comfort Index fell slightly to 44.3 from 44.5 the prior week. The Economic Expectations index fell markedly from 47 to 42.5.

The Index of Leading Economic Indicators improved slightly in January from -0.3% to -0.2%.

Mortgage Delinquencies fell from 4.99% to 4.77% and foreclosures fell from 1.88% to 1.77% in the fourth quarter, according to the MBA.

The FOMC minutes were released yesterday, and for the most part they were a non-event as far as the markets were concerned. The Fed did spend some time talking about the slowdown in China, and the reverberations in the markets. A number of officials are beginning to think the inflation forecasts are too high. In addition, the stresses in the financial system act as a tightening even if rates go nowhere. The Fed seems to be setting the stage for a cut in the GDP and inflation forecasts at the March meeting, as well as a pause in tightening. Separately, the OECD took down its forecast for global growth to 3.0% from 3.3%.

Mortgage REIT MFA Financial reported earnings this morning. They continue to position their portfolio of MBS more towards credit risk and less towards interest rate risk. When the private label securitization market comes back, REITs like MFA will be the big buyers of non-QM paper. Their appetite for non-agency MBS will be the key driver bringing back the widespread use of products that don’t fit in the agency box.

FHFA Chairman Mel Watt says that the GSE’s lack of capital is the most serious risk to the mortgage market right now. He says that guarantee fees have increased 25 basis points since 2009 and they are now “appropriate.” He also said that the current state of conservatorship is “not a desirable end state” and said that the GSE’s protection from market forces “presents itself in multiple decisions, including pricing.”

Morning Report: Neel Kashkari wants to get tougher on the banks 2/17/16

Stocks are higher this morning as yesterday’s rally has follow-through on overseas markets. Bonds and MBS are down.

Mortgage Applications rose 8.2% last week as purchases fell 3.7% and refis rose 16%.

Housing starts came in 1.1 million, missing the 1.17 million estimate. Building Permits were flat at 1.2 million.

The Producer Price Index rose 0.1% in January. The core index (ex food and energy) rose 0.4%. The headline number was up 0.6% YOY and the core number was up 0.8%.

Industrial Production jumped in January by 0.9%, however the preior month was revised lower from -0.4% to -0.7%. Manufacturing Production rose 0.5%. Capacity Utilization improved markedly from 76.4% to 77.1%.

At 2:00 pm, we will get the FOMC minutes. Given the uncertainty around the Fed’s future plans, we could see the market more sensitive to these than usual.

Neel Kashkari of the Minneapolis Fed gave a speech to Brookings yesterday, calling for even more regulation for the banks and to turn them into public utilities. Of course any examination over whether the Fed had a hand in creating the real estate bubble in the first place is nowhere to be found.

The new enemy for consumer direct is not the government – it is a new robot designed to waste a telemarketer’s time.

Morning Report: Markets rebound after a long weekend 2/16/16

Green on the screen as investors return after a long weekend. Bonds and MBS are down small.

The Empire Manufacturing Index improved slightly to -16.64 versus -19.37 in the prior month.

The NAHB Homebuilder Sentiment Index fell to 58 from 61 in February.

Saudi Arabia, Russia, Venezuela and Qatar agreed to freeze production at January levels provided the other members of OPEC agree to go along. Apparently this has been in the works for a while, so oil isn’t having much of a reaction.

Household debt increased 0.4% in the fourth quarter, according to the NY Fed. Student Loan and Auto loan financing are growing the most, while mortgage and HELOC is steady or falling. Credit quality for mortgage debt remains strong, however you can see the increase in low-FICO auto loans (the new subprime). Debt levels below:

As the Spring Selling Season begins, inventory remains tight, especially close to urban areas. The supply of homes is the lowest since 2005.

On Scalia’s replacement, Senate R’s should follow Obama’s lead

Yes, you read that headline correctly. In the wake of the extremely untimely death of Justice Antonin Scalia, I believe that Senate Republicans should follow Barack Obama’s lead when it comes to the next Supreme Court nomination. Specifically they should follow the path laid out by then Senator Obama in a 2005 speech explaining his decision to vote against the nomination of John Roberts. Specifically, Obama said that:

…while adherence to legal precedent and rules of statutory or constitutional construction will dispose of 95 percent of the cases that come before a court, so that both a Scalia and a Ginsburg will arrive at the same place most of the time on those 95 percent of the cases — what matters on the Supreme Court is those 5 percent of cases that are truly difficult. In those cases, adherence to precedent and rules of construction and interpretation will only get you through the 25th mile of the marathon. That last mile can only be determined on the basis of one’s deepest values, one’s core concerns, one’s broader perspectives on how the world works, and the depth and breadth of one’s empathy.

Republicans in the Senate should take that standard to heart and both act and vote accordingly whenever Scalia’s replacement is finally nominated.

To be honest, Obama’s standard for evaluating a judicial nominee has almost nothing to recommend it. It has no basis in the Constitution, nor in historical tradition, nor in the oath that Judges take, nor in any common sense understanding of the role the judiciary can legitimately play in a democracy. Although calling it “Obama’s standard” is not entirely fair. In his speech Obama merely made explicit what had been implicit long before Obama came along, at least since 1987 and the defeat of the nomination of Robert Bork to the Court, and that is that the judiciary is a political branch of the government that makes decisions based on not on the law or the constitution, but rather on the personal values and political philosophy of individual judges.

Again, there is almost nothing to recommend Obama’s approach to nominating and confirming judges. Almost. The only thing that does recommend it is that it is already a reality for roughly half of those involved in the process, including half of those already on the court. Given that reality, R’s have virtually no choice but to play by the same rules. To be sure, embracing those rules is destined to alter the nature of our political system beyond recognition, but R’s must face the fact that it has already started to happen without them, and will continue to happen with or without them. The best they can hope to do is embrace this new system in the hopes of influencing the system towards their own values. The idea of objective law being applied objectively by judges seeking to understand the law on its own terms regardless of personal values is, we must admit, a failed experiment.

A baseball team facing an opponent that not only routinely ignores the written rules of the game but has bought off half of the umpires in its effort to do so has no choice but to follow suit. Republican Senators must establish explicit political litmus tests for potential nominees to the court, and must apply those tests ruthlessly, using all possible political machinations to impose their will. They must, as Senator Obama did, vote only for those nominees to the court which reflect their own “deepest values”, their own “core concerns”, their own world philosophy, their own notion of who deserves “empathy”.

The days of allowing well qualified judges of any political stripe to sit on the court are over. We may lament that fact, but we must accept it nonetheless. The Court is now a political branch of the government, and to treat it as something different is to deny reality. The politics of nominees to the court explicitly matter. R’s must do everything they can to understand the politics of future nominees, and reject any nominee that does not reflect their own conservative values and a conservative understanding of the constitution. In other words, they must take Obama at his word and do exactly what he would have them do. The Democrats asked for this kind of process. R’s should give it to them.

Morning Report: Rates back to pre-taper tantrum levels 2/11/16

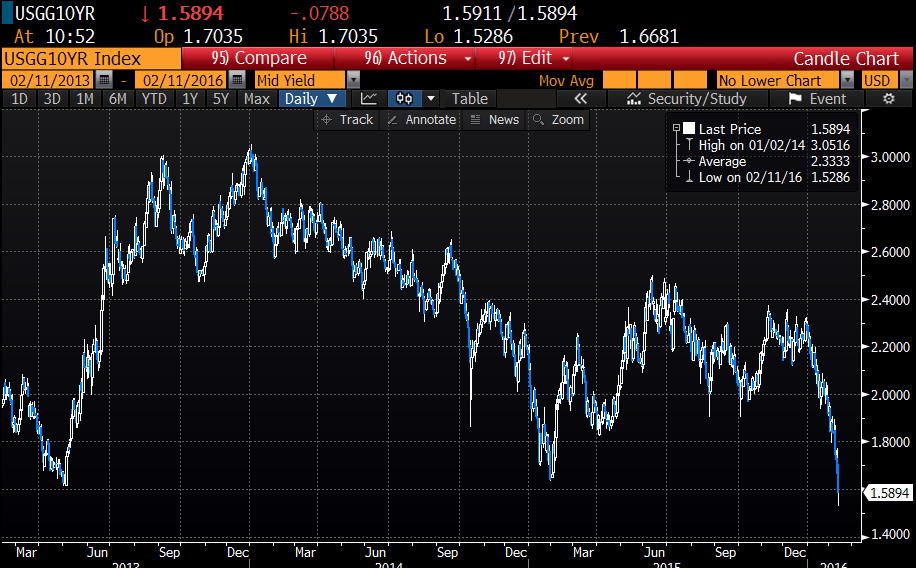
Global stock markets are down again on no real news. Whatever comfort markets took in Janet Yellen’s remarks yesterday are over. Bonds and MBS are up, with the 10 year bond yield pushing a 1.5% handle.

Speaking of Janet Yellen’s plan to continue to increase the Fed Funds rate, the markets are not buying. The Fed Funds Futures contracts are forecasting no rate hikes until 2018.

Loan officers, you have been given an unexpected gift with the 10 year. Rates are now at the pre “taper tantrum” level when the Fed started bracing the markets for the end of QE. So I guess the Fed didn’t need to purchase $4 trillion worth of assets to get rates down?

Initial Jobless Claims fell to 269k from 285k last week. It bears repeating that these numbers are exceptionally good and are associated with boom times. The tape doesn’t care, but still…

The Bloomberg Consumer Comfort Index rose slightly to 44.5 from 44.2 last week. Lower gasoline prices are helping improve the mood.

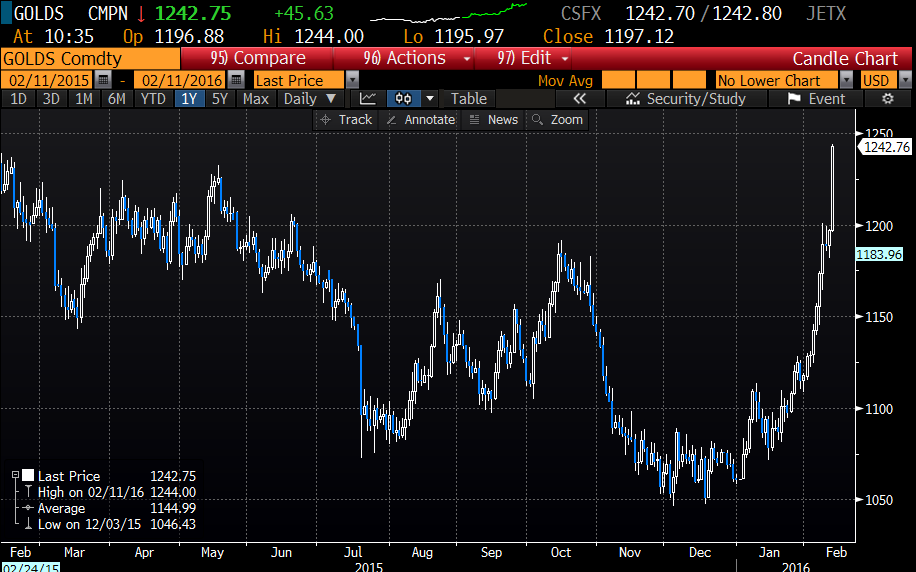
Most commodities have been getting crushed lately, however one has been on a tear: Gold. Gold is a strange animal, in that it is one of the few financial assets that isn’t some else’s liability. The price of gold can be considered to be the (inverse) confidence indicator in the world’s central banks. Gold up, confidence down.

Continuing on the central bank thread, one of the bright spots in the US markets has been auto sales. This has been driven by a couple things: The biggest was that people deferred replacing cars until they absolutely had to due to the lousy economy. However another reason is cheap credit, and some hedge funds think they have found the new “big short” in subprime auto. When you can get an 8 year loan for a new car at a rate below the 30 year fixed rate mortgage, something is awry.

So, yet another pillar holding up the economy was based on cheap credit. Janet Yellen must feel like Michael Corleone: “Just when I thought I was out, they pull me back in.”

The House Financial Services Committee is having a hearing today on FHA MIP. Expect Democrats to push for another cut and Republicans to be against it. The Democrats are in a strange position with the base continuing to push for even tougher regulations for the industry and the affordable housing types getting sick and tired of the tight credit that results.

Morning Report: Yellen calms the markets 2/10/16

Stocks are higher this morning based on prepared testimony for Janet Yellen’s appearance before Congress. Bonds and MBS are down small.

Keep in mind that the Chinese stock market is closed all week in observance of the Chinese New Year, so the biggest catalyst for downside movement in the markets will be absent this week.

Janet Yellen is traveling to the Hill for her Humphrey Hawkins testimony. In her prepared remarks she did spend some time talking about the turmoil in the financial markets and that acknowledgement was soothing enough to stocks to give them a boost. Overall, however the message is that the US economy is improving, and rate are going up gradually. The rest of the testimony will probably be a bunch of ideological questions from various congresscritters trying to get the Chairman of the Fed to agree with their ideological worldview.

Goldman is forecasting 3 rate hikes in 2016. Given the overall weakness in the global economy and the rush to negative interest rates globally, it may not affect long-term interest rates in the US (or mortgage rates for that matter).

Blackrock is forecasting that US growth has probably peaked for the near term as more and more central banks enter the negative interest rate vortex. I wonder what our grandkids will think about today’s PhD standard. If it ends up not working, do we go back to the gold standard?

In New Hampshire, Bernie Sanders won the Democratic primary vote, and Donald Trump won the Republican primary vote. John Kasich had a surprisingly strong showing.

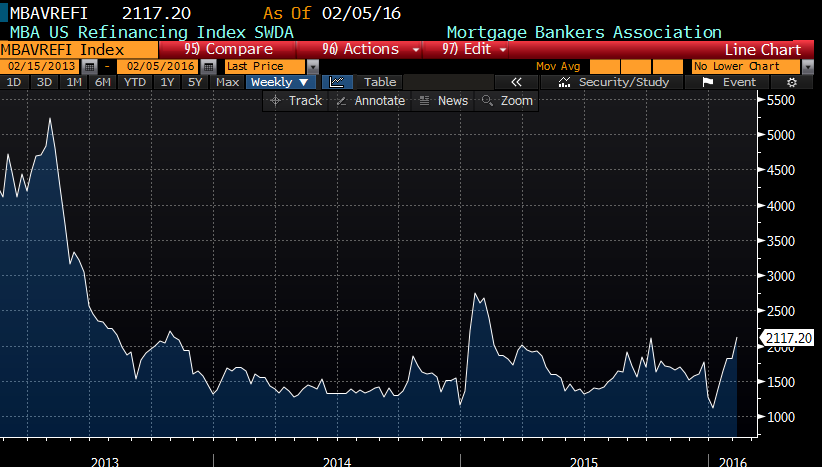
Mortgage Applications rose 9.3% last week as purchases were up 0.2% and refis were up 15.8%. The refi index has had a nice run since rates started collapsing, but we are nowhere where we used to be compared to 2013.

Competition in the jumbo market is fierce, and the typical rate for a jumbo is now 15 basis points below a conforming mortgage. Historically, jumbos have cost an extra 25 basis points to the borrower.

Do you think your underwriters are approving too many shaky loans? Move them to Seattle. Are they too conservative? Move them to San Diego.

Morning Report: Global growth engines are stalling 2/9/16

Markets are down after yesterday’s blood bath. Bonds and MBS are up small.

Since the Fed tightened rates at the December meeting, the 10 year bond yield has fallen by 58 basis points. Fun fact: The Japanese 10 year bond yield is now negative.

In economic data, the NFIB Small Business Optimism Index fell from 95.2 to 93.9 last week. This is surprisingly tame given the activity in the markets over the past couple months. That said, small business optimism didn’t ride the post-2009 rally in the markets up, so it probably will be a little insulated on the way down. Hiring plans remain intact, which is a good sign, however finding qualified applicants continues to be an issue.

Job openings are pushing close to new highs, according to the JOLTS job report. Quits are increasing, which is a bullish sign for the labor markets.

Wholesale sales and inventories both fell in December. We are seeing a buildup in inventory, which is bearish for the economy.

Bottom line: the markets are signalling pain in the global economy, but it is hard to draw the conclusion that conditions in the US are driving it. If anything, the US appears to be taking its historical role of the engine of growth in a soft global economy.

The canary in the coal mine (besides oil) has been the absolute carnage in the banking sector, especially overseas. Deutsche Bank has been cut in half since September. Same as Credit Suisse. Citigroup is down 27% since Jan 1. So is BNP Paribas. Not sure what this is signalling (exposure to energy? exposure to China?) but it is a big warning button for the global economy and it is flashing red.

Even though the economy has recovered, the hatred of the financial sector hasn’t changed, and it is being channeled through Bernie Sanders. The ironic thing is that the “Wall Street” they are railing against hasn’t existed for 10 years. Regardless it isn’t an environment conducive to risk-taking.

Speaking of politics, the New Hampshire Primaries are today. Clinton and Sanders look neck and neck, and Trump looks to be ahead of the pack for the Republicans.

Completed Foreclosures fell to 32,000 in December, which is down 2.4% from November and 22.6% year-over-year.

Super Bowl Rant and Open Thread

I’m watching the pre-game show and naturally CBS cuts to an interview with the Obamas. Sigh. Is there no occasion in this country that can pass without the precious thoughts of a fucking politician being foisted on us?

Newsflash: The president (any president) is a mere politician, not a monarch anointed by the hand of God. We have no need to hear him pontificate on every event, big or small, that takes place in the nation. The guest list for his party is completely unimportant to me. I don’t give a rat’s ass what kind of food he is serving. I couldn’t care less which team he is rooting for. Doubly so for the First Lady, for goodness sake. And I think anyone who does care is a moron.

It is actually quite baffling. The opinion of the ordinary person towards politicians in general is usually one of overwhelming contempt, and rightly so. Yet when a politician is so “good” at all the vile things that politicians do and are that they rise to the highest political office in the country, suddenly we are supposed to wait with bated breath for his sage thoughts on all things big and small. What does he think of the Super Bowl? What does his March Madness bracket look like? What is he saying about the latest tragedy in a small town in the middle of nowhere?

Someone stop the madness, please.

Rant over…open thread.

Planning for Old Age

Anybody have advice/experiences to share in regards to an elderly parent losing their ability to function, yet being entirely uncooperative about doing anything about it?

Right now, we’re struggling to get my dad to the doctor. He doesn’t want to go. We’re trying to get his house to be a little friendlier to his inability to move around, and trying to convince him to put bills on autopay so there’s nothing to forget, and the power won’t get cut off. Again, not very cooperative.

He’s got two dogs he never lets out, and he cleans up after them some if they go to the bathroom in the living room but two of the back rooms were a mess, and we’re going to have the carpets replaced (that in itself will be a challenge . . . his house is very dirty, and crammed with crap). My sister will be putting pee pads down in one of them (already is, and will presumably continue to do so after the carpet is replaced) and is now checking on him daily. He really needs to be in some sort of nursing home, but he is adamant about not having that, and I’m fairly confident all that will accomplish is to kill him quicker. And right now, he’d have to cooperate on that. And he won’t.

My Uncle Don had him doing the accounting for his building company for about 30 years, and now needs information for taxes, and my dad is being uncooperative there as well (and likely does not know where it all is). He has about sixty or seventy baskets in the house (in desk baskets) spread all over the house, filled with all the paperwork from the last few years. Nothing particularly organized. He grows very hostile if someone tries to start going through it, however. Ultimately, I guess that battle will be up to me. Not looking forward to it.

Looking around for an Eldercare lawyer to consult that doesn’t cost an arm and a leg. Also trying to get my ducks in a row as to what sorts of contacts we’ll need. In addition to getting the carpets replaced we just found out he needs a working tub, so we’re likely to replace one of his tubs with a walk-in shower or walk-in tub. Additionally, he could clearly use some strategically placed grab bars. And he definitely needs someone to come in and radically reduce the clutter in the house, but is stubborn about it.

My father at least had the foresight to put my sister’s name on one of his bank accounts, so there’s some access to money (I think the idea was to have money to cover funeral and other related expenses, though, not to provide assisted care, but there should be enough money to cover some of the fixes that have to be made to his house, among other things). But nothing else is planned for. So, good lord, do your children a favor and assume there may come a point where they need a lot of help taking care of you, but you’ll be hostile to letting them, and provide for it. I could do with a list of accounts and bills and necessary numbers and whatnot right now.

My mother, fortunately, is younger, in much better shape, and has planned her estate out to the nth degree. So, I’m likely only going to have to go through this once but still—sheesh, what a pain in the ass.

At some point soon, I need to do a little planning to try and make things easier if I kick off unexpectedly. List of bills and accounts and URLs where I pay them and logins and passwords, that sort of thing. Or I’m going to end up like my dad.

So the lesson is: get your kids set up to take care of your before you start getting dementia!

Any wisdom would be appreciated. Thanks!