Morning Report: Wage inflation is beginning to creep up 2/5/16

Stocks are lower this morning after the jobs report. Bonds and MBS are down

Jobs report data dump:

  • Nonfarm payrolls + 151k vs 190k expected
  • Unemployment rate 4.9%
  • Average Weekly Hours 34.6
  • Average Hourly Earnings up 2.5%
  • Labor force participation rate

Overall a good report, Payrolls are disappointing, but the rest is strong. We are starting to see the beginning of wage inflation with average hourly earnings up 2.5%. December’s number was revised upward from 2.5% to 2.7%. Stocks and bonds are down as this report will keep pressure on the Fed to maintain its posture of normalizing rates. The 2-year yield is higher by 4 basis points.

Higher wage inflation coupled with no inflation equates to lower profit margins. Ironically, this is the sort of “middle class economy” that politicians are promising to bring back. Good for workers, not so much for investors.

The rise in the dollar and the corresponding fall in commodity prices is wreaking havoc on other economies though. Citi is saying fear oilmageddon. This will be felt not only in developing economies like Russia and Brazil, but also developed economies like Canada and Norway. Norway’s “economic miracle” may have simply been a massive leveraged bet on oil and real estate.

Obama proposed slapping a $10 per barrel tax on oil. Obviously that is going nowhere..

1 in 3 houses are still bought with cash, according to CoreLogic. This is a drop of 3 percentage points from a year ago.

Morning Report: Dismal economic numbers this morning 2/4/16

Stocks are lower this morning after we got some disappointing economic data. Bonds and MBS are up small.

Dismal economic numbers all around this morning

Productivity fell 3% in the fourth quarter and unit labor costs rose 4.5%. This is a recipe for falling profits in 2016. Given the tepid GDP growth being forecast for next year (sub 2%), companies will focus most on cost-cutting. Given the excess capacity in the manufacturing economy, companies have been reluctant to spend on capital expenditures, which has depressed productivity. Definitely not a recipe for releasing the animal spirits, although if builders start to address the tight supply, it will provide a good boost for the economy.

Factory orders fell 2.9% in December, which was below the Street estimate. November’s numbers were revised downward as well.

Durable Goods orders fell 5% in December as well. Capital Goods orders (a proxy for capital expenditures by business) fell by 5%. This directly relates to the lousy productivity numbers above.

Announced job cuts increased 41.6%, to over 75,000 according to outplacement firm Challenger and Gray. Most of the cuts are coming in retail and energy.

Initial Jobless Claims rose 285k last week.

The Bloomberg Consumer Comfort Index fell from 44.6 to 44.2 last week.

Don’t underestimate the Fed, which is the message from major strategists. Goldman Sachs Chief Economist Jan Hatzius is calling for a 3% 10 year by the end of the year.

On the other hand, mortgage REIT American Capital Agency is calling for the Fed to abandon its “tightening bias” by the end of 2016. They see a hard landing in China, continued weakness in emerging markets, and undervalued Treasuries versus other benchmark sovereigns.

In a testament to the change occurring in the financial markets, lenders like Quicken and SoFi will be advertising during the Super Bowl this year.

Both Republicans and Democrats agree the economy is lousy, and both sides are going back to their boilerplate explanations. Democrats blame Wall Street and the rich, while Republicans blame government. The funny thing is that the “Wall Street” they rail against hasn’t existed for almost 10 years.

Morning Report: How’s that working for you? 2/3/16

Stocks are higher this morning after oil rebounds overnight. Bonds and MBS are down.

Mortgage Applications fell 2.6% last week as purchases fell 7% and refis rose 0.3%.

The ISM Non-Manufacturing Index fell to 53.5 from 55.8 in January

The ADP Employment Change report came in at 205k. The Street is forecasting 190k in Friday’s jobs report.

Bill Gross’s latest Investment Outlook takes some shots at central bankers, and asks why we think negative interest rates are going to generate growth. As he says “How’s that working for you?” While the consumer has deleveraged over the past 10 years, corporate america has not. That said, corporate america has taken advantage of record-low interest rates to refinance and extend high coupon debt with lower coupon debt. When people are willing to lend you money at 2% for 20 years, why not take it?

Speaking of negative interest rates, it seems the only nation anymore that isn’t playing the beggar thy neighbor devaulation game is the US. Exports are falling, while imports are rising. This is the reason why we are seeing everyone – from Republicans to Democrats – willing to take potshots at free trade. Of course foreigners can accept one of two things in payment for their imports: goods and services from the US or IOUs (Treasuries). So far, they seem to want the IOUs. Which means interest rates are lower than they ultimately would be. Still manufacturing job losses are easy to point to versus interest rates and the benefits of cheaper imports.

Another day, another settlement with the banks: Wells is paying FHA $1.2 billion over “failure to properly review early payment defaults in 2010-2012.” And the government is scratching its head wondering why banks like JP Morgan are reducing / exiting FHA lending… At what point do these constant suits and settlements become simply a surtax on banking?

Refuse to Go Red for Women

According to the American Heart Association, the prevalence of heart disease among men is greater than among women in every age demographic. In the 60-79 age bracket, the prevalence among men is more than twice what it is among women. More than 1.4 times as many men as women have had a diagnosed heart attack or fatal coronary disease across all age groups.

In light of those statistics, it makes perfect sense, of course, that this Friday is Go Red For Women Day, during which the American Heart Association encourages people to wear red in order to “help support educational programs to increase women’s awareness and critical research to discover scientific knowledge about cardiovascular health.”

According to the AHA:

In 2003, the American Heart Association and the National Heart, Lung and Blood Institute took action against a disease that was claiming the lives of nearly 500,000 American women each year – a disease that women weren’t paying attention to. A disease they truly believed, and many still believe to this day, affects more men than women.

Um…it does affect more men than women. It is rather unbelievable that the AHA is attempting to disabuse women of a plain and simple fact.

This is all of a piece with our increasingly female-centric culture which attempts to instruct us that whatever problems exist, they are inevitably worse for women. (Climate change to hit women hardest!) It is bad enough we have to suffer through sports seasons in which players, coaches and officials are pressured to where pink in order to “raise awareness” for breast cancer several times a year. At least women do in fact suffer from breast cancer more than men do, even if the “awareness” of the disease far outweighs its dangers relative to other women-killers. But this is just taking things to an absurd level.

Whatever this says about the AHA in particular or our screwed up society more generally, I highly encourage everyone to refuse to wear red this Friday, to protest this sexist denial of reality. Don’t believe it and don’t accept it. And keep your eye out….if, on Friday, you see more people without red on than with it, know we are winning the battle!

(BTW, I found out about this Red Day foolishness because my HR department, in that cloying way that only HR departments can achieve, sent around a circular encouraging all employees to wear red on Friday. When I presented them with the statistics on heart disease and wondered if they had ever promoted to employees a “men’s awareness” movement of any kind whatsoever, they replied, again in typical HR manner, “We are always looking for volunteers to promote important causes across a wide range of missions.” I’m taking that as a firm “No”.)

Morning Report: Marco and Bernie real winners in Iowa 2/2/16

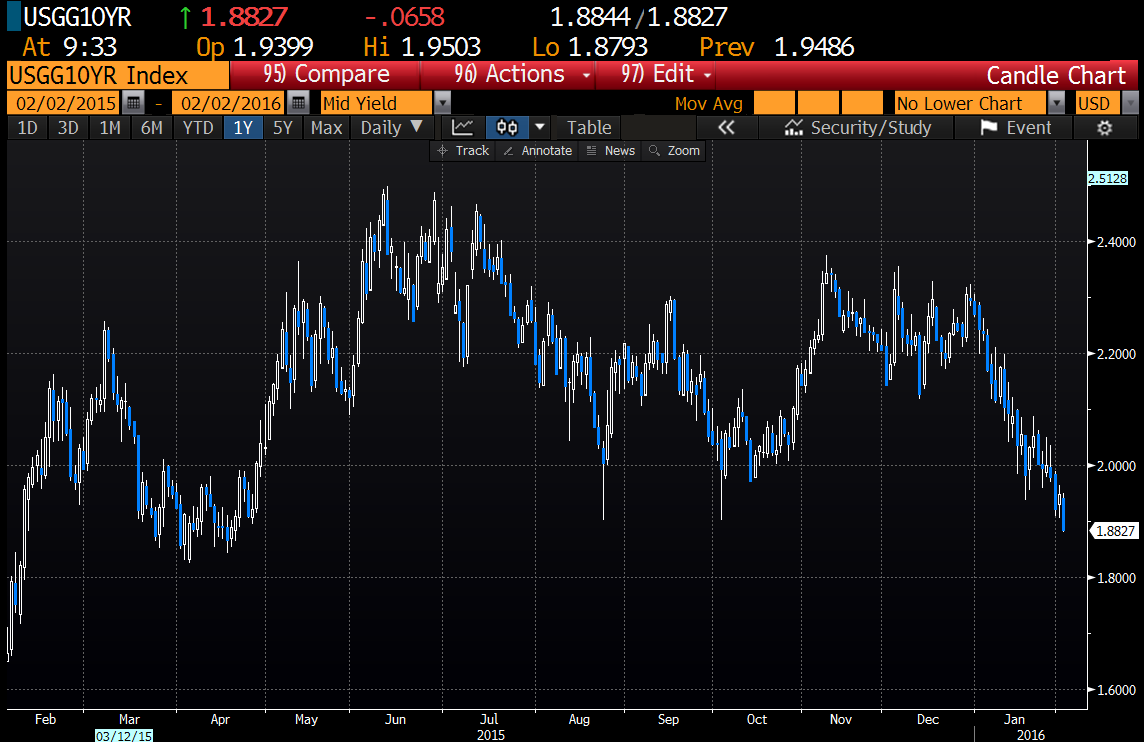
Stocks are getting roughed up a little as overseas markets and oil continue to fall. Bonds and MBS are up sharply, with the 10 year trading just below 1.9%.

The ISM New York Index fell from 62 to 54.6 while the IBD / TIPP Economic Optimism Index ticked up slightly to 47.8.

The winners in Iowa last night were Ted Cruz and Hillary Clinton. Unofficially, the winners were Rubio and Bernie. The losers? Donald Trump and the pollsters who had him in the high 40s. He came nowhere near that. Note that there are allegations of tomfoolery on the Democratic side with vote counting..

The correlation between global stock markets and the price of oil is somewhat strange – historically, high oil prices were considered bad for stocks, not good. While the drop in oil prices is certainly not good news for the big integrated energy companies, it is great news for consumers. Overall, the US benefits from low oil prices. The action in the stock market may be viewing the oil price as the canary in the coal mine for the global economy.

For the time being, the drop in commodities and stocks is keeping a lid on interest rates, which is a good thing for originators. The 10 year is heading back to late winter / early spring of 2015 lows. Fun fact, since the Fed raised the Fed Funds rate on December 16th, the 10 year bond yield has dropped 42 basis points. The trader in me says bond yields have fallen too far too fast.  Loan officers, if you have someone floating, try and lock ’em.  And wake up any potential borrowers who missed out on refinancing the last time around.

Delinquency rates continue to fall, according to Fannie Mae. In December, the seriously delinquent rate fell to 1.55% from 1.58% in November and 1.89% a year ago. Home price appreciation and an improving job market are doing their jobs.

With house price appreciation increasing well in excess of wage inflation, how affordable is housing these days? It depends on the statistic you use. If you look at the median house price versus the median income, you would conclude that housing affordability is approaching the lows of the bubble. However, if you look at the mortgage payment on the median house divided by median income, housing is at pre-bubble levels affordability-wise. Another argument to find people with ARMs and refi them in to 30 year fixed rate mortgages.

Morning Report: Big Week Ahead 2/1/16

Stocks are being weighed down by commodity weakness. Bonds and MBS are down small.

We have a big week of economic data, with the ISM numbers, construction spending, and the jobs report on Friday. Friday’s jobs report will be the highlight of the week.

Personal Income rose 0.3% in December, which was a little better than expected, although that money wasn’t spent. Personal Spending was flat in December, which means the Great American Deleveraging continues to take place.

Inflation remains nowhere to be found, with the PCE Deflator negative in December on a month-over-month basis and up 0.6% YOY. The core PCE was flat in December and up 1.4% YOY.

The ISM Manufacturing Index fell to 52.4 from 52.7 last month, while the ISM Manufacturing Index rose slightly to 48.2 from 48.

Construction Spending rose 0.1% in December after falling 0.6% in November.

Here are Realtor.com’s list of the 20 hottest real estate markets right now. Very California-centric, however some surprises in Stockton, Detroit MI, and Fort Wayne, IN.

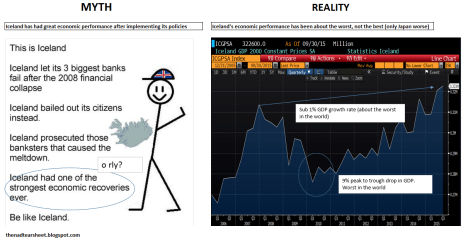
Be like Iceland

Leftist wing truthiness….


Get out the pitchforks all you want, but if the left thinks throwing Jamie Dimon in jail is the path to prosperity, the evidence says otherwise…


Iceland


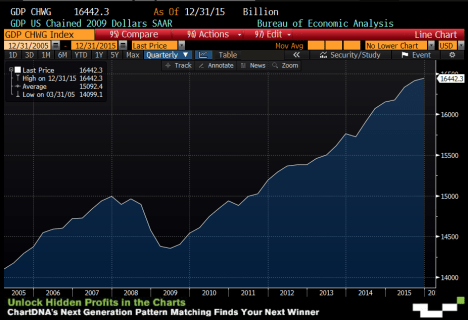
Compare to US growth: (which is still the worse post-WWII recovery on record:


US GDP growth

Morning Report: Bank of Japan to the rescue 1/29/16

Stocks and bonds are higher this morning after the Bank of Japan instituted negative interest rates in an attempt to improve their struggling economy and weaken the yen.

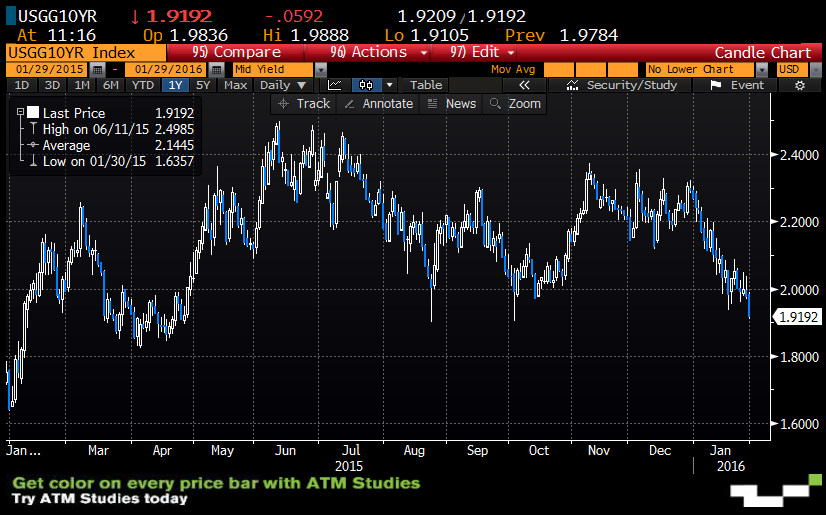
The Bank of Japan’s move caused a worldwide bond rally, which has brought the US 10 year bond solidly below 2%. Mortgage bankers could catch a break here as refi activity will pick up.

We have a lot of economic data this morning

Fourth quarter GDP came in at an anemic 0.7%, missing the Street estimate of 0.8%. The only bright spot of the report was consumption, which increased 2.2%

Inflation remains well-contained with the PCE (the preferred inflation measure of the Fed) increasing at 0.8%, and the core index increasing at 1.2%

The Employment Cost Index rose at 0.6% as wage inflation remains nowhere to be found.

Consumer sentiment slipped in January, while the ISM Milwaukee and Chicago Purchasing Manager Indices increased.

The homeownership rate increased by a tenth of a percent in the fourth quarter to 63.8%. It bottomed in the second quarter at 63.4%. Median asking rent increased 6% from the third quarter to $850. On an annualized basis, it increased 11%.

Household formation dropped to 460,000 in the fourth quarter from 1,447,300 in the third quarter. This almost looks like a data error. If household formation was slowing that much, you wouldn’t see the tight inventory of housing that we have.

Morning Report: The Fed acknowledges risks to the global economy 1/28/16

Markets are flattish after the Fed maintained interest rate levels. Bonds and MBS are flat.

The statement out of the FOMC was relatively dovish, and the key sentence was: “The Committee is closely monitoring global economic and financial developments and is assessing their implications for the labor market and inflation, and for the balance of risks to the outlook.” Stocks initially rallied on the statement and then sold off into the close. Bonds rallied.

Initial Jobless Claims fell from 294k to 278k last week.

Durable Goods orders fell by 5.1%, much more than the Street expectation of -0.7%. Capital Goods orders ex defense / air, a proxy for business capital expenditures, fell 4.3%.

Pending Home Sales rose 0.1% in December and are up 3.1% YOY.

The Kansas City Fed index was unchanged at -9.

Homebuilder PulteGroup reported better than expected earnings this morning. Orders were up 13%, and backlog increased 26%. ASPs increased 6% to $353k. CEO Richard Dugas had this to say about the state of the housing market: “While heightened global economic concerns have created greater market volatility, the positive trends in jobs, demographics and household formations, along with low interest rates and limited housing inventory, support expectations that housing demand continues to move higher at a measured pace for a number of years.” They are seeing weakness in Texas, although Dallas seems to be immune to the drop in energy prices, at least for now.

The CBO estimates that wage growth will outstrip home price appreciation in 2016. They are predicting 3.3% wage inflation and 2.4% home price appreciation. Given the tight inventory levels, I think that home price appreciation estimate is low. Wage inflation has recently crept up from 2% to 2.5%, but I don’t see the catalyst for further wage inflation given the huge reservoir of people who left the labor force for statistical purposes but would gladly take a job if they found one.

Morning Report: New Home Sales highest since 2007 1/27/16

Stocks are lower this morning on lower oil prices and disappointing numbers out of Apple last night. Bonds and MBS are down small.

The FOMC will announce their decision at 2:00 PM EST today. No change in the Fed Funds rate is expected. Bond bulls are going to be looking for a mention of the recent market volatility or oil prices and the path of future inflation. Bond bears will be looking for no mention of oil / volatility and / or language that characterizes these effects as transitory.

New Home Sales increased to 544k in December from 491k the month before. The Spring Selling season is just around the corner. For the full year, new home sales increased 14.6% to 501,000, the highest level since 2007. Interestingly, the median sales price fell 4.3% to $288,900. D.R. Horton’s product mix has mirrored that somewhat, with the Horton Express (starter homes) becoming a bigger share of revenues while Emerald (McMansions) has fallen.

Mortgage Applications rose 8.8% last week as purchases rose 4.6% and refis rose 11.3%.

Weakness in the overall economy depressed sales for Apple. They are seeing it especially in Asia between China and Hong Kong. China is going to be exporting deflation, which is going to make the Fed’s job tougher.