Morning Report: Global Bond sell-off continues 9/12/16

Vital Statistics:

Last Change
S&P Futures 2111.5 -5.0
Eurostoxx Index 340.7 -5.0
Oil (WTI) 44.9 -1.0
US dollar index 86.5 0.3
10 Year Govt Bond Yield 1.68%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.48

Stocks are weaker this morning as global markets continue the sell-off that began on Friday. Bonds and MBS are lower.

Dennis Lockhart is speaking this morning, and said that it is time to have a serious discussion about raising rates. Neel Kashkari and Lael Brainard will be speaking later on today. That should be the end of Fed-speak until the FOMC meeting later this month. Fed Funds futures are now signalling a 60% chance of a rate hike by the end of the year.

So far it appears that mortgage rates are lagging the move up in sovereign yields. The same thing happened after the taper tantrum in 2013. The 10 year bottomed in spring, while mortgage rates kept falling and didn’t start rising until fall.

Donald Trump went after Janet Yellen and monetary policy, accusing the Fed of being political to protect Obama’s legacy. FWIW, it seems like there is a change in the consensus over ZIRP and whether it is causing more problems than it is solving. Not too long ago, such comments would have been treated with “How dare you!” kvetching by the press.

Certainly you are seeing the change in consensus overseas, as foreign bond markets have been selling off over the past week, with the German Bund now trading with a positive yield. Even the Japanese bond market is heading lower. Deutsche Bank lays out the scenarios going forward.

The chart below (courtesy of Deutsche Bank) looks at overvaluation / undervaluation of various asset classes over a two centuries. Bonds are extremely overvalued (we know that already), but ZIRP has also caused overvaluation in stocks and real estate, which should unwind as rates start going up. Best case scenario: a situation like the post WWII era where rates gradually crept up over the course of a few decades. Of course currencies were linked to gold back then.. Today, we are on the PhD standard where the value of paper is based on the relative value of other paper.
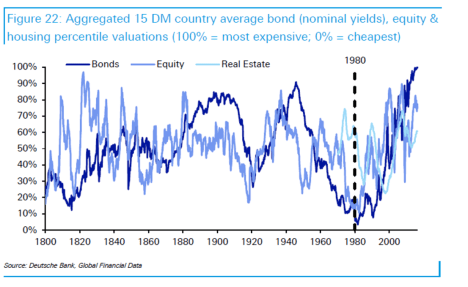
asset-overvaluation

It is almost as if global bond markets jumped the shark last week when Sanofi and Henkel were able to issue corporate debt at negative yields.

Morning Report: Ratio of job openings to unemployed back to pre-recession levels 9/9/16

Vital Statistics:

Last Change
S&P Futures 2159.0 -12.0
Eurostoxx Index 347.1 -2.0
Oil (WTI) 46.7 -0.9
US dollar index 86.4 0.3
10 Year Govt Bond Yield 1.65%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.52

Stocks are lower as emerging markets sell off. Bonds and MBS are down.

Risk-off feel today, but bonds aren’t rallying. What is going on? Global bond yields are increasing, especially in Japan where the BOJ is taking a breather purchasing bonds. The German Bund is down as well. Some strategists are beginning to sense that the Japanese bond market could be headed lower. So, despite weak US economic data, a global bond sell-off will affect US Treasuries as well.

Boston Fed President Eric Rosengren is sounding hawkish, which is not his natural home. His argument is that a campaign of slow, steady rate hikes will prolong the expansion more than waiting and then having to move more aggressively. Of course it all comes down to wage growth, which decelerated in the last jobs report.

Barry Ritholz took a look at the the lack of wage growth and comes up with an interesting chart: the ratio of the unemployed to the number of job openings. This ratio is back down to pre-crisis levels. While we have yet to see much evidence of increased turnover in the quits rate, it does appear at least anecdotally that we are seeing more turnover. Certainly the stage is set for further wage inflation.

jolts-to-unemployed

Mortgage credit tightened slightly in August, according to the MBA. Apparently, one investor is exiting the correspondent business and that accounted for the tightening. Credit is easing in the jumbo space however.

Morning Report: Consumers are getting more constructive 9/8/16 on the economy

Vital Statistics:

Last Change
S&P Futures 2186.5 2.0
Eurostoxx Index 350.5 1.0
Oil (WTI) 46.4 0.9
US dollar index 85.7 -0.1
10 Year Govt Bond Yield 1.54%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.52

Stocks are higher after the ECB left rates unchanged. Bonds and MBS are flat.

Initial Jobless Claims came in at 259k, We have been below 300k (an important level) for 80 weeks now.

Consumer comfort increased to 44 last week, according to Bloomberg.

Wage inflation is evident only in certain pockets of the labor economy – tech workers, engineers, construction, and remains flattish in the less skilled sectors. Elsewhere, hours are being cut and we are seeing full-timers being relegated to part-time. Until we start seeing broad-based wage inflation, the Fed is going to move slow. Note there is a disconnect between the Fed heads and what the markets are saying regarding near-term rate hikes. The markets aren’t buying the hawkish language.

Consumers are getting somewhat more constructive on the economy, according to Fannie Mae. The number of people who think the economy is on the right track improved to 38% and the number of people who think the economy is on the wrong track fell to 52%. Given the weak data recently that could be a temporary blip.

Morning Report: European companies get paid to borrow 9/7/16

Vital Statistics:

Last Change
S&P Futures 2183.0 -2.0
Eurostoxx Index 350.1 0.7
Oil (WTI) 44.9 0.1
US dollar index 85.7 0.1
10 Year Govt Bond Yield 1.52%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.5

Markets are flattish on no real news. Bonds and MBS are up small.

Mortgage Applications rose 1% last week as purchases and refis rose the same amount.

Job openings hit a record 5.9 million in July, according to the JOLTS data. The quits rate, which is the best indicator of economic strength inched up to 2.1% which was the typical level pre-recession. Note the JOLTS data is older than the more recent employment data, however it continues to indicate either strength in the labor market, or a mismatch of skills. Job openings in construction are about the same level as the go-go years of 2005 – 2007.

Same store sales increased 0.8% last month, which was the strongest showing since May. This is the back-to-school shopping season, which is the second most important period for retailers.

There is no doubt that the latest economic data has pointed towards a deceleration of growth. The ISM report from yesterday was the worst in 6 years. Still some strategists see the chance of a September move – Goldman’s Jan Hatzius just took down his probability of a Sep hike from 55% to 40% (still pretty high). Given the non-existent inflationary picture, it is hard to make a case that the Fed needs to hike rates now.

Second quarter originations were the highest since 2013, right before the “taper tantrum” killed the refi market, according to Black Knight Financial Services. Total first lien originations were 512 billion, of which 58% were refis.

Distressed sales are falling as a percent of home sales, and the discounts appear to be narrowing slightly. The biggest discounts are still in the judicial states where foreclosures sit and depreciate during the elongated timelines. Compare New York’s 40% with Texas’s 14%.

Aside from raising the Fed Funds rate, the next shoe to drop with the Fed will be dealing with the assets it purchased during quantitative easing. Pre-2008, the Fed’s balance sheet stood at something like $800 billion in assets. Today, it is about $4.5 trillion. The Fed intends to eventually return its balance sheet to pre-2008 levels. Ben Bernanke argues that the Fed should maintain its balance sheet at current levels for the long term.

File under “things that will astonish people some day:” In Europe, you are starting to see negative yields in the corporate bond sector. Yesterday, Germany’s Henkel and French pharma giant Sanofi sold 1.5 billion euros of 0% corporate bonds above par. Astonishing that people would pay to take credit risk and interest rate risk, but there you go.  With the ECB buying corporate bonds as well as sovereigns maybe the thought is that they will flip them to the ECB a couple of basis points higher? I don’t know. IMO, this is the equivalent of buying eToys at 40x revenues of iVillage at 2x pageviews in the hopes that the daytraders will ramp them so you can exit.

Morning Report: Jobs report disappoints 9/6/16

Vital Statistics:

Last Change
S&P Futures 2180.0 2.0
Eurostoxx Index 351.0 0.3
Oil (WTI) 44.2 -0.2
US dollar index 86.5 -0.2
10 Year Govt Bond Yield 1.59%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.5

Markets are slightly higher this morning on no major news. Bonds and MBS are flat.

Jobs report data dump:

  • Nonfarm payrolls + 151k vs 175k expected
  • Unemployment rate 4.9% vs 4.8% expected
  • Labor force participation rate 62.8% flat
  • Average hourly earnings +0.1% vs. 0.2% expected
  • Average weekly hours 34.3 versus 34.5 expected

Overall, not a report that should move the needle for the Fed, especially with respect to the September meeting. Bonds initially rallied on the report, but sold off during the rest of the day. The key numbers (the disappointing hourly earnings and average weekly hours) point to the Fed standing pat in September.

The ISM Non-Manufacturing missed expectations by a country mile, falling to 51.4 versus expectations of 55. Growth is still positive (since the number is above 50), but growth took a big step back.

The Labor Market Conditions Index slipped to -0.7 in August.

Lack of construction workers are a drag on housing, according to Freddie Mac. About 30% of the construction workers from 10 years ago found jobs in other fields. There are about 200,000 unfilled construction jobs in the US at the moment, and the ratio of job openings to hiring is the highest since 2007. The number of open jobs has increased 81% over the past two years.

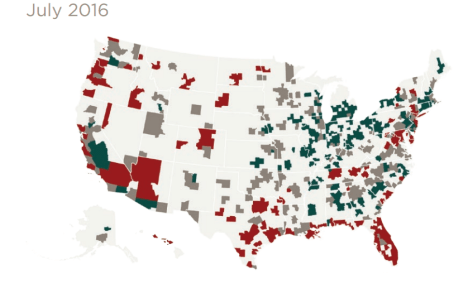
Home prices rose 6% YOY in July, according to CoreLogic. Home price appreciation continues its torrid pace out West, while the Northeast and Midwest lag. We are beginning to see overvalued markets especially out west. Here is a map of the overvalued (red) and undervalued (green) markets:

corelogic MSAs

Delinquencies ticked up in July, according to the Black Knight Financial Services Mortgage Monitor. Part of that was technical, with the month ending on a Sunday. Foreclosures and foreclosure inventory continue to work their way downwards.

What are the markets thinking about the Hillary versus Trump match up? While the US has some betting markets, the UK has a very liquid market in betting. You can track the markets here, at Sporting Index. The current markets are here:

sporting index markets Hillary and Trump

The original bets pre-dated the conventions, so the payout is 25 if the person gets the party nomination and 50 if they win. Based on these markets the implied probability of the election is 72% Clinton, 28% Trump. FWIW, in the US-based PredictIt markets, Trump costs 37 cents and Hillary costs 64 cents…

Afternoon Report – 9/1/16

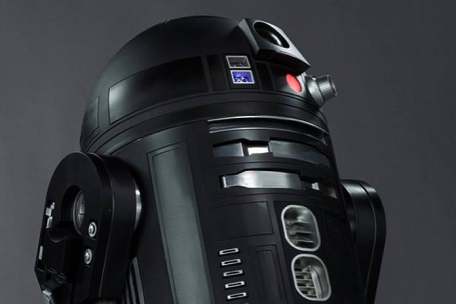
rogue-one-features-a-black-sexy-R2-like-droid

R2-D2 is joining the Dark Side for Rogue One. Not really, but it sure looks like a black R2-D2.

It’s good to be the King. Or an ex-king. Apparently, money allotted by the Former President’s Act (a program created largely after the time when a president’ dying in penury was actually a potential problem) has been used to pay salaries and benefits to Clinton aides.

But even as the Clintons got rich and grew their foundation into a $2 billion organization credited with major victories in the fights against childhood obesity and AIDS — while paying six-figure salaries to top aides — Bill Clinton continued drawing more cash from the Former President’s Act than any other ex-president, according to a POLITICO analysis. The analysis also found that Clinton’s representatives, between 2001, when the Clintons left the White House, and the end of this year, had requested allocations under the Act totaling $16 million. That’s more than any of the other living former presidents — Jimmy Carter, George H. W. Bush and George W. Bush — requested during that span.

Well, isn’t that special?

Mel Brook’s “It’s Good to be the King Rap” ended up with Mel Brooks being the first white artist to land a rap song on the R&B charts.

…

Life gets a little more like cautionary science fiction every day: Scientist’s Using Light to Reprogram Brains.

French police make woman wearing too many clothes take some off at the beach. Well, that’s one way to belatedly deal with their immigration policies. Probably not the best one.

Trump went to Mexico. Not exactly Nixon in China, but, you know, it happened.

I want to unload my dad’s house. Anybody got any warnings or useful info regarding HomeVestors and We Buy Ugly Houses?

The UK is working on how to extract itself from the EU (or maybe not), but as to how it’s going to extract itself from the caliphate is another story entirely.

An oldy-but-a-goody: Tear gas in parliament. An average day of politics in Kosovo.

So what’s up with you?

Evening Report 8/30/16

Syracuse, ostensibly an FBS football program in a P5 conference, opens against Colgate, an FCS team.

Michigan State, not to be outdone, opens against Furman, which may be in a lower division than even Colgate.

There are some good games scheduled this weekend – real intersectional clashes. ‘Bama is playing USC in Jerryworld. K St. goes to Stanford. UT plays ND Sunday night. Oklahoma is at UH; not a true old fashioned intersectional game, but it does pit preseason #3 against preseason #15. UNC v. UGA, Mizzou at WVa and LSU traveling to Lambeau to play Wiscy round out the potentially good games, I think, except for this one.  UCLA is traveling to College Station to play the benighted Aggies.  Here is UCLA’s take on Aggie “traditions”:

http://www.bruinsnation.com/2016/8/28/12685880/a-bruin-field-guide-to-game-day-strangeness-in-college-station?_ga=1.233849438.1963087941.1472559008

In other news, Turkey needs the west and the west needs Turkey, according to this article:

http://www.economist.com/news/leaders/21705828-how-manage-relations-natos-most-awkward-member-dont-lose-plot

The EC wants to fine Apple more than a billion Euros for something.

https://espresso.economist.com/5133aa1d673894d5a05b9d83809b9dbe

What Texas state employees earn:

https://salaries.texastribune.org/

And piston engine airplanes are the last major source of lead in the atmosphere.

http://news.mit.edu/2016/unfriendly-skies-piston-engine-aircraft-pose-significant-health-threat-0826


Morning Report: Janet Yellen speaks at 10:00 am EST 8/26/16

Vital Statistics:

Last Change
S&P Futures 2173.0 0.0
Eurostoxx Index 342.0 0.0
Oil (WTI) 47.4 0.1
US dollar index 85.6 0.1
10 Year Govt Bond Yield 1.56%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.5

Markets are in a holding pattern ahead of Janet Yellen’s speech in Jackson Hole today. Bonds and MBS are flat

Janet Yellen will give a speech today at 10:00 am, discussing the tools in the Fed’s monetary policy toolkit. Speeches at Jackson Hole are generally not market-moving, however the markets have been adjusting ahead of this one. Expect to hear Yellen push for fiscal policy to improve the economy.

The markets are now assigning a 33% chance of a rate hike in September. Somewhat hawkish Fed-speak out of different Fed heads largely accounts for the increase. The Fed Funds futures markets are also assigning a 58% chance of a hike through December.

Fed funds probability.PNG

GDP came in at 1.1% in the second quarter, which was a downward revision from the first estimate of 1.2%. The price index was up 2.3% on a year-over-year basis, which was a little hotter than expected.

Corporate profits fell 2.2% in the second quarter. Tough to reconcile a near-record stock market with falling profits. Something has to give.

corporate profits

For all the talk in Washington about the need for more infrastructure spending, states are beginning to take advantage of low interest rates to issue bonds to raise money for infrastructure spending. When municipalities can borrow money for 30 years at 2.23%, it is kind of a no-brainer. Both Donald Trump and Hillary Clinton are talking about increasing infrastructure spending, so it looks like we will probably have something out of DC next year as well.

Morning Report: New home sales rise 8/24/16

Vital Statistics:

Last Change
S&P Futures 2186.0 1.0
Eurostoxx Index 345.6 2.0
Oil (WTI) 46.8 -1.7
US dollar index 85.8 0.1
10 Year Govt Bond Yield 1.55%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.5

Stocks are flattish this morning on no real news. Bonds and MBS are flat as well.

Bonds have been in a tight trading range over the past couple of weeks. On Friday, Janet Yellen will speak in Jackson Hole.

Existing home sales dropped 3% YOY in July as tight inventory remains an issue. The median home price increased 5.3% YOY to 244k. Unsold inventory is at 4.7 months, an uptick from June. The first time homebuyer accounted for 32% of sales compared to 28% last year. Appraisal-related issues are increasing as demand is overwhelming the already reduced supply of appraisers.

New home sales increased over 12% in July to a 654,000 annual rate. The median home price fell 5.1% month-over-month to $294,600. The median home price is down about half a percent YOY. Softness in the luxury space might be driving this as well as a move to focus more on starter homes. Supply is still tight at about 4.3 month’s worth so you can’t say it is a glut. Regardless of what is going on in pricing, the number is an encouraging sign for the economy.

You aren’t seeing softness in pricing at Toll Brothers. Their ASPs rose 16% in the third quarter YOY. Toll has been emphasizing luxury urban condo construction, which may explain part of the huge increase. Revenues increased 24% and net income rose 54%. Yet what are they doing with their capital? Buying back stock, to the tune of $97 million worth in the third quarter. If business is that good, why?

Mortgage Applications fell 2.1% last week as purchases fell .3% and refis fell 3%.

The FHFA House Price Index rose 0.2% MOM and is up 5.6% YOY. Home prices rose in every state except for Vermont. The Pacific Northwest and mountain states had the highest price appreciation, while the Northeast and Mid Atlantic continue to bring up the rear. In fact, the worst MSA was the Stamford-Bridgeport MSA which saw prices decline 3%. The FHFA index only looks at houses with a conforming mortgage, so it excludes jumbos and cash sales.

McMansions are not holding their resale value the way they used to. This may help explain the drop in the median sales price for new homes. The premiums are lower for new houses.

There is an old saying that if you spend some time on a website and can’t figure out what the product is, you are the product. This is especially true with Facebook. Ever wonder how facebook classifies you politically? You can find out here. This determines the political ads you see.

Morning Report: Donald Trump was a mortgage broker 8/22/16

Vital Statistics:

Last Change
S&P Futures 2179.0 -3.0
Eurostoxx Index 340.7 -0.1
Oil (WTI) 47.8 -1.0
US dollar index 85.7 0.2
10 Year Govt Bond Yield 1.56%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.5


Stocks are slightly lower this morning after Stanley Fischer said the US economy was close to hitting all of the Fed’s targets. Bonds and MBS are down small.
Not a lot of market-moving data this week, aside form the second revision to GDP on Friday. Note central bankers will be out in Jackson Hole this week, so there is the possibility of comments moving the markets. Otherwise, it looks to be a dull week in late August.
The Chicago Fed National Activity Index came in better than expected at .27, but the 3 month moving average is negative, indicating the economy is growing slightly below trend.

Fannie Mae is forecasting the Fed will maintain rates throughout 2016, and they believe the economy will strengthen. “Second quarter growth was a disappointment, but consumer spending appears solid heading into Q3, and we expect inventory investment to balance out after a surprising drawdown in Q2,” said Fannie Mae Chief Economist Doug Duncan. “Credit expansion, combined with improving labor market conditions and strengthening household balance sheets, should continue to support consumers, who will likely be the primary driver of growth again in the second half of the year. The positive July jobs report may encourage some Federal Open Market Committee members to argue for a Fed rate hike at the September meeting. However, we remain convinced that the Fed will hold the target rate steady this year given global uncertainties and anemic output growth. Although much of the financial volatility from Brexit has subsided, long-term Treasury yields continue to face downward pressure and we expect them to remain low for some time.”

More from Fannie on the housing market: “Housing market fundamentals remain a mixed bag. During the second quarter of 2016, both new and existing home sales rose to expansion highs, while single-family starts pulled back, remaining historically low for an expansion,” said Duncan. “Tight housing inventory from a lack of new construction continues to create affordability challenges, particularly at the lower end of the market. Robust rental demand during the second quarter of the year has created the lowest rental vacancy rate in decades. In addition, the homeownership rate dropped to below 63 percent in the second quarter, but we are seeing some tentative signs of older Millennials moving toward homeownership. We expect homebuyers will benefit from improving job and wage growth, more favorable lending standards, and continued low mortgage rates through the rest of the year, with the 30-year fixed-rate mortgage rate projected to average 3.4 percent during the fourth quarter.”

Talk about bad timing: Donald Trump got into the mortgage business in 2006. He did make an interesting point about bubbles and the madness of crowds. “Are you the type of person who takes advantage of positive situations when they present themselves, riding them out as long as they last? Or do you heed every message of doom and gloom, avoiding risks that could be some remarkable opportunities?” If you sold stocks in 1996 when Alan Greenspan discussed “irrational exuberance” in the stock market, you missed out on the lion’s share of the growth. Also, the most money is made right at the end of the move when it goes parabolic.
Following on Donald Trump, many recognize we have a bubble in sovereign debt. Black Rock believes that supply-demand imbalances will keep the bubble inflated for the near term. Meanwhile, Paul Singer suggests that bonds come with a warning label: “Hold such instruments at your own risk; danger of serious injury or death to your capital!”
Note that the European Central Bank and the Bank of Japan are now buying private placements from corporate issuers.  I guess the big question is “what happens when these bond issues go bad?” The European Central Bank is supporting 3.3 trillion euros of assets on 100 billion euros of capital, or about a 32:1 leverage ratio. The Fed is even worse, supporting $4.5 trillion in assets on just $40 billion worth of capital for a 112:1 leverage ratio. It won’t take much of a move in asset prices to wipe out the equity of either entity.