

PLACEHOLDER FOR BRENT. BRENT, PLEASE EDIT.
The rest of you can use it as an open thread, or not.
Filed under: Morning Report | 19 Comments »
PLACEHOLDER FOR BRENT. BRENT, PLEASE EDIT.
The rest of you can use it as an open thread, or not.
Filed under: Morning Report | 19 Comments »
Stocks are lower this morning after yesterday’s bloodbath. Bonds and MBS are up.
The jobs report came in weaker than expected. Payrolls increased by 209,000, and the two-month payroll revision was +15,000. The unemployment rate ticked up to 6.2% and the labor force participation rate rose to 62.9% from 62.8%. However hourly earnings were flat and average weekly hours were flat as well. The lack of wage pressure cheered the bond market, which is clawing back yesterday’s losses. FWIW, the employment cost index showed a .8% increase in wages yesterday (benefits are calculated separately), so the lack of wage growth as reported by BLS is surprising.
By the way, for the bond market to start worrying about wage inflation, you will need to see increases in average wages of about 4%, not the 2% inflation target. Why? Productivitiy, which is running about 2% (notwithstanding the lousy print in Q1). Wage inflation that is offset by productivity increases is not inflationary. So, when you think about the US needing 4% wage growth just to get to the Fed’s inflation target, you can see we have a long way to go.
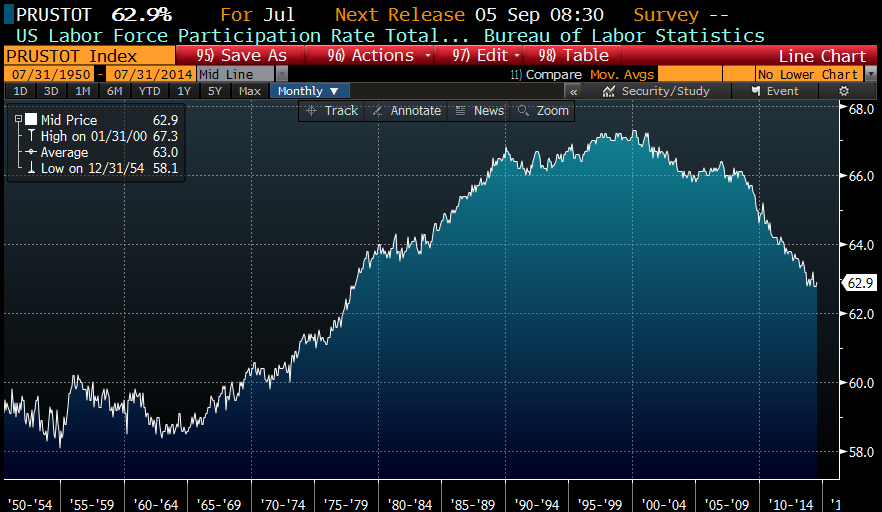
Still, we aren’t going to see a robust economy until the labor force participation rate gets back to normal levels. As you can see from the chart below, about half of the increase in the labor force participation rate that was attributable to women entering the workforce starting in the 1960s has been given back. That low number represents excess capacity that isn’t being captured with the headline unemployment number. Which is why wage growth is so hard to come by (the other reason being technology).
Personal Spending rose .4% in June, and Personal Income rose .4% as well. The core personal consumption expenditure index rose 1.5% year-over-year, still below the 2% target the Fed would like to see.
The ISM numbers came in stronger than expected, showing that manufacturing continues to do well, A 57.1 number would correspond to GDP growth of 4.6%. Of course manufacturing doesn’t dominate the economy (and employ people) like it used to, but it is still a good, strong number.
Finally, construction spending slipped 1.8% in June after increasing an upwardly-revised .8% in May. Resi construction fell .2% month-over-month but is up 7.1% year-over-year.
Filed under: Morning Report | 32 Comments »
Markets are higher this morning on a strong GDP numbers. Bonds and MBS are selling off.
We will get the FOMC rate decision this afternoon. Since there are no economic forecast revisions and no press conference, I expect it to be a non-event with an announcement of another decrease in asset purchases and no change in interest rates. The interesting stuff probably won’t make it into the press release and we will have to wait for the minutes.
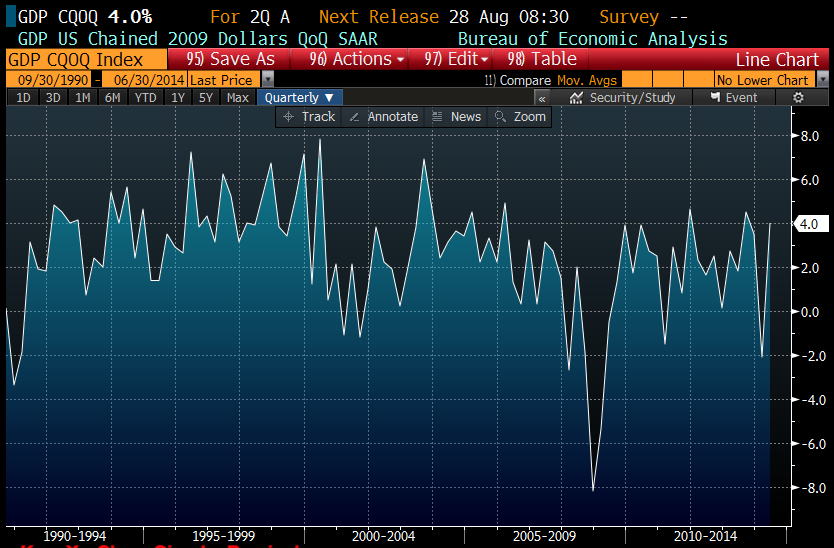
The advance estimate for second quarter GDP came in at 4%, a strong rebound from the revised -2.1% pace in Q1. The Street was at 3%. People were expecting a strong Q2 number as the first quarter number was depressed due to the weather and activity undoubtedly was pushed into Q2. Personal consumption came in at 2.5%, again a better than expected number. I would caution that the advance estimates of GDP have been WAY off lately – the advance estimate for the first quarter was +0.1% and the final number was -2.9% (subsequently revised up to -2.1% as the government made some baseline adjustments). Inflation came in at 2%..
The internals for the GDP number: big jump in consumption, especially durable goods and autos. Not surprising – the average age of a car in the US is something like 11.4 years, which is a record. Gross private domestic investment (in other words capital expenditures) rose by a lot. My suspicion is that was weather-driven. Government spending increased as well. Overall, the strong number should not have been a surprise given the strong data we have been seeing lately
Chart: GDP QOQ growth 1990 – 2014
The ADP payroll number came in weaker than expected: 218k versus 230k. The Street is at 231k for Friday’s payroll number. Note that ADP uses a model to predict the number while BLS uses a sampling methodology. ADP’s number is designed to match the final BLS number, not the initial one, though it has been pretty spot-on the last couple months.
This strong economic data does kind of beg the question of whether the Fed is getting behind the curve. QE will probably end sometime this fall, but the Fed could find itself by the end of the year substantially at its inflation and unemployment targets, with rates still at zero percent and a balance sheet four times the size it should be. I think the Fed is fine with erring of the side of caution and doesn’t want to make the mistake the Bank of Japan did and tighten before the economy was hitting on all cylinders. I think the Fed will probably hold rates at or close to zero until we start seeing wage inflation. That will be the tell, IMO.
Mortgage Applications fell 2.2% last week as purchases rose .2% and refis fell 4%. Bonds were flat last week, and MBA has the average 30 year fixed rate mortgage flat at 4.33%, while Bankrate had it increasing from 4.27% to 4.33%.
Filed under: Morning Report | 15 Comments »
Markets are higher this morning as earnings reports continue to come in. Bonds and MBS are up as well.
Consumer Confidence improved dramatically in June, according to the Conference Board. The present situation index rose from 86.3 to 88.3, but the expectations index rose from 86.4 to 92.7. In other words, the increase is being driven more by expectations of the future, which may or may not come to pass. Consumer confidence is back to October 2007 levels, where the first indications of the financial crisis were beginning to be felt. This was the beginning of the buyer’s strike where the big buyers of structured product were saying no mas and banks were beginning to lug paper they couldn’t move.
The S&P Case-Shiller index dropped 31 basis points in month-over-month in May, but is still up 9.34% on an annual basis. This is the seasonally-adjusted number. The non-seasonally adjusted number rose 1.1%. This is the first month-over-month drop since real estate bottomed in early 2012. Prices are back to summer 2004 levels. San Francisco, Tampa, and Chicago led the way with price appreciation.

Mortgage REIT giant American Capital Agency reported good second quarter numbers. They reduced their leverage by shrinking their balance sheet, which is a bearish signal on MBS. Of course everyone knows rates are going up, but you don’t want to lighten your exposure until it is imminent. Interestingly, they cite the favorable supply / demand relationship with MBS, which seems to be unaffected by the Fed’s tapering. This speaks to how lousy origination volumes have been this year.
Will the Zillow / Trulia merger do to real estate brokers what Expedia did to travel agents? That is the fear of many, although Zillow adamantly denies that is where it is going. “We sell ads, not houses.” said Spencer Rascoff, CEO of Zillow. That may be true, but given the sheer size of broker commissions, it is probably inevitable that technology will cut in on their business model. Still, this is a merger of #1 and #2 and it could get blocked on antitrust grounds. If the NAR pushes the regulators to block the deal, it might be curtains. FWIW, the risk arbitrage community thinks this one is a long shot, with the arbitrage spread trading at 9.25% gross. This is very, very wide. On a back of the envelope basis, it looks like arbs are giving this one a 1 in 3 chance of blowing up.
Filed under: Morning Report | 29 Comments »
Markets are higher this morning on overseas strength. Bonds and MBS are down.
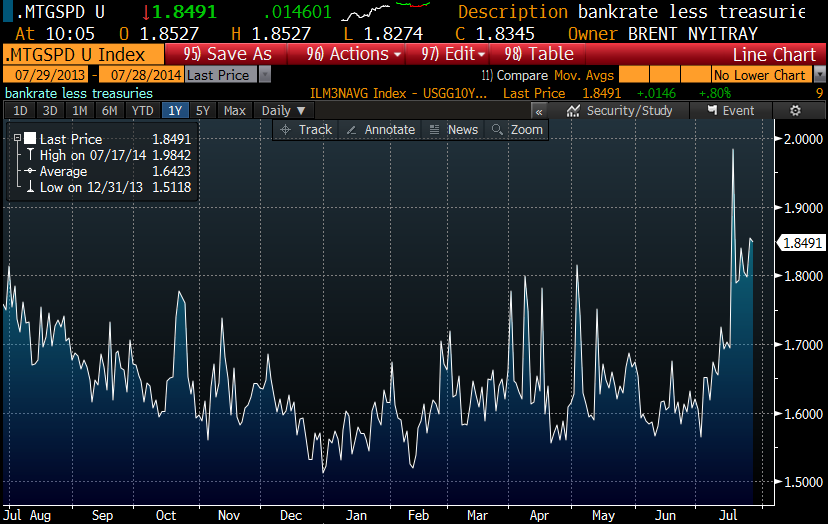
Pending Home Sales fell 1.1% month over month in June, a sign that the real estate market continues to struggle to get up off the mat in many areas of the country. Limited credit and wage growth continue to be issues. That said, mortgage rates continue to increase even in the face of a flat bond market, which could signal credit is easing. Here is a chart of the Bankrate average 30 year fixed rate mortgage minus the 10 year bond yield:
In other economic data, the Markit Composite PMI came in at 60.9, a very strong number. The services PMI came in at 61. The Street forecast for the ISM PMI is 56 (for both services and manufacturing), so there is another possibility of an upside surprise there. The economy is getting better.
Big week coming up with economic data. On Wednesday, we will get the advance estimate for second quarter GDP and the results from the FOMC meeting. Friday is a big day – we will get the jobs report, ISM, and personal spending / personal income. This is a lot of data in one day, and markets will be thin as many desks will be half-staffed. This is a recipe for volatility. The lack of action in the bond market has bred complacency – don’t get caught napping – I wouldn’t be floating ahead of this Friday.
I don’t expect any fireworks with the FOMC meeting – there will be no economic revisions until September, and the meaningful stuff (how to conduct policy after QE, how to prep the markets for rate hikes) won’t make it into the FOMC statement. Separately, Dallas Fed Head Richard Fisher wrote an opinion piece in the Wall Street Journal pressing the Fed to not only end QE but to also start shrinking its balance sheet by not re-investing maturing bonds back into the market. Even that might not be enough. FWIW, he is skeptical of the Yellen framework for bubbles which is that “low interest rates don’t cause speculative bubbles, and we can deal with bubbles through banking regulation.” People have gotten used to the hawks being ignored. As the economy recovers, that will change.
It is official: Zillow is buying Trulia. It would be the marriage of the #1 and #2 online real estate listing sites, so it will attract antitrust scrutiny. Trulia will remain an independent brand and Zillow is following a similar strategy to Barry Diller’s IAC/Interactive corp, where competing brands co-exist as some appeal to different market segments than the other.
Guess the marching orders went out over the weekend: The Administration want to end these inversion transactions, and everyone from Jack Lew to Dr. Cowbell are singing from the same sheet of music. The message: Take away this loophole now, and then let’s focus on corporate tax reform later. It is clear what is going on: The Administration fears a Republican Senate will mean vastly different negotiations regarding corporate tax reform. Republicans are going to want to trade closing loopholes for lowering rates, so Obama wants to get a few “free” tax hikes in (which is what “closing loopholes” really means). Of course Republicans are in no mood to throw Obama a freebie and he knows it, so this is just a means to create some talking points ahead of the midterm elections.
Check out our iServe app for iPhone and Android.
Filed under: Morning Report | 12 Comments »
Stocks are lower this morning on no real news. Bonds and MBS are up.
Durable Goods orders rose .7% in June, topping expectations. Capital Goods ex air / defense rose 1.4%, although May was revised downward in a big way.
The left continues to push Mel Watt to do principal mods on loans held by Fannie Mae. Not sure it is going to happen, as it would undoubtedly trigger a wave of strategic defaults. Interesting that the couple mentioned in the article said they refinanced into a loan with “abusive” terms. A Fannie Mae loan was abusive? Or was this part of the American Dream Commitment, where Fannie partnered with the big subprime players like Countrywide, Irwin, Doral, etc. and agreed to buy their loans for their own balance sheet. Anyway, it looks like Mel Watt is giving the affordable housing advocates the Heisman and running out the clock on principal mods, much to the chagrin of the left.
Potential merger in the real estate data industry: Zillow and Trulia are examining a potential merger.
Good summary of earnings from the homeboys. Orders in units are flat / down (except for D.R. Horton), and ASPs are up. With home prices leveling out, that game isn’t going to last.
Filed under: Morning Report | 48 Comments »
Markets are higher this morning on decent earnings. Bonds and MBS are down.
Initial Jobless Claims came in at 284k, the lowest print since 2006. Consumer Comfort inched up in last week.
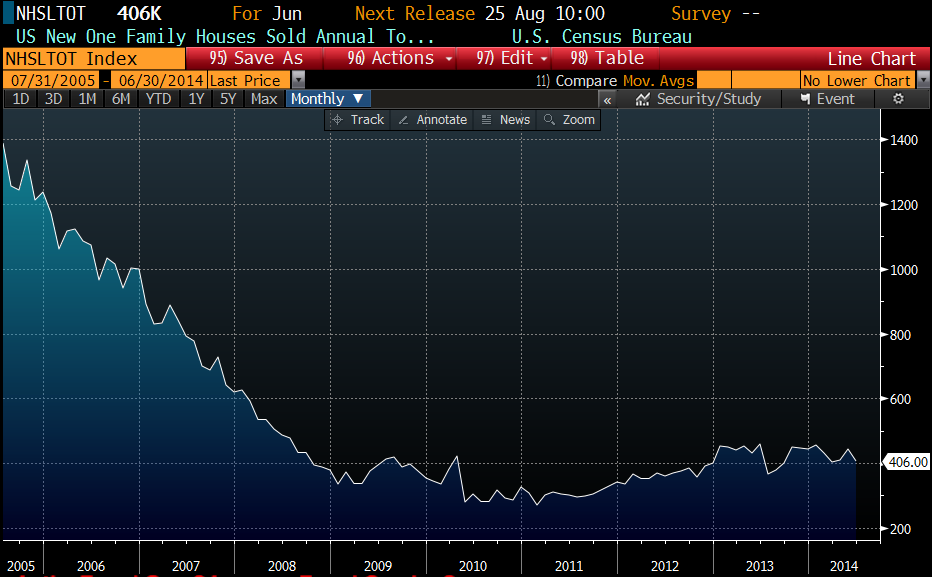
Remember that blockbuster new home sales number last month? 504,000 units? Revised down to 442k. June new home sales came in at 406k. I remember looking at the strong May number and trying to reconcile it with the weak numbers out of KB Home and Lennar, which were announcing earnings at the time. Turns out the new home sales number was bad. You can see how depressed new home sales are from peak levels almost 10 years ago.
D.R. Horton reported earnings this morning, as orders increased 32% in value and 25% in units. The cancellation rate was 24%, though. Interestingly, gross margins fell, which is the first we have seen. The builders have been able to increase prices faster than input costs have gone up. That said, there were some special items in that number so the year-over-year decrease could be misleading. The stock is down this morning.
PulteGroup also announced numbers this morning. Average selling prices rose 12% to $328,000, and gross margins came in at 23.6%, up 480 basis points year over year. Closings dropped 9% in units, however, so Pulte looks to be following the typical builder pattern of higher prices / lower units. PHM is down this morning.
China is in the midst of a skyscraper-building craze. This sort of thing is reminiscent of the 1920s, where the Chrysler Building and 40 Wall Street were neck and neck to build the tallest skyscraper. The Chrysler building won out by constructing the spire inside the building and then pushing it through the top at the very last minute. However their position as tallest was eclipsed by the Empire State Building in the years following. As a general rule, tallest skyscrapers tend to be associated with market tops. Think Chrysler and the Empire State Building prior to the Depression, the Petronas Towers in Kuala Lumpur ushered in the Asian Crisis. China has been going through a period like the US did in the subsequent WWI era – rapid growth and urbanization. They will probably have to go through a gut-wrenching bust like the Depression as well.
Note that China is the biggest international player in the US residential market, and is pushing up prices in Los Angeles, San Francisco, San Diego, New York, and Seattle as professional investors buy up properties sight unseen. Once the Chinese bubble bursts and things start getting ugly, look for these same investors to begin unloading properties in these cities. Remember in a crisis, you sell what you can, not necessarily what you want to.
Filed under: Morning Report | 13 Comments »
Stocks are higher this morning as second quarter earnings are generally better than expected. Bonds and MBS are flat
Mortgage Applications rose 2.4% last week, according to the Mortgage Bankers Association. Purchases rose.3%, while refis rose 4.1%. The MBA backs up the data we have seen from Bankrate- as the 10 year (and TBAs) have rallied over the past month, mortgage rates are flat, except for jumbos, which have dropped 7 bps over the past month. I suspect it is evidence that riskier loans are being done.
When the government settled with the big banks and demanded debt relief, most of the relief came from portfolio loans, but some did not. About 39% of Bank of America’s relief came from loans that were investor-owned – in other words, the money came from someone else’s pocket, not Bank of America’s. It looks like the number at JP Morgan was even higher – 44%. In other words, these banks got fined, but the investors (pension funds, 401ks, mortgage REITs) ended up paying the fine. Of course the best one was Ocwen, who provided $2 billion in relief. The catch? Ocwen is a servicer and simply passes on payments from borrowers to investors. They paid their fine with other people’s money. The Association of Mortgage Investors (AMI) is rightly calling foul. The government is not commenting, although it is stuff like this that partially explains why the private label market hasn’t come back yet. Once bitten, twice shy.
Split decision yesterday on Obamacare. Looks like this one might have to be settled at the Supreme Court. Separately, the IRS destroyed hard drives in the targeting probe. Lots of partisan bickering to pedal into campaign donations before midterm elections. Democrats and Republicans pretty much despise each other at this point. Such is the political climate as Congress goes on break.
Filed under: Morning Report | 15 Comments »
Stocks are higher this morning as earnings reports pour in. Bonds and MBS are flat.
Existing Home sales rose 2.6% month over month to an annualized 5.04 million pace, according to NAR. The median home price rose to $223.3k (up 4.3% YOY), while the average price rose to $269.1 (up 3.1% YOY). Distressed sales accounted for 11% vs 15% a year ago, while the first time homebuyer slipped a point to 28%. All cash deals were basically flat at 32%, and days on market rose from 37 to 44. The housing market is becoming more balanced as inventories are increasing and prices are leveling off.
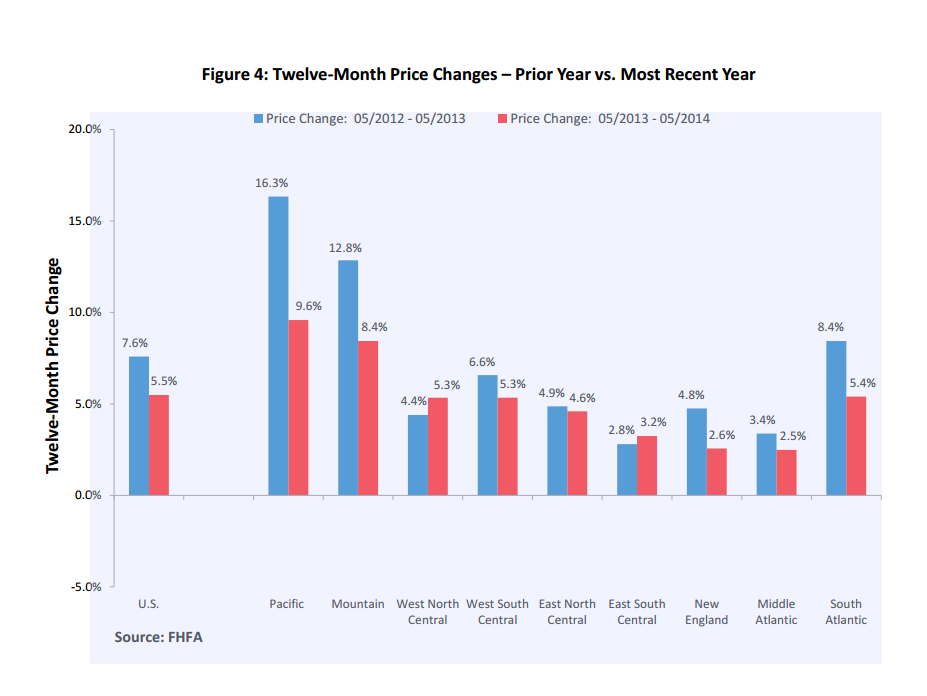
Home prices rose .4% in May, according to FHFA. This is up 5.5% year-over-year. Remember the FHFA index only looks at homes with conforming mortgages, so it is a narrower index than Case-Shiller. The West Coast performed the best, and the Midwest / Mid-Atlantic performed the worst.
The Consumer Price Index came in at .3%, bang in line with expectations. Ex-food and energy, it rose .1%. On a year over year basis, the CPI headline number increased 2.1% and ex food and energy it was 1.9%, more or less where the Fed would like to see the inflation numbers. Note that the Fed prefers to use PCE (Personal Consumption Expenditures) not CPI.
A good backgrounder on Bloomberg about returning vets and VA loans. The VA’s share of new mortgages is at a 20 year high. The stat that jumped out at me was this: VA loans accounted for 8.1% (just under $20 billion) of mortgages made in the first quarter. Last year, VA’s share in Q1 as 6.9% and 10 years ago it was under 2%. The record was 28% in 1947. VA and FHA are tailor made for the first time homebuyer, who wants to buy, but feels shut out of the market.
Speaking of first time homebuyers, here is another article discussing how the economy is depressing birth rates, which would influence household formation numbers. Classic catch-22: The economy needs the housing sector to at least get back to historical norms, but the first time homebuyer is the key to that and they won’t get in until the economy improves.
As a follow-up to yesterday’s comment about the Fed and their belief that (a) low interest rates don’t cause bubbles, and (b) bubbles can be prevented by smart regulation, the appetite for second-lien junk is increasing. Formula One is paying L+6.75 for a $1 billion covenant-light junior loan. Second lien paper is yielding about 9%, while first-lien is yielding about 5.3%. Interestingly, the better credit spreads are widening, while the junkier stuff is tightening. This is of course the unintended consequence of ZIRP, and the biggest risk for 2015 / 2016. The markets are blithely assuming the Fed can start raising rates without any negative consequences for the economy. The economy shook off the end of QE, so there is reason for hope, but I wouldn’t rule out someone big blowing up as rates start increasing, and it will be the junkiest stuff that gets hit the hardest.
Filed under: Morning Report | 9 Comments »
Markets are lower this morning on no real news. Bonds and MBS are up small.
Earnings season kicks off in earnest this week, with a lot of market heavyweights reporting. With the stock market at record highs, it is vulnerable if companies start missing or guiding down for the second half of the year.
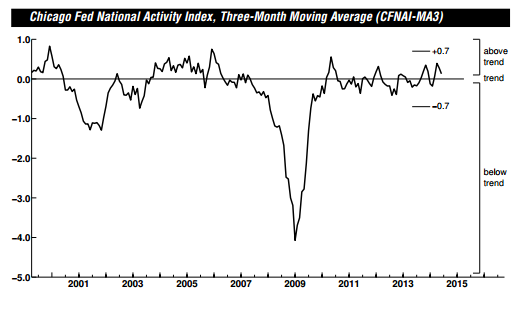
The Chicago Fed National Activity Index decreased to .12, lower than estimates. May was revised downward as well. Production indicators were flat, however employment was a big positive contributor. This index is notoriously volatile, so it makes sense to look at the 3 month moving average, which has been declining over the past couple of months.
As bonds have rallied these past couple of week, mortgage rates have gone up. The spread between the Bankrate 30 year fixed rate mortgage and Treasuries has blown out. Not sure why this is happening – TBAs have been rallying with bonds, so it isn’t necessarily MBS related. It could simply be something funky with the data which will get corrected. Another possibility is that mortgage bankers are moving out on the risk curve and doing loans they would have turned down a year ago.

Jamie Dimon’s comments about ending FHA loans raises questions about how it can meet its CRA goals. If it doesn’t do FHA loans, it will have to portfolio some more CRA loans. Jamie Dimon said on the conference call regarding fair lending quotas: “Yes, if you don’t do any FHA, that hurts you a little bit. But to do FHA and lose billions of dollars, that’s a whole different level of shareholder irresponsibility.” Implicit in that statement is the idea that CRA loans are losers and a cost of doing business. Which flies in the face of the standard fair lending talking points that banks are avoiding perfectly good loans out of racism. The truth is that the fair lending advocates are forcing banks to subsidize low income borrowers. Who pays? Everyone else who has a mortgage. It would be nice if the government was intellectually honest about CRA loans – saying we want low-income people to get mortgages, we don’t want banks to fully charge the borrower for the added risks they represent, and we don’t want to pay for it. So we will force other borrowers to subsidize these loans. The government is simply being generous with other people’s money.
Speaking about talking points, one of the big ones out of the Fed is their belief that bubbles are (a) not caused by too-low interest rates and (b) regulation of banks can prevent them from taking risks they shouldn’t be taking. This theory is being tested as we speak, in the high yield market. The issue is that when rates are super-low, investors HAVE to move out on the risk curve to make any money. The demand is there. Think about it this way: if you are an insurer or pension fund, the actuarial tables couldn’t care less that money is free. You still have to hit your return bogey. And if you can’t do it in low-risk products, you’ll have to do it in high risk products.
Filed under: Morning Report | 5 Comments »

