Posted on January 27, 2016 by Brent Nyitray
Stocks are lower this morning on lower oil prices and disappointing numbers out of Apple last night. Bonds and MBS are down small.
The FOMC will announce their decision at 2:00 PM EST today. No change in the Fed Funds rate is expected. Bond bulls are going to be looking for a mention of the recent market volatility or oil prices and the path of future inflation. Bond bears will be looking for no mention of oil / volatility and / or language that characterizes these effects as transitory.
New Home Sales increased to 544k in December from 491k the month before. The Spring Selling season is just around the corner. For the full year, new home sales increased 14.6% to 501,000, the highest level since 2007. Interestingly, the median sales price fell 4.3% to $288,900. D.R. Horton’s product mix has mirrored that somewhat, with the Horton Express (starter homes) becoming a bigger share of revenues while Emerald (McMansions) has fallen.
Mortgage Applications rose 8.8% last week as purchases rose 4.6% and refis rose 11.3%.
Weakness in the overall economy depressed sales for Apple. They are seeing it especially in Asia between China and Hong Kong. China is going to be exporting deflation, which is going to make the Fed’s job tougher.
Filed under: Morning Report | 28 Comments »
Posted on January 26, 2016 by Brent Nyitray
Stocks are higher this morning in spite of another down 7% day in China overnight. Bonds and MBS are flat
House prices continue to rise, according to the FHFA House Price Index and Case-Shiller. The FHFA House Price index rose 0.5% MOM, while Case-Shiller rose .94%. The Case-Shiller index is up 5.83% YOY. The FHFA House Price Index has recouped all its post-bubble losses.
In other economic data, the Richmond Fed Index slipped while consumer confidence increased.
The Fed starts their 2 day FOMC meeting today. The decision is expected tomorrow at 2:00 PM EST.
Homebuilder D.R. Horton reported earnings yesterday and met Street expectations. Orders increased 9% in units and 12% in value. Backlog is up 15% at 10,665 homes. The company is “Well-positioned” for spring selling season, FY 2016, given backlog, “positive sales trends” in Jan., “robust” lot supply, inventory of homes available for sale according to Donald R. Horton, chairman of DHI. Their new brand for first time homebuyers – Horton Express – accounted for 22% of sales last quarter.
Foreign money helped prop up the ultra-luxury sector of the real estate market and now they pulling back. Prices are stagnating and homes are not moving. Blame the stock sell-off in China, and the oil price collapse which is hurting Middle Eastern and Russian investors.
Filed under: Morning Report | 9 Comments »
Posted on January 25, 2016 by Brent Nyitray
Stocks are lower this morning on lower oil prices and weaker overseas markets. Bonds and MBS are up small.
Not much data this morning, although we do get some important real estate data this week with the FHFA House Price Index and Case-Shiller on Tuesday, new home sales on Wednesday, and pending home sales on Thursday. We will also get the first estimate of fourth quarter GDP on Friday, with the consensus estimate at 0.8%. While this is a dramatic slowdown from the third quarter, a recession in the US is probably not in the cards (Bank of America is handicapping a 20% chance of a recession next year). Remember the old market saw: stocks have predicted 12 of the last 5 recessions..
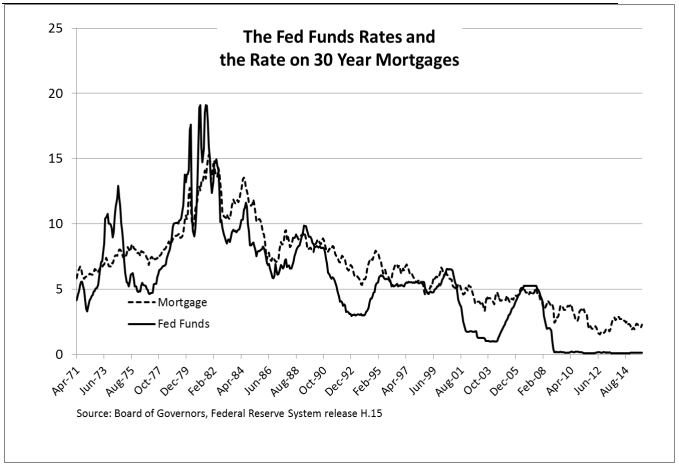
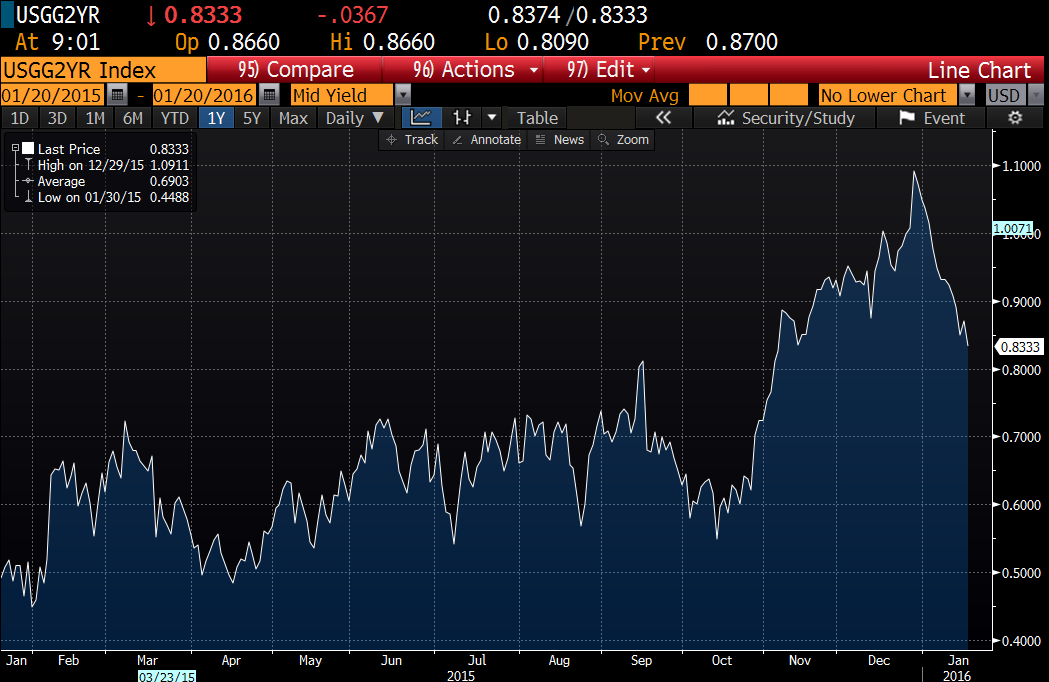
The main event of this week is the FOMC meeting on Tuesday and Wednesday. The general consensus is that the Fed isn’t going to hike rates at this meeting. Given the turbulence in the markets lately people are beginning to think the March meeting isn’t a definite hike either. Ever since the Fed hiked rates in December, the two year bond yield has dropped by 24 basis point to 0.86%. If you take a look at the chart below, it plots the Fed Funds rate versus mortgage rates. While there is a correlation, over the past 50 years or so, mortgage rates have risen or fallen with Fed Fund, but at a much slower rate. In fact, during the last tightening cycle, mortgage rates barely moved, although there could be some bubble effects happening as well.
Filed under: Morning Report | 42 Comments »
Posted on January 22, 2016 by Brent Nyitray
Stocks are higher this morning as global markets rallied overnight. Bonds and MBS are lower.
Generally a risk-on feel to the market, as stocks and commodities are rallying. Oil is back above $31 a barrel.
The Chicago Fed National Activity Index improved to -.22 from -.36 last month, while the Index of Leading Economic Indicators fell 0.2%.
Existing Home Sales rose 14.7% in December to 5.46 million. November’s numbers were depressed by TRID, and it looks like much of those sales got bumped to December. This makes 2015 the best year for existing home sales since 2006. The median home price increased 7.6% to $224,100. Housing inventory continues to fall, and the 1.79 million homes for sale represents only a 3.8 month supply (6 – 6.5 months’ worth constitutes a balanced market). First time homebuyers accounted for 32% of all sales, while all-cash transactions fell to 24%.
Things might run a little slow today as the Federal Government workers will leave at noon to get home before Snowmageddon II hits DC. Fannie Mae pricing will be the most affected.
Filed under: Morning Report | 19 Comments »
Posted on January 21, 2016 by novahockey
On the Flint disaster:
In sum: The Democratic government of a Democratic city destroys that city’s finances so thoroughly that it must go into state receivership; a Democratic emergency manager signs off on a consensus plan to use a temporary water source; the municipal authorities in that Democratic city responsible for treating and monitoring drinking water fail to do their job; a state agency whose employees work under the tender attention of SEIU Local 517 fails to do its job overseeing the local authorities; Barack Obama’s EPA, having been informed about the issue, keeps mum. Republican scandal.
Filed under: Morning Report | 43 Comments »
Posted on January 21, 2016 by Brent Nyitray
Stocks are up this morning as ECB President Mario Draghi hinted at further easing in March. Bonds and MBS are up small.
Stocks got pummeled yesterday with the Dow down 566 points in early afternoon. Markets then turned around on no real news and rallied into the close to cut the losses for the day. The 10 year got down to 1.94%.
Initial Jobless Claims rose to 293k from 283k yesterday. This is the highest level in 6 months. The Philthy Fed Index improved from -10.2 to -3.5.
We are starting to see more announcements about job cuts. Johnson and Johnson is cutting 3,000 and Barclay’s is letting 1,200 go as it pulls out of Asian markets.
Filed under: Morning Report | 6 Comments »
Posted on January 20, 2016 by Brent Nyitray
Housing starts fell in December from 1.17 million to 1.15 million, missing the 1.2 million Street estimate. Building permits fell from 1.28 million to 1.23 million, topping the 1.2 million estimate. Single-fam permits hit the highest level in 8 years. I sound like a broken record, but the economy isn’t going to hit the next level until housing construction returns to normalcy, about 1.5 million units per year. The plus side of this is that the housing deficit continues to grow, which means the rebound (when it happens) will be stronger and longer. Confidence and credit remain the issues at the moment.
Mortgage Applications rose 9% last week as refis rose 18.7% and purchases fell 1.6%. With the 10 year trading below 2% again, there should be refinance opportunities. With the 10 year yield falling and the Fed Fund rate increasing, the strategy to pitch is to swap out of an ARM (which is pegged to short term rates) and into a 30 year fixed.
Inflation remains under control, as the consumer price index fell 0.1% in December. Ex-food and energy it increased 0.1%.
The dramatic sell-off in the markets has taken down rate hike expectations out of the Fed. You can see this in the 2 year bond yield, which has fallen 25 basis points since late December. This forecast was borne out in the latest Bank of America survey on the economic outlook. A month ago, 40% of fund managers expected no more than 2 rate hikes in 2016. Now that number is closer to 50%.
Earnings season is upon us, and the first companies to report are out of the banking sector. The main theme: a withdrawal from mortgage banking. The only big bank to report an increase in mortgage banking? Wells. Jamie Dimon said on JP Morgan’s conference call that the banks remain under assault. And politicians in DC continue to scratch their heads and wonder why the economy remains tepid. Refer to housing starts above.
Filed under: Morning Report | 19 Comments »
Posted on January 19, 2016 by Brent Nyitray
Markets are higher this morning as commodities rally. Bonds and MBS are down small.
The NAHB Homebuilders Index was unchanged at 60 last month.
Last Friday had some bad numbers with retail sales disappointing and industrial data coming in much softer than expected.
Bank of America reported better than expected numbers this morning, with mortgage production up 13%.
The 10 year bond yield touched 2% on Friday during the stock market sell-off. For those keeping score at home, the 10 year bond yield has dropped about 25 basis points since the Fed hiked rates in December.
Jeb Bush’s donors are getting cold feet. The rumor is that he needs to be in the top 3 in Iowa and New Hampshire or else they are going elsewhere. The “elsewhere” is Rubio.
On Friday, the Atlanta Fed took down their estimate for Q4 GDP to 0.6%. Luckily they waited until after the close to drop that bomb.
Filed under: Morning Report | 10 Comments »
Posted on January 14, 2016 by Brent Nyitray
Markets are up this morning after yesterday’s bloodbath. Bonds and MBS are up.
Initial Jobless Claims ticked up to 284k last week. Import prices fell 1.2% as the dollar rallied, and consumer comfort ticked up a tiny bit last week.
Note that in the President’s State of the Union address, housing was basically ignored. The country has an acute shortage of affordable housing, and housing starts are still mired well below historical averages. Getting housing back on track is the difference between 2% GDP and 3% GDP. Unfortunately, the only mention political candidates have regarding housing is that Wall Street is evil, the banks are too big, and there needs to be more government control. Which is most definitely not the way to increase credit or confidence.
Filed under: Morning Report | 20 Comments »
Posted on January 13, 2016 by Brent Nyitray
Markets are higher this morning as oil rebounds a little. Bonds and MBS are up.
Mortgage Applications rose 21% last week as purchases rose 18% and refis rose 24%.
New regulations may require banks to raise up to $550 billion in the bond market by 2019. The bonds will be part of a package that are designed to prevent another 2008 from happening. They will be senior unsecured debt that converts to equity when a bank becomes insolvent. The new regs are open for comment and the ABA is working hard to lower the amount. I have trouble imagining the type of investor that would buy half a trillion of this stuff.
China’s troubles are further evidence that whenever a country appears to have “cracked the code” for seemingly perpetual growth, a real estate bubble is usually the culprit. And it always ends badly.
Larry Summers is warning the Fed that the global economy cannot withstand 4 rate hikes this year. The bond market rally is saying the same thing. Since the Fed hiked rates on Dec 16, the 10 year bond yield has fallen 20 basis points.
Boston Fed Chairman Rosengren is also warning about further growth and the effect that overseas weakness will have on the US economy.
The US is starting to require title companies to identify the people who pay cash for properties in NYC and Miami.
Filed under: Morning Report | 9 Comments »