Morning Report: Job openings fall 7/12/16

Vital Statistics:

Last Change
S&P Futures 2141.0 11.0
Eurostoxx Index 335.9 3.2
Oil (WTI) 46.0 1.4
US dollar index 86.9 0.1
10 Year Govt Bond Yield 1.48%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
BankRate 30 Year Fixed Rate Mortgage 3.57

Stocks are higher this morning as global markets continue to recover in anticipation of further government stimulus. European bank shares, which led the markets down, are rebounding. Bonds and MBS are down

Job openings fell to 5.5 million from 5.8 million in May. This is the lowest since February, and shows that some of the strength in the labor market is dissipating. Note that the JOLTS data has been much stronger than the other labor market indicators – it was at a record not too long ago.

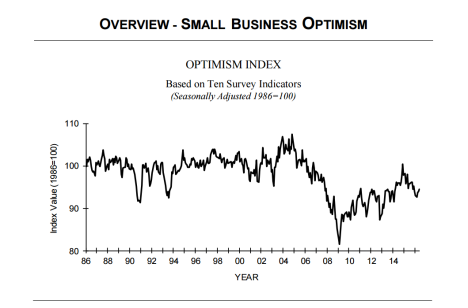
The NFIB Small Business Optimism ticked up .7 points in June. Small business owners appear to be on the same track they have followed for the past few years – maintenance mode, but not much growth. This will keep the economy moving forward, but not at an impressive pace. While sentiment has been improving, it remains well below the average of 98 since the mid-80s.
NFIB

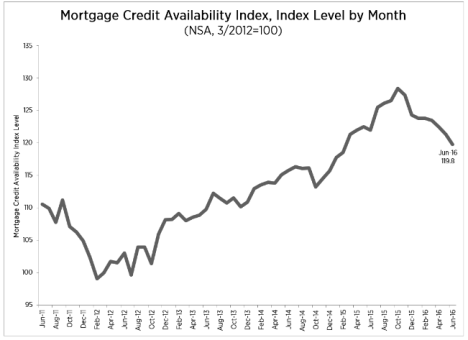
Mortgage credit availability decreased in June, according to the MBA’s Mortgage Credit Availability Index. Conventional loans had the biggest tightening, while government loans only tightened slightly. A number of investors discontinued conventional high balance 7-year ARMs, while keeping their 5 and 10 year ARMs intact. A note about the chart below. It begins in early 2012 at 100, which more or less marks the bottom of the real estate bust. If you use the same methodology to project what the index would have been previously, it would have peaked at about 900 in 2006, compared to 120, where it is today.
MCAI

Completed Foreclosures fell 7% year-over-year to 38,000 according to CoreLogic. The national foreclosures inventory fell 25% to 390k homes, or about 1% of all homes with a mortgage. This takes us back to October 2007 levels, which is still about 2x the historical average. The seriously delinquent rate continued to fall and is now down to 2.8%.

The House approved a bill changing the structure of the CFPB, by subjecting it to Congressional appropriation like every other governmental agency, and replacing the single director with a bipartisan committee. It also requires the CFPB to conduct a cost-benefits analysis for any proposed changes to arbitration regulations.

Lot sizes for new homes are the smallest on record, according to the NAHB, down to 8,600 square feet. 20 years ago, the median lot size was about 10,000 square feet. Interestingly, the average square footage of new homes has increased by 150 since the real estate bust.

Morning Report: Is the post-Brexit rally over? 7/11/16

Vital Statistics:

Last Change
S&P Futures 2128.0 8.0
Eurostoxx Index 324.3 2.1
Oil (WTI) 45.6 0.4
US dollar index 87.1 0.1
10 Year Govt Bond Yield 1.41%
Current Coupon Fannie Mae TBA 104
Current Coupon Ginnie Mae TBA 104.2
BankRate 30 Year Fixed Rate Mortgage 3.57


Stocks are up this morning as overseas markets rally. Bonds and MBS are down.

Friday’s huge payroll print was largely due to seasonal adjustment factors. The unemployment rate rose, hourly earnings barely budged and the labor force participation rate inched up only slightly. The right thing to do is to take May’s 11k number and average it in with June’s 287k number to get a more realistic run rate.

There isn’t much in the way of market-moving data this week – the week after the jobs report is invariably data-light. Earnings season kicks off this week, and the next two weeks will be dominated by bank earnings.

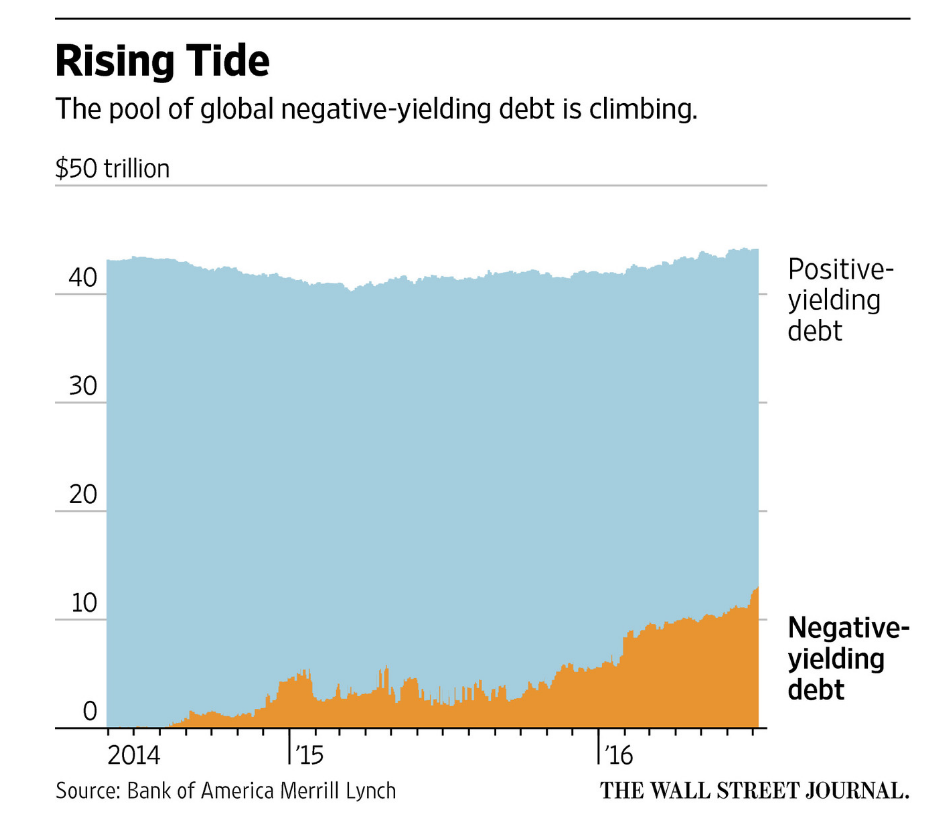
Morgan Stanley is making the call that the post Brexit bond market rally is largely played out. “After having been bullish, we turn neutral on bonds as G4 yields sit at all-time lows,” Morgan Stanley analysts including Matthew Hornbach, the head of global interest-rate strategy in New York, wrote in a report July 8. That said, the increasing amount of negative yielding paper will continue to push up Treasuries in the US, as investors sell bonds yielding nothing to buy bonds yielding something. This will also lower borrowing costs for Corporate America.

Don’t forget the last time bond yields bottomed out (2012) it took mortgage rates another 4 months to bottom out as well. We should probably see a similar effect going this time around.
Mortgage delinquency rates ticked up in May, according to the latest Black Knight Financial Services Mortgage Monitor. Some of this is apparently seasonally driven. Interesting stat: From 2009-2012, over 80% of borrowers that refinanced a GNMA loan refi’d back into another GNMA product. Post 2013, GN back into GN refis have dropped below 50%. Increasing home equity and higher MI premiums are pushing borrowers out of GN products.

Morning Report: June payrolls rebound in a big way 7/8/16

Vital Statistics: Last Change
S&P Futures 2112.0 15.0
Eurostoxx Index 324.3 2.1
Oil (WTI) 45.5 0.4
US dollar index 87.1 0.1
10 Year Govt Bond Yield 1.41%
BankRate 30 Year Fixed Rate Mortgage 3.44

Stocks are higher after the jobs report came in stronger than expected. Bonds and MBS are down small

Jobs report data dump:

  • Nonfarm payrolls + 287k
  • Two month revision -6k
  • Unemployment rate 4.9%
  • Labor force participation rate 62.7%
  • Average weekly hours 34.4
  • Average hourly earnings + 0.1% (+2.6% YOY)

The payrolls number is certain to get everyone’s attention, however some of that might be a catch-up from May, which was revised downward to only 11k jobs. The 3 month average is 147k. Given Brexit, this report probably doesn’t move the needle for the Fed. Until we start seeing more evidence of wage inflation the Fed isn’t going to be aggressive.

Mortgage rates have lagged the move downward in Treasuries. As we saw in 2012, bond yields bottomed out in July, but mortgage rates continued to fall for another 4 months, finally bottoming in November. We are seeing the same thing again, where mortgage rates have fallen with the 10 year, but nowhere near as dramatically. Note the MBA keeps bumping up its forecast for 2016 volume.

Morning Report: FOMC minutes a non-event 7/7/16

Stocks are higher this morning on no real news. Bonds and MBS are down after a stronger-than-expected ADP jobs report

We have a few economic data points this morning. Job Cuts fell 14.1% in June, according to Challenger and Grey. Job cuts fell in the East and Midwest, while rising in the South and the West.

The ADP Employment number shows private companies added 172k jobs in June, above the 160k forecast. May was revised to 168k. Of course last month the ADP number came in at 173k while the official BLS nonfarm payroll number came in at 38k. So ADP has been pretty useless lately

Initial Jobless Claims fell to 254k last week.

The FOMC minutes didn’t really shed much light on the state of thinking at the Fed, other than to say the Fed remains data-dependent. The June FOMC meeting predated Brexit, so in many ways it is a dated view. The participants noted that the labor market weakened while the overall economy was strengthening, and believe that the economy will continue to grow moderately. Given the added uncertainty of Brexit, the FOMC meeting in a few weeks will almost certainly be a non-event, and even tightening in September looks like a tall order.

Morning Report: Bill Gross talks Monopoly 7/6/16

Stocks are lower this morning as markets fret about the Italian banks and the Japanese 20 year bond went negative overnight. Bonds and MBS are up. The US 10-year hit 1.32% overnight and is trading at 1.36% at the moment. The German Bund now yields -18 basis points.

The FOMC minutes from the June meeting will be released around 2:00 pm EST today. Brexit has pretty much made these pretty much irrelevant for July meeting which is in 3 weeks. Still, there is always the possibility that something surprising could come out of it, so just be aware.

Mortgage applications rose 14.2% last week as purchases rose 4.3% and refis increased 20.8%.

The June ISM services index jumped to 56.5 from 52.9 in May.

Hillary Clinton will not face criminal charges over the email investigation. This should stick a fork in Bernie.

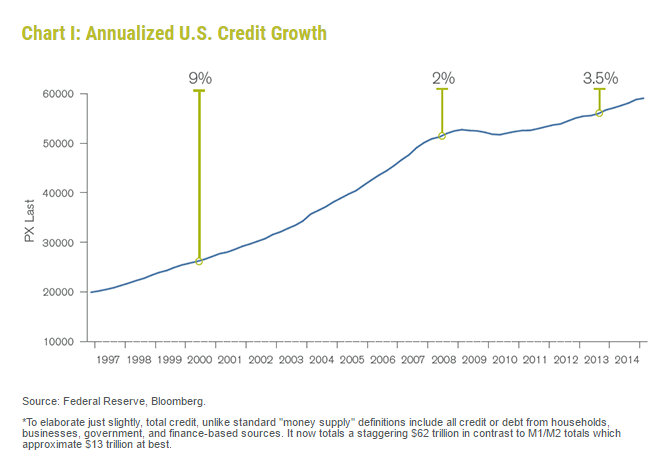
Bill Gross compares the current state of the economy to the game of Monopoly. In the beginning of the game, you get $1,500 and begin buying properties (investing). You also get $200 for passing go. However, the game always ends in a credit crunch where your opponents go bankrupt. He then imagines the game where the amount you get for passing go increases as the game progresses. He likens the income from passing go as credit growth. If you look at credit growth over the past several years, it has been much less than the previous decades. His advice to Janet Yellen is to stop worrying about the Taylor rule and inflation and worry more about slow economic growth. While QE and negative interest rates should have helped create credit, they aren’t really doing that, and the current economy is like the end of a monopoly game, where all the property has been bought, and conservation of cash becomes the name of the game. This is a recipe for stagnant growth.

Bank of America is forecasting a 1.25% 10 year yield by the end of September as pension funds embrace the “lower for longer” thesis and build their holdings of Treasuries. Roughly 6% of pension fund assets are in Treasuries, about half the allocation they were in 1980. Of course Treasuries represented true value in 1980, and now they are simply a momentum trade. The 100 largest pension funds in the U.S. have a shortfall of $400 billion, which has doubled over the past year. Pension funds have been the biggest victims of ZIRP, as the actuarial tables couldn’t care less that interest rates are zero. In fact, it makes their liabilities appear even worse because the rate used to discount them is lowered.

Morning Report: Trust in government is at a record low 7/5/16

Markets are lower this morning as bond yields push lower globally. Bonds and MBS are up, with the 10 year trading below 1.4%. The German Bund now yields negative 16 basis points.

We have a short week, but a lot of data. The biggest events will be the FOMC minutes on Wednesday and the jobs report on Friday. Given the Brexit backdrop, I see the FOMC minutes as a nonevent, and the jobs report shouldn’t be market moving unless wage inflation accelerates.

This morning, the ISM New York Index rose from 37.2 to 45.4. Still, a reading below 50 is indicative of a slowing economy.

Economic Optimism slipped in July to 45.5 from 48.2 a month ago.

Factory Orders fell 1% in May after increasing 1.8% in April. Durable Goods orders fell 2.3% while capital goods orders, which is a proxy for business capital expenditures, fell 0.3%.

Last week stocks rallied as it looks like Brexit didn’t trigger a financial crisis. Bonds continued their march higher and yield curves flattened, which is a recessionary pattern. Generally speaking, when the stock market and the bond market disagree, the bond market is usually right. That said, Italy is injecting more capital into its weak banking system, but that issue predates Brexit.

Speaking of Italy, they may be the next one out of the EU, as they have issues with their banks and cannot come to the aid of banks without giving investors a haircut according to EU rules. Since about half of Italian bank debt is held by ordinary Italians, no politician wants to suggest that investors lose money on a bailout. Plus their debt to GDP ratio is 1.3x, which gives them little maneuvering room.

Brexit and the rise of Donald Trump are symptoms of a bigger problem: a lack of trust in government and institutions like the media. Some say we need to learn to trust the government. Other say we need to push Facebook to use its algorithms in order to show opposing viewpoints more often. Bottom line, we are more polarized than ever before, and no matter who wins in November, gridlock will be the name of the game. Both parties are focused on one thing: a potential 3 or 4 Supreme Court nominees, which would ideologically skew the Court for a generation.

Home prices rose 5.9% in May, according to Corelogic.

Loan performance increased in the first quarter, according to the OCC. Performing loans are up 0.7% YOY, while foreclosures have declined to 0.4% to 0.9%.

Morning Report: Treasury yields hit an intraday record low 7/1/16

Vital Statistics:

Last Change Percent
S&P Futures 2090.5 0.3 0.01%
Eurostoxx Index 2888.6 23.9 0.83%
Oil (WTI) 48.03 -0.3 -0.62%
LIBOR 0.646 0.015 2.38%
US Dollar Index (DXY) 95.66 -0.488 -0.51%
10 Year Govt Bond Yield 1.44% -0.03%
Current Coupon Ginnie Mae TBA 106.2
Current Coupon Fannie Mae TBA 105.6
BankRate 30 Year Fixed Rate Mortgage 3.53

Markets are flattish as we head into a 3 day weekend. Bonds and MBS are up.

Bonds will close early today and most of the Street will be on the LIE by noon.

Manufacturing picked up in June, according to the ISM Manufacturing Survey. New orders were up while prices paid fell.

Construction spending fell 0.8% in May versus an expected increase of 0.6%. April was revised downward from -1.8% to -2%. Homebuilding was flat versus April and is up 5.3% on a year-over-year basis.

Vehicle sales are coming in this morning, and they look light generally.

Overnight, the 10 year yield touched 1.38%, which is a record low on the 10 year. It looks like we are getting ready for another refi boom. Vanguard, Blackrock, and Guggenheim are all making the call that Brexit means slower growth and lower rates for the next couple of years. How pension funds and insurance companies, which need to earn 7% or more to keep up with liability growth will do that is beyond me.

Note that the Bankrate 30 year fixed rate mortgage rate is still about 20 basis points higher than the record low set in late 2012. Mortgage backed securities have lagged the move up in Treasuries. Below is a chart of the Bankrate 30 year fixed rate mortgage rate versus the 10 year yield. The top line is mortgage rates, the lower line is the 10 year yield. If you look at the 2012 period, you can see that the 10 year yield bottomed out in July, and started rising into the end of the year. Mortgage rates kept falling throughout the year, bottoming out in December. So, mortgage rates didn’t bottom out until 5 months after Treasuries did.

mortgage rates vs treasury yields

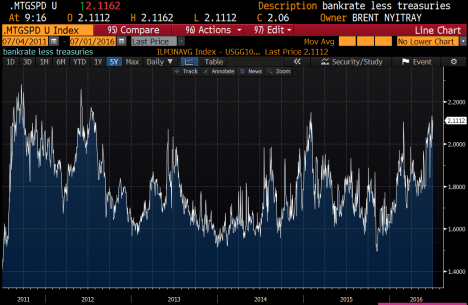
If you plot the difference between the two rates (basically a proxy for MBS spreads), you can see that the current difference is approaching a high again. If this is a truly mean-reverting series, you should expect that gap to close over time, and that will either happen through higher Treasury yields or lower mortgage rates. Given the momentum in the Treasury markets at the moment, it is probably mortgage rates that will have to give. Which means we could have a good refi season into the end of the year.

mortgage spreads.PNG

The worlds’ central bankers are being forced to take the global economy into account more and more. Brexit gives Janet Yellen the excuse to hold off on hiking rates until we see inflation in the US. The ECB and the Bank of England are looking at easing. Could the next move by the Fed be some sort of stimulative measure, like bringing back QE or cutting the Fed Funds rate back down to .25%? It is definitely a non-zero probability.

The discussion draft of the bill to reform the CFPB is out. The main changes would be to bring the agency under Congressional control (it nominally reports to the Fed, but in reality it reports to no one) and to replace a single director with a bipartisan board of 5. It will also make some changed aimed at curbing the most abusive practices of the agency. While the Elizabeth Warren wing of the Democratic party will fight this tooth and nail, the affordable housing lobby is getting sick and tired of tight credit. Note that the President doesn’t think there is an issue, and even if there was, it isn’t his fault. Quote from the article:

Bloomberg Magazine: “Some of the rules put in place have meant it’s harder to get a loan. Something like 58 percent of approved mortgages are going to the wealthiest applicants, and homeownership among African Americans is down. Where’s the balance there?

Obama: “Well, the interesting thing—and we’ve looked at this very carefully—is that there’s no doubt that there’s been some pullback and increased conservatism on the part of lenders. But oftentimes, it’s not justified by the regulations”

Morning Report: Banks pass stress test 6/30/16

Vital Statistics:

Last Change Percent
S&P Futures 2067.7 0.9 0.04%
Eurostoxx Index 2838.7 6.5 0.23%
Oil (WTI) 48.86 -1.0 -2.04%
LIBOR 0.631 0.004 0.64%
US Dollar Index (DXY) 95.7 -0.069 -0.07%
10 Year Govt Bond Yield 1.50% -0.02%
Current Coupon Ginnie Mae TBA 106.1
Current Coupon Fannie Mae TBA 105.4
BankRate 30 Year Fixed Rate Mortgage 3.54

Stocks are taking a breather after a ferocious two-day rally. Bonds and MBS are up.

Initial Jobless Claims came in at 268k, up 9k from the previous week. Claims have now been below 300k for a year, which is an astounding run.

In other economic data, the Chicago Purchasing manager index rose while the Bloomberg Consumer Comfort index fell.

Last night, the Fed released the results of its stress tests and most, if not all, US banks passed. After the close, the tape was dominated by news of banks raising dividends and buybacks. Deutsche Bank failed to pass. Deutsche Bank’s market cap stands at just under $19 billion, roughly the same size as M&T or Suntrust. Citi’s market cap is $123 billion. This gives you an idea how hard the banking system has been rocked in Europe.

George Soros believes Brexit will be the catalyst to unleash a financial markets crisis. He believes it will be concentrated in Europe, where their economies are stuck in a deflationary trap, similar to Japan. His prescription is for European governments to adopt deficit spending en masse to boost aggregate demand. Of course Japan has been doing exactly that for over 25 years. All they have to show for it is negative interest rates, flat GDP and a debt to GDP ratio of 2.2x. He is also predicting a hard landing in China, which would add fuel to the fire. Punch line: Deflationary forces emanating out of Asia and Europe will keep the US dollar strong (which will dampen inflation in the US) and interest rates low.

When talking about interest rates, it is important to remember that interest rate cycles are long. Below is a chart of long term Treasury yields in the US going back 90 years. The relevant comparison for the global economy right now is the 1930s. The crash was in 1929, (versus 2008) and rates kept falling for another 11 years. It looks like rates bottomed around 1940. Rates remained unusually low until the late 1950s. To put a parallel on that, we would be looking for rates to bottom out somewhere around 2020, and then have another 10 years where these exceptionally low rates increased only gradually. Note the trough-to-peak time was about 40 years. Of course history doesn’t repeat – it only rhymes, however those looking for a cataclysmic top in the bond market might be waiting a while.

Treasury yields long term

Fun fact: There are now $11.7 trillion worth of bonds with negative yields right now. The notional amount of bonds with negative yields and maturities of 7 years or longer is $2.6 trillion. This number has doubled since April. The UK 10 year is still positive, yielding .95%, but who knows how long that will last. This is the thing to keep in mind: with global rates near or below zero, there will be a natural bid for Treasuries. It is inevitable as global investors sell bonds yielding nothing to buy bonds yielding something.

Morning Report: Brexit panic over? 6/29/16

Stocks are higher this morning as global stocks and commodities rally. Bonds and MBS are flat.

It seems like the big Brexit-related sell-off might be over.  Brexit will have a negligible effect on US corporate earnings, and stocks will benefit from a lower, steadier interest rate environment. I would look for the correlation between US stocks and global stocks to break down gradually. I am not sure we will see the same effect in the Treasury markets as the global bond market is simply much more integrated. Speaking of which, global bond yields are holding steady this morning, with the German Bund at -11 basis points and the the PIIGS slightly lower.

First quarter GDP was revised to +1.1%. while personal consumption came in at 1.5% and the PCE index (the inflation measure preferred by the Fed came in at 0.4%). Housing as a percentage of GDP increased. I have long said the difference between this sub-par economy and a strong one is housing. Politicians have yet to figure this out.

Home prices rose .5% MOM and 5.4%YOY, according to the Case-Shiller home price index. Home prices in 7 MSAs (Denver, Dallas, Portland OR, San Francisco, Seattle, Charlotte, and Boston) have eclipsed their 2006 peaks.

Personal Incomes rose 0.2% in May, slightly below forecasts, while personal spending increased 0.4%, right in line with expectations. For the month, the PCE core index rose 1.6% YOY, which is still below the Fed’s target of 2%.

Mortgage Applications fell 2.6% last week as purchases fell 3% and refis fell 2.4%. Pending Home Sales fell 3.7% MOM in May and are up 2.4% YOY.

The Fed is scheduled to release the results of its stress tests for the largest US banks. The results should come out after the close. Billions of dollars in dividends and buybacks are on the line. Separately, GE’s systemic designation has been rescinded by US regulators. GE is the first institution to have the designation removed, which requires stringent capital and leverage requirements. GE has sold much of its GE Financial division, and has returned to its roots as an industrial manufacturer.

Speaking of banking crises, the European big banks have stabilized in the aftermath of Brexit. The canaries in the coal mine are Deutsche Bank and Unicredito. Even Barclay’s and RBS have stabilized. The thing to keep in mind is that the banks now have almost double the capital they had in 2008 and Brexit is nothing like the bursting of the US residential real estate bubble. The Bernank agrees.

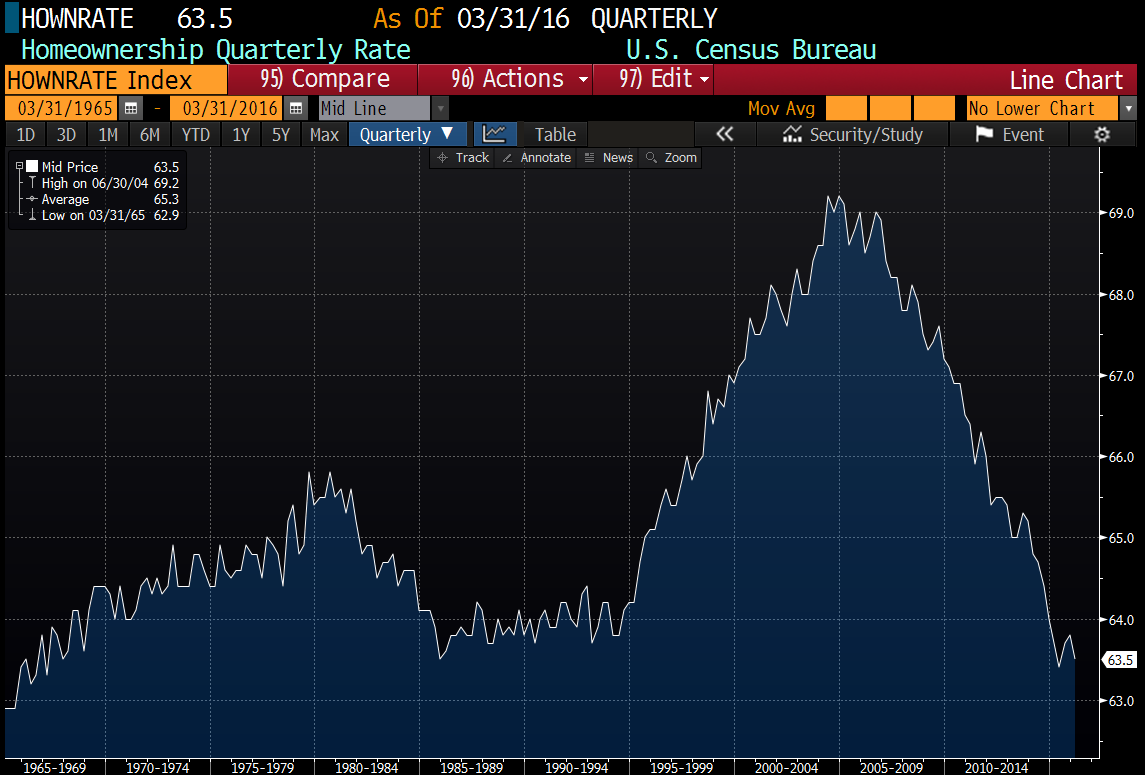
Freddie Mac wonders if the homeownership rate can fall below 50%. The current level is at 63.5%, which is the lowest in 22 years, and just off the low of 63%, which goes back to 1965, when Census started tracking the statistic. They look at 3 studies, which all predict lower homeownership going forward. The factors inhibiting an increase in homeownership are lower income growth, high rental prices, tight supply and and high student loan debt / tight credit. It is hard to tell what a “normal” homeownership rate as the 2005 spike was the result of a bubble and a lot of social engineering via the housing market, which really started early in the Clinton Administration.

Morning Report: Implications of Brexit 6/27/16

Stocks are lower this morning as markets adjust to Brexit. Bonds and MBS are up.

Here is the summary of the financial market reaction to Brexit: Stocks down, Treasuries up, US dollar up, Gold up, but other commodities down. Fed Funds futures pricing in no more interest rate hikes this year. In many ways, markets were discounting #Bremain in the week or so heading up to the vote, so in many cases, they merely gave back those moves. Friday was volatile, with 3-sigma moves seen in 23 currencies, 30 sovereign bonds, and and 28 stock market indices.

What does Brexit mean to the European financial markets?  The banks got crushed on Friday, and part of that is due to widening sovereign spreads. Brexit caused a yield divergence between the German Bund and the PIIGS (Portugal, Italy, Ireland, Greece, and Spain) bonds. Greek spreads widened out 89 basis points to 8.65%. German bond yields fell 14 basis points to -5 basis points. While yields on the PIIGS are still low, they could become an issue going forward.

The biggest risk to the US is any sort of financial contagion. The tell will be the performance of the European and UK banks. Note Italy is considering injecting 50 billion euros into its banking system. The PIIGS are behaving this morning, but that will be something to watch.

Brexit has put the Fed in a box. The slowing economy in China plus the issues with Brexit have pretty much put them on the sidelines for now. In fact, the Fed Funds futures are beginning to price in the possibility of a rate cut. The bottom line is that rates will be lower for longer. FWIW, Bill Gross thinks the upside is limited in US bonds. While Brexit will probably dampen global growth slightly, it shouldn’t be a catalyst to push the US into a recession. The biggest beneficiaries will be tourists who want to visit the UK this summer. The biggest losers will be US manufacturers who compete with UK manufacturers and become less competitive due to the sell-off in the pound. In other words, the economic fall-out to the US will probably be pretty limited. Perhaps US stocks were looking for a reason to sell off, but the effect of Brexit on US corporate earnings should be pretty small.

In terms of the mortgage markets, the TBA market (which sets mortgage rates) really didn’t have much of a move on Friday. Ginnie II 3.5s were up about 1/4 of a point, which is more or less normal volatility. Fannie TBAs were up 3/8 of a point, which again is more or less normal volatility. Historically, TBAs have lagged movements in the bond markets, and days like Friday absolutely annihilate people who hedge MBS interest rate risk. So, while their portfolio goes up in value, their interest rate hedges lose a lot more than their book gains, so it ends up pressuring TBA pricing, which in turn prevents mortgage rates from moving as low as you think they should go. If the 10 year stays right here, expect mortgage rates to catch up only gradually over a week or even two. Note that the Bankrate US 30 year fixed rate mortgage had been lagging the moves downward in rates already, even before the big move on Friday. It dropped 11 basis points on Friday.

Construction wages are rising faster than the rest of the industry, however they are really just playing catch-up. It will make new houses marginally more expensive, however falling mortgage rates will cushion the blow.