Morning Report: FOMC decision due at 2:00 pm EST 7/27/16

Vital Statistics:

Last Change
S&P Futures 2168.3 5.0
Eurostoxx Index 343.8 2.5
Oil (WTI) 42.8 -0.2
US dollar index 88.0 0.2
10 Year Govt Bond Yield 1.56%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.53

Markets are calm ahead of the FOMC decision this afternoon. Bonds and MBS are up small.

The FOMC decision is set to come out around 2:00 pm EST today. Beware of locking around that time. Since there is no press conference scheduled, the odds of a rate hike are extremely low. Investors will parse the language of the statement closely. Note the next time Janet Yellen speaks will be in late August at Jackson Hole, so markets will have all sorts of time to fret without any sort of real input from the Fed.

Mortgage applications fell 11% last week as purchases fell 3% and refis fell 15%. Rates rose 2 basis points last week, but they increased 17 basis points the week before.

Durable Goods orders fell 4% MOM and are down 6.4% YOY. Ex transportation they were down .5% MOM and 3.6% YOY. Capital Goods orders fell as well. For all the talk about an acceleration in the economy, these numbers are a warning sign.

Pending Home sales rose 0.2% last month. Tight inventory remains a problem, and the increase was mainly due to the Northeast which doesn’t have the inventory problem we see on the West Coast. Lawrence Yun, NAR’s chief economist had this to say: “With only the Northeast region having an adequate supply of homes for sale, the reoccurring dilemma of strained supply causing a run-up in home prices continues to play out in several markets, leading to the last two months reflecting a slight, early summer cooldown after a very active spring,” he said. “Unfortunately for prospective buyers trying to take advantage of exceptionally low mortgage rates, housing inventory at the end of last month was down almost 6 percent from a year ago,1 and home prices are showing little evidence of slowing to a healthier pace that more closely mirrors wage and income growth.”

Lost in all the focus on falling / negative bond yields is the rise in LIBOR. LIBOR is a short-term rate that is the basis for lots and lots of financial products, from everything to auto loans to ARM mortgages. New money market regulations have been pushing up LIBOR. The explanation is really inside-baseball sort of stuff, but just be aware as this does affect ARM pricing.
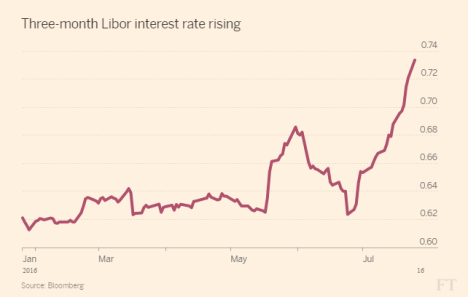
LIBOR

Just one more note on ARMS – in this interest rate environment, where long term rates are steady / falling and short term rates are rising – ARMs are unattractive for borrowers. If there are any borrowers out there who still have ARMs now is the time to refi to a 30 year fixed rate mortgage.

Fannie Mae has announced changes to its 3% down HomeReady program.

Changes that go into effect immediately include:

  • Income limits have been raised to 100 percent of area median income (AMI) in all areas except for low income market tracts which have no limit. The company says this will expand access to affordable credit and also make it easier for lenders to determine eligibility for the loans.
  • The occupant borrower will now be allowed to own other residential properties.
  • Homeownership education courses that fulfill the HomeReady mortgage requirement have been expanded to include one-on-one pre-purchase advising from HUD-approved providers. Fannie Mae will offer lenders a $500 credit to encourage borrowers to take advantage of this option. Homebuyer education will continue to be available through Framework, Fannie Mae’s education partner.

The requirement for homeownership education has been removed for limited cash-out refinances and borrowers for loans secured by two- to four-unit properties will no longer be required to take landlord education although homeownership education will remain a requirement.

  • The Seller Guide announcing the above changes also noted that Fannie Mae expects to make additional enhancements later this year, including:
  • Allowing a maximum loan-to-value up to 97 percent on limited cash-out refinance transactions in Desktop Underwriter (DU) if the existing mortgage is owned or securitized by Fannie Mae.
  • Expanding current HomeReady eligibility for buydowns and adjustable-rate loans to include three- to four-unit properties.

Adding additional incentives for the one-on-one homeownership counseling implemented with the current changes.

The strange, strange world of jumbo lending in the Bay Area. Lenders are now taking into account stock and stock option compensation for determining whether a borrower can afford a mortgage. In a place where the median house price is $1.13 million, lenders have to get creative in finding ways to get working stiffs into a home. I guess if real estate prices and the stock market continue to hit new highs, everything is okay until the music stops.

Speaking of crazy lending, car loans are the new subprime, with 8 year car loans at mortgage rates. As investors reach for yield, they inevitably take more risk. That said, fears of this causing a 2008 style calamity are overblown. Residential real estate bubbles are a fundamentally different animal than this sort of thing.

If you missed the Democratic Convention last night, here is the cliff notes version:

DNC convention.PNG

Morning Report: New Home Sales climb 7/26/16

Vital Statistics:

Last Change
S&P Futures 2163.0 -0.3
Eurostoxx Index 341.8 2.0
Oil (WTI) 42.5 -0.6
US dollar index 88.1 0.2
10 Year Govt Bond Yield 1.56%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.53

Markets are flattish on no real news. Bonds and MBS are up small.

New Home Sales rose to 592k in June, much higher than the Street expectation. The median new home price rose 6.1% YOY to $306,700. There is about 4.9 month’s worth of inventory right now, compared to 5.1 months in May.

Consumer confidence slipped in June to 97.3 from 97.4.

Home prices continued to appreciate in May, according to the Case-Shiller Home Price Index. “Home prices continue to appreciate across the country,” says David M. Blitzer, Managing Director and Chairman of the Index Committee at S&P Dow Jones Indices. “Overall, housing is doing quite well. In addition to strong prices, sales of existing homes reached the highest monthly level since 2007 as construction of new homes showed continuing gains. The SCE Housing Expectations Survey published by the New York Federal Reserve Bank shows that consumers expect home prices to continue rising, though at a somewhat slower pace.”

The FOMC starts its meeting today, and we will get the decision tomorrow around 2:00 pm. Here is a good take on how to parse the FOMC statement. The key will be the characterization of the economy in the first paragraph. If the Fed notes an improvement in the economy since June, then that could be interpreted as a step towards hiking in September.

Is wage growth beginning to pick up?  One key will be the employment cost indicator, which will be released on Friday. The ECI was depressed in the second quarter of 2015, so we should get a mid 2% YOY comparison. Is that enough to convince the Fed that inflation is returning to their 2% target? Possibly, but the Fed has said they are going to let the labor market run hot for a while. Don’t forget, even if the Fed hikes rates 25 basis points this year, monetary policy is still at emergency-level accommodation. Note that many indicators are showing that the economy is recovering well, and the doves will be on the defensive at some point.

Interesting article about how it is so hard to make affordable housing affordable. Trying to build in an urban area and hold rents down to $500 a month is impossible without government subsidies. Regulatory issues like open space set asides also do not help. This is also an issue with starter homes, especially in high cost urban areas on the West Coast. By the time you build and comply with all the regulations, you are looking at a $500k + price tag, which is way out of the range of the typical first time homebuyer.

Morning Report: Fed week 7/25/16

Vital Statistics:

Last Change
S&P Futures 2167.0 -0.3
Eurostoxx Index 341.8 2.0
Oil (WTI) 43.5 -0.7
US dollar index 88.1 0.2
10 Year Govt Bond Yield 1.57%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.53

Stocks are flattish this morning on no real news. Bonds and MBS are flat as well.

The big event this week will be the FOMC meeting on Tuesday and Wednesday. The Fed will probably stand pat, however it will be interesting to see how Brexit is treated. The markets have become much more sanguine about the event and the Fed Funds futures have reacted accordingly.

The other thing to watch with the Fed is their stance on QE, and re-investing maturing proceeds back into the market. The Fed’s buying has supported the mortgage market and their exit would cause mortgage rates to rise at the margin.

The Democratic National Convention opens today after a WikiLeaks document dump over the weekend. It shows the Clinton campaign coordinated with the DNC (which is supposed to be neutral) to undermine Bernie Sanders’ campaign. It also showed how much the media gets its marching orders straight from the Democratic Party. Debbie Wasserstein-Schultz resigned from her position as head of the DNC and immediately joined the Clinton campaign. Protesters are gathering in 100 degree heat in the City of Brotherly Love.

Morning Report: Home prices are stretched versus incomes again 7/21/16

Vital Statistics:

Last Change
S&P Futures 2173.0 9.0
Eurostoxx Index 339.4 2.0
Oil (WTI) 44.9 -0.2
US dollar index 88.0 0.2
10 Year Govt Bond Yield 1.62%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.52

Markets are higher this morning after the ECB hinted at further stimulus down the road. Bonds and MBS are down.

The Fed Funds futures are now pricing in a 47% chance of 1 more rate hike this year. That probability was 20% about 10 days ago. That is what has been driving the 10 year yield back up.

We have a bunch of economic data this morning.

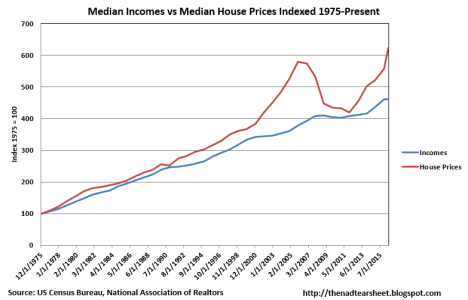
Existing home sales rose 1.1% to an annual pace of 5.57 million, according to the NAR. This is up 3% YOY, and is the highest level since February 2007. All regions except the Northeast reported an increase. The median home price rose 4.8% to $247,700. This puts the median home price to median income ratio at 4.3x, which is extended versus its historical range of 3.2x – 3.6x. Of course interest rates are influencing this as well, but it looks like home prices are beginning to run a little too far, too fast. Below is a chart of incomes versus home prices, indexed back to 1975. This doesn’t really speak to bubble behavior – it speaks to the caution out of the homebuilders who are reluctant to add supply. The current inventory of houses for sale is about 4.6 month’s worth, while a balanced market is about 6.5 months.


Median house price to median income indexed


Initial Jobless Claims slipped 1,000 to 253k last week. We should be seeing an increase given this is the season for re-tooling factories, however we aren’t, and we are hitting all-time lows for initial jobless claims, which goes back to the 1960s. To put it in perspective, the last time initial jobless claims were around these levels, we had a military draft.

House prices rose 0.2% month-over-month in May and are up 5.2% YOY, according to the FHFA House Price Index. The East Coast continues to lag while the Left Coast is still hitting high single digit YOY appreciation. The index as a whole has recouped all of the losses from the real estate bust. Remember, the FHFA House Price index only looks at houses with a conforming mortgage, so it ignores the extremes of both ends of the spectrum – distressed and jumbo.

The Philly Fed index fell to -2.9 while the Chicago Fed National Activity Index rebounded to +.15. The Bloomberg Consumer Comfort Index slipped again to 42.9, while the Index of Leading Economic Indicators rose to 0.3%.

PulteGroup announced earnings this morning, beating estimates and announcing a new value creation plan. They will buy back up to $1.5 billion in stock over the next 18 months, and reduce land investment. This is a bit of a surprise given that revenues increased 41%, and average selling prices increased 11%. Pulte has been targeting the first time homebuyer pretty aggressively, and given the pent-up demand, they probably should be investing in the business instead of buying back stock.

D.R. Horton also announced this morning, with earnings coming in line with expectations. Revenues increased 9% and earnings increased 13%.

Morning Report: Vastly different forecasts for the 10-year 7/20/16

Vital Statistics:

Last Change
S&P Futures 2164.0 -3.0
Eurostoxx Index 339.4 2.0
Oil (WTI) 44.4 -0.2
US dollar index 88.0 0.2
10 Year Govt Bond Yield 1.57%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.52

Stocks are lower this morning on no real news. Bonds and MBS are flat

Mortgage Applications fell 1.3% last week as purchases fell 2% and refis fell 1%. Considering that the 10 year bond yield picked up 17 basis points last week, those are surprisingly good numbers, however there could be comparison issues with the 4th of July week.

Brexit has created some winners and losers in the real estate business. Winners: those in the mortgage origination business and borrowers who benefit from lower mortgage rates. Losers: high-end developers who rely on foreign money and the private label securitization market, which needs higher yields to attract interest in non-guaranteed paper.

Strategist Komal Sri-Kumar, who has been right as rain about the rally in Treasuries this year (when everyone else was predicting higher yields) has an eye-popping forecast for the 10 year: 90 basis points. He sees global growth slowing and believes inflation will be nowhere to be found.

On the other side of the trade, SocGen believes fair value in the 10 year is 1.95%, and sees a 1% chance of the 10 year hitting 1.1% this year. Their original model was looking for high 2%. In fact, most strategists were looking for 2.75% of so on the 10 year by the end of the year. No one can make heads or tails of the bond market right now.

We obviously have a bubble in sovereign debt, and the world is assuming inflation and growth are never, ever coming back. In other words, it is just another “its different this time” argument. IDTT are the 4 deadliest words in investing. Will it end with a cataclysmic top like we had in stocks in 2000 and residential real estate in 2006? Who knows? The last time we had interest rates this low was the 1930s under the gold standard. Today, we have negative rates under the PhD standard. This is uncharted territory and isn’t in the economics textbooks.

What will be the catalyst to get growth and inflation growing again? It should be housing. Household formation was depressed during the Great Recession and has been coming back. Housing starts are still lagging, however. Throw in obsolescence and you have a housing shortage, which is driving up prices. That pent-up demand is going to get released as the Millennials age, and that is going to push housing starts up to where they should be, around 2 million units a year. Compare housing starts to household formation over the past few years.

Tim Duy, a very smart Fed-watcher suggests the Fed doesn’t have the room to raise rates given that the yield curve is flattening. A flat yield curve (where long-term rates are close to short term rates) is generally bad for the economy, especially the banking system.  He suggests that the process of normalization start with shrinking the Fed’s balance sheet. Since the Fed cut rates to zero first, and then instituted quantitative easing, the Fed should undo quantitative easing first and then raise rates. In fact they are doing the opposite. The first step would be to stop re-investing maturing proceeds and let the debt run off. Ideally, the Fed should be hitting bids in the Treasury market, selling overpriced paper, but they have to figure out how to offset the contractionary effect it will have on the money supply.

Morning Report: Glass-Steagall is a solution in search of a problem 7/19/16

Vital Statistics:

Last Change
S&P Futures 2167.0 5.0
Eurostoxx Index 336.3 1.0
Oil (WTI) 45.4 0.2
US dollar index 87.4 0.1
10 Year Govt Bond Yield 1.56%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.52

Stocks are higher this morning on no real news. Bonds and MBS are up small.

Housing starts came in at 1.19 million units, the highest since February. May was revised lower. Building Permits rose to 1.15 million units. Starts seem to have found a level here at 1.2 million per year, which is still depressed.  Housing starts have historically averaged closer to 1.5 million units (even before the real estate bubble) and inventory remains tight. This is helping push up prices, but the side effect is that the first time homebuyer remains on the sidelines due to affordability issues. Given the tight inventory out there, starts should be closer to 2 million per year, and that makes a huge difference in economic growth.

Now that Brexit hasn’t caused the world to end, the Fed is back to thinking about hiking rates again. The Fed Funds futures are now pricing in a 45% chance of a rate hike this year versus a 20% chance last week. Next week’s FOMC meeting just went from being a sleeper to potentially big. It might also mean that people who are waiting for a 1.37% 10-year bond yield to refinance might be waiting a while. The big driver will be overseas rates, and if European bonds head back into negative territory, US yields will follow. Absent the overseas influence, rates would be a lot higher in the US than they are.

Note that Morgan Stanley is calling for a 1% 10-year yield by the end of the year.

The Republican platform now includes reinstating Glass-Steagall which would break up the big banks. I guess the idea is that JP Morgan would split back into JP Morgan and Chase, Citi would spin off Smith Barney, and Bank of America would spin off Merrill. FWIW, Glass-Steagall is a solution in search of a problem, and it really had nothing to do with the financial crisis.

For a quick history lesson, Glass-Steagall was instituted during the Great Depression, but the reason for it is largely forgotten. At the beginning of the Depression, investment banks were choking on failed underwritings. In an underwriting, Company XYZ comes to an investment bank and says “I want to borrow $100 million by issuing bonds.” The investment bank gives Company XYZ $100 million and takes the bonds. The investment bank now has to sell these bonds to the public in order to get their money back. In the early 30s, there were no buyers for bonds, so the investment banks were stuck with a lot of stock and bond issues they couldn’t sell. Since these investment banks also owned commercial banks and insurance companies, they basically “sold” the failed underwritings to their subsidiaries who bought them at their inflated full value, not market value. When these banks and insurance companies failed, the regulators saw that much of their assets were worthless bonds bought from the parent investment bank. Thus Glass-Steagall was born – it prohibited investment banks from using their captive commercial banks and insurance companies as a buyer of last resort for failed underwritings. All transactions had to be arm’s length after that.

Fast forward to the late 1990s. Plain vanilla derivatives like currency and interest rate swaps were a huge business as Corporate America was doing more and more business overseas. The arena for these derivatives was highly competitive, and big foreign banks like Credit Suisse, Deutsche Bank, Barclay’s and Nomura were able to offer much better rates to Corporate America than Goldman or Merrill because they had access to cheap capital: deposits. Banks like Nomura could borrow for free, while Morgan Stanley had to borrow at LIBOR. Washington saw that “Wall Street” was beginning to mean foreign banks and not US banks. The rest of the world doesn’t separate investment banking and commercial banking. Indeed, the rest of the world doesn’t even recognize a difference. Washington decided that Glass Steagall was handicapping US banks versus the international competition (and it was). And thus Glass Steagall was repealed.

It is important to realize that the financial crisis was not the result of JP Morgan selling CDO squareds to Chase. Nor was Citi selling crap paper to Travelers. The financial crisis was the result of a residential real estate bubble, which are the Hurricane Katrinas of banking. Banking systems almost never survive a nationwide real estate bust, derivatives or no derivatives. See the busts in Japan and Sweden in the early 90s, and watch what happens in other places with massive bubbles. I guess the hope is G-S can address too big to fail, however if a hedge fund nearly brought down the system (LTCM), then an investment bank failure will as well. I am sure plenty in Washington are licking their chops at further regulating the banks and using them as a policy tool for social engineering. This is the model for many European banks.

If GS gets re-instated and the big banks break up, you could see a similar effect to when the government busted up AT&T in the 80s and investors cleaned up on all the baby bells.

Anyway, re-installing Glass Steagall might be politically popular, but it is a solution in search of a problem.

Morning Report: Big change in the market’s forecast for rate hikes 7/18/16

Vital Statistics:

Last Change
S&P Futures 2158.0 5.0
Eurostoxx Index 338.8 1.0
Oil (WTI) 45.3 -0.6
US dollar index 87.4 0.1
10 Year Govt Bond Yield 1.57%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.52

Markets are higher this morning despite the coup attempt in Turkey over the weekend. Bonds and MBS are down.

We have a relatively data-light week coming up, at least as far as market-moving data. We will get a lot of housing related data however, with the NAHB Homebuilder sentiment, housing starts, building permits, the FHFA House Price Index and existing home sales. We will also get earnings from Pulte, D.R. Horton, and NVR.

The Republican National Convention kicks off today in Cleveland. The #NeverTrump crowd is still trying to find a way to derail his nomination, but without a candidate it looks impossible. Mainstream Republicans are largely avoiding the convention altogether, so expect a bunch of celebrities to kill time with speeches. The protests from the left will probably be the most interesting part, as “law-and-order” promises to be the big theme of the convention.

Bond yields rose 17 basis points last week as US economic data came in stronger than expected, and global yields rose. The German Bund hit 0% late last week after starting the week at a yield of -18 basis points. As people realize Brexit didn’t cause the end of the world, risk appetites returned and with it, expectations of a rate hike. The Fed Funds futures are now pricing in a 44% chance of a rate hike this year, from 20% a week ago. That is huge, and indicates this is more than just a pull back in a market that went too far too fast.

That new forecast for rate hikes makes next week’s FOMC meeting all that more important. A week ago, I would have said it wouldn’t be market-moving. Now I am not so sure.

Are we in danger of living in a new housing bubble? Not really. Housing is expensive because inventory is tight, not because of loose lending standards.

Homebuilder sentiment slipped in July to 59 from 60 the prior month.

Morning Report: Capping off a terrible week for bonds 7/15/16

Vital Statistics:

Last Change
S&P Futures 2160.0 3.0
Eurostoxx Index 337.5 -1.0
Oil (WTI) 46.1 0.4
US dollar index 87.0 0.1
10 Year Govt Bond Yield 1.57%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.49

Markets are higher this morning in spite of a massive terrorist attack in France. Bonds and MBS are down.

Lots of stronger-than-expected economic data this morning

The Consumer Price index rose 0.2% versus expectations of 0.3%. On an annualized basis, it rose 1%. Ex food and energy, it is up 2.3% YOY. Note the Fed prefers the Personal Consumption Expenditure index and not the CPI.

Retail sales came in stronger than expected – up 0.6% versus expectations of 0.1%. Retail sales had a sluggish start to the year, which partly drove the lousy 1.1% Q1 GDP growth rate. I wouldn’t be surprised to see some strategists and the Fed take up Q2 GDP estimates on this number.

Industrial Production rose 0.6% last month and manufacturing production rose 0.4%. Both numbers beat estimates. Capacity Utilization rose to 75.4%, again better than expectations.

It is hard to believe, but the 10 year bond has picked up 20 basis points in yield since Monday morning. This is the biggest weekly loss in a year.  Whether that was “the top” remains to be seen: markets can have ferocious sell-offs in the context of a bull market. At the end of the day, the US is going to be driven by foreign bond trading. The German Bund went from -18 basis points on Monday to nearly 0% this morning.

Larry Fink of Blackrock says that a .75% 10-year yield wouldn’t surprise him.

Wells Fargo reported a 4% YOY increase in net income for the second quarter. Mortgage origination was up 2% YOY. Citi beat numbers.

Morning Report: Professionals are exiting the foreclosure market 7/14/16

Vital Statistics:

Last Change
S&P Futures 2162.0 16.0
Eurostoxx Index 338.8 3.0
Oil (WTI) 45.6 0.8
US dollar index 86.9 -0.2
10 Year Govt Bond Yield 1.53%
Current Coupon Fannie Mae TBA 103.2
Current Coupon Ginnie Mae TBA 104.2
BankRate 30 Year Fixed Rate Mortgage 3.47

Stocks are higher this morning after the Bank of England declined to cut interest rates. Bonds and MBS are down

Initial Jobless Claims fell to 254k in a holiday shortened week.

Consumer comfort increased last week to 44.7 from 43.5

Producer prices increased 0.5% in June, versus expectations of a 0.3% increase. On a YOY basis, they increased 0.3%. Higher energy prices drove the increase, however we are a long way from seeing true inflationary pressure. Inflationary pressure won’t build until we start seeing wage inflation, and there we have a dichotomy: Firms with highly skilled labor are having to raise wages to keep top talent, while technology is depressing wages for people in jobs that will eventually be replaced by robots and expert systems. Note the Fed’s Beige Book characterized wage growth as “modest to moderate.” This is Fed-speak for “almost imperceptible.” That said, wage growth appears to have broken free from post-crash 2% level and is beginning to register in the mid 2%s.

JP Morgan reported better-than-expected earnings this morning. Mortgage banking revenue was up 2% QOQ and 5% YOY. Portfolio growth and and production revenue increases were offset by lower servicing revenues. The stock is up 2.5% pre-market.

Has the big rally in prices for foreclosed homes run its course? RealtyTrac suggests that it may have, as more and more “mom and pop” investors are winning foreclosure auctions and the professionals are pulling back from the market. Professional investors accounted for almost 10% of all home purchases in the depths of the housing bust, now they account for about 2.5%. There are some fears that this signals another housing bubble. FWIW, home prices are stretched compared to incomes, however that ignores the effect low interest rates are having. Housing bubbles are rare things – prior to the 2006 bust the last bubble in real estate popped in the 1920s. Anyone reading this will probably never see another one.

Speaking of foreclosures, the people who got foreclosed on early in the housing bust basically missed out on about 10 years of house price appreciation. To add insult to injury, many sold into a cheap housing market (to the professional investors mentioned above) and moved into expensive rentals (managed by the professional investors above).

Earnings season has just started, and the S&P 500 is at record highs. Is this rally for real? It will depend on earnings, which have been declining the past several quarters. The other thing that will drive the market is share buybacks. With the world’s central banks driving down interest rates, they are lowering Corporate America’s cost of capital. Many companies are choosing to issue debt to retire stock. This move is essentially a no-brainer for corporate CFOs who don’t have much in the way of profitable expansion opportunities. When you can issue debt for 4% to retire stock with a cost of capital of 10%, you do it.

The flip side of ultra-low interest rates is a boring, risk-averse economy. This has been a conscious choice among policy-makers (remember “Make banking boring again”?). Of course a major problem is that usually global economies de-leverage after asset bubbles, but that hasn’t happened this time around. As global debt levels rise, they act as sand in the gears for the economy, slowing it down. Ironically, the policy-makers who drove this are concerned first and foremost about inequality, and the unintended consequence of their policy has been an economy that gooses asset prices and retards business formation (which means less jobs). This increases inequality even further – the opposite of what they intended.

Of course the endgame for these policies is Japan, which is discussing new fiscal measures to try and pull their economy out of a 25-year bust.

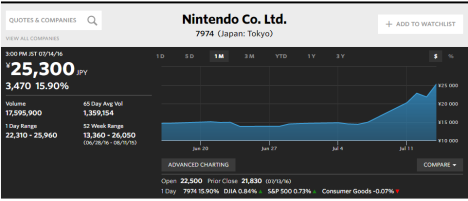
Speaking of Japan, do you have kids that are playing Pokemon Go? (the latest craze). This has really caught investors by surprise: Nintendo stock is up 76% over the past week.

Nintendo

Morning Report: Bond yields rise on a weak 10 year auction 7/13/16

Markets are higher this morning on no real news. Bonds and MBS are up.

Bond yields rose dramatically yesterday on hopes of future stimulus. The 10 year was trading around 1.52% yesterday after lower than expected demand at a Treasury auction. Yesterday, Germany auctioned 10 year bunds at a yield of -.05%. Yields worldwide are heading lower this morning. Note that MBS are still largely ignoring the volatility, although we did see some reprices yesterday.

Mortgage Applications rose 7.2% last week according to the MBA. Purchases were flat, while the refi index rose 11%. Note this was a short holiday week and we still saw a big increase in refis.

Import prices rose 0.2% MOM and are down 4.8% YOY. The strength in the US dollar (or as Bill Gross says, the cleanest dirty shirt) is driving the drop. Yet another reason why the Fed can’t seem to find inflation anywhere.

Bernie Sanders made it official yesterday and endorsed Hillary Clinton. Meanwhile, Mitt Romney and Jeb Bush are considering backing Libertarian Gary Johnson. The GOP convention is this weekend, and promises to be a spectacle between the #NeverTrump crowd and the expected protests from the left. Here is how the #NeverTrump crowd can block his nomination.

The Atlanta Fed is now estimating that US GDP growth increased at a 2.3% pace in the second quarter. This is a drop of 0.1% from their estimate a week ago.

James Bullard believes that Brexit will have almost no US impact. Loretta Mester said more or less the same thing as well. The main effect will probably be a stronger dollar and lower interest rates in the US.

One of the biggest effects of the financial crisis may be rolling off: Those who had short sales and foreclosures in 2009 – 2010 are reaching the end of the 7 year no mortgage period and become eligible to borrow again.