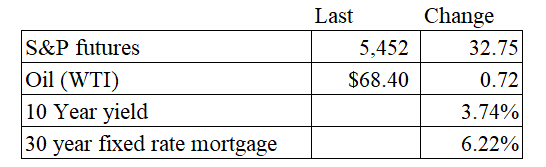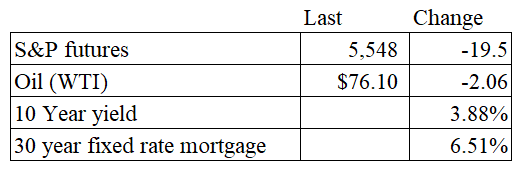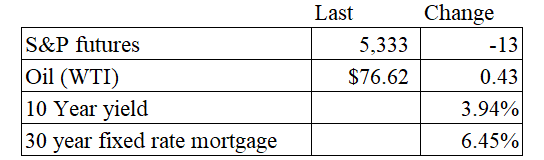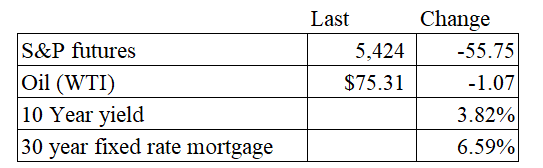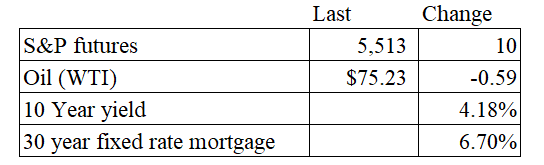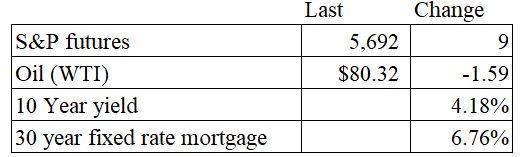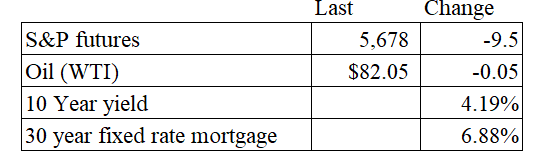Stocks are higher this morning after getting roughed up last week. Bonds and MBS are down.
The week ahead will be dominated by inflation data with the consumer price index on Wednesday and the producer price index on Thursday. We are in the quiet period ahead of the FOMC meeting next week, so there won’t be any Fed speakers.
Fed Governor Christopher Waller said that the “time has come” to begin cutting rates. “If the data supports cuts at consecutive meetings, then I believe it will be appropriate to cut at consecutive meetings,” Waller said in remarks prepared for delivery at the University of Notre Dame. “If the data suggests the need for larger cuts, then I will support that as well. I was a big advocate of front-loading rate hikes when inflation accelerated in 2022, and I will be an advocate of front-loading rate cuts if that is appropriate.”
New York Fed President John Williams also supports cutting rates: “It is now appropriate to dial down the degree of restrictiveness in the stance of policy by reducing the target range for the federal funds rate,” Williams said, in a speech prepared for delivery to the Council on Foreign Relations.
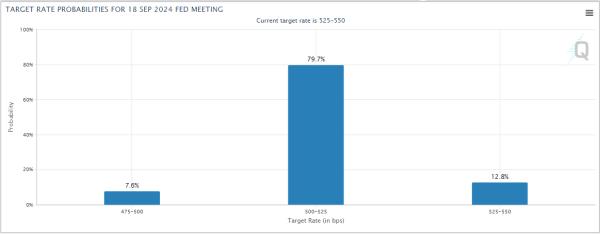
The base case for next week continues to be 25 basis points. Right now, the Fed Funds futures see a 75% chance of a 25 basis point cut and a 25% chance of a 50 basis point cut. The jobs report showed the labor market is softening, but not deteriorating which means the Fed doesn’t need to move with alacrity.
Stocks are higher this morning after another benign inflation report. Bonds and MBS are down small.
Personal incomes rose 0.3% MOM in July, according to the Bureau of Economic Analysis. This was 0.1% above expectations. Consumption rose 0.5% MOM, which was in line with expectations.
The PCE Price Index rose 0.2%, in line with expectations, but was above May and June. The core rate, which excludes food and energy rose 0.2%, which was flat with June and in line with expectations. On an annual basis, the headline number rose 2.5% and the core rate rose 2.6%.
Bonds sold off slightly, and the Fed Funds futures now handicapping a 70% chance of a 25 basis point cut and a 30% chance of a 50 basis point cut. The strong spending number probably means the Fed will choose the less aggressive option.
Pending Home Sales fell 5.5% in July, according to NAR. The index fell to the lowest level on record, which goes back to 2001 when the index first started. “A sales recovery did not occur in midsummer,” said NAR Chief Economist Lawrence Yun. “The positive impact of job growth and higher inventory could not overcome affordability challenges and some degree of wait-and-see related to the upcoming U.S. presidential election. In terms of home sales and prices, the New England region has performed relatively better than other regions in recent months,” added Yun. “Current lower, falling mortgage rates will no doubt bring buyers into market.”
Affordability did improve somewhat in July, according to the MBA. The national median payment for purchase applicants fell from $2,167 to $2,140. “Homebuyer affordability conditions improved for the third consecutive month as rates below 7 percent and rising housing inventory continue to bode well for prospective homebuyers,”,” said Edward Seiler, MBA’s Associate Vice President, Housing Economics, and Executive Director, Research Institute for Housing America. “MBA is expecting that slower home-price appreciation, coupled with lower rates, will ease affordability constraints and lead to increased activity in the housing market.”
Stocks are higher this morning as we await Jerome Powell’s speech at Jackson Hole. Bonds and MBS are down.
Powell is set to speak at 10:00 am this morning. The FOMC minutes indicated that unless something dramatic happens, the Fed is set to cut interest rates at their September meeting. Powell will probably reiterate the Fed’s data-dependent mindset and confirm that a September rate cut is probably in the cards. Note that Kansas City Fed President Tom Harker said the Fed is ready to start cutting on CNBC yesterday. “I think it means this September we need to start a process of moving rates down,” Harker told CNBC’s Steve Liesman during a “Squawk on the Street” interview. Harker said the Fed should ease “methodically and signal well in advance….Right now, I’m not in the camp of 25 or 50. I need to see a couple more weeks of data,” he said.
Existing home sales rose 1.3% in July to a seasonally adjusted annual pace of 3.95 million, according to the National Association of Realtors. This snaps a 4 month losing streak which started in March. On a year-over-year basis, sales fell 2.5%. “Despite the modest gain, home sales are still sluggish,” said NAR Chief Economist Lawrence Yun. “But consumers are definitely seeing more choices, and affordability is improving due to lower interest rates.”
Total housing inventory rose 0.8% to 1.33 million units, which is up 19.8% compared to a year ago. The median home price rose to $422,600, up 4.2% compared to a year ago.
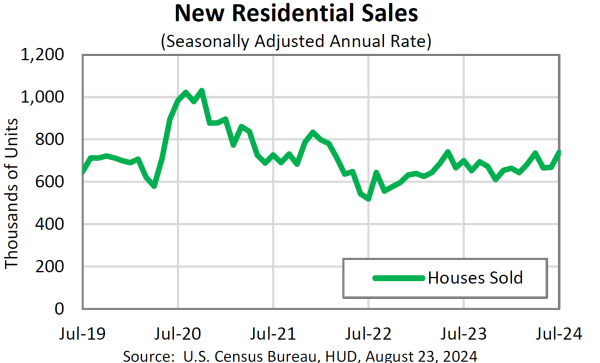
New Home sales rose by more than expected in July, increasing 10.6% to a seasonally adjusted annual rate of 739,000. This is still down about 5.8% compared to last year.
The CFNAI is sort of a meta-index which gives a high-level view of the state of the economy. While the numbers don’t indicate recessionary territory, it does show a softening economy.
Stocks are lower this morning on no real news. Bonds and MBS are up.
Housing starts declined to a seasonally-adjusted annual rate of 1.238 million. This is a 7% decline from a downwardly-revised June rate of 1.329 million, and down 16% compared to a year ago. Building permits fell 4% MOM and 7% YOY. Starts are at the lowest levels since May of 2020.
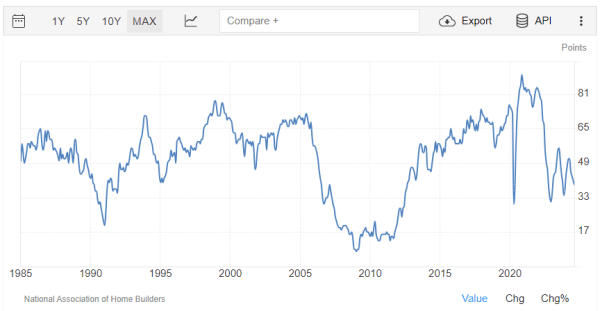
Homebuilder confidence declined in August as we await interest rate cuts. This is a decline from July and the lowest level since December last year. “Challenging housing affordability conditions remain the top concern for prospective home buyers in the current reading of the HMI, as both present sales and traffic readings showed weakness,” said NAHB Chairman Carl Harris, a custom home builder from Wichita, Kan. “The only sustainable way to effectively tame high housing costs is to implement policies that allow builders to construct more attainable, affordable housing.”
Homebuilder confidence is still stuck at the levels we saw during the post-bubble housing bust.
Mortgage delinquencies ticked up in the second quarter, according to the MBA. The delinquency rate rose 3 basis points QOQ to 3.97%. This is up 60 basis points compared to a year ago. “Mortgage delinquencies increased across all product types compared to this time last year,” said Marina Walsh, CMB, MBA’s Vice President of Industry Analysis. “While delinquencies are still low by historical standards, the recent increase corresponds with a rising unemployment rate, which has historically been closely correlated with mortgage performance.”
Industrial production fell 0.6% in July, according to the Federal Reserve. This was well below Street expectations. Manufacturing production fell 0.3%, which was in line with expectations. Capacity utilization fell to 77.8%. We have known the manufacturing economy is struggling, and this report shows no indication of a turnaround.
Stocks are lower as we finish up a turbulent week for markets. Bonds and MBS are up.
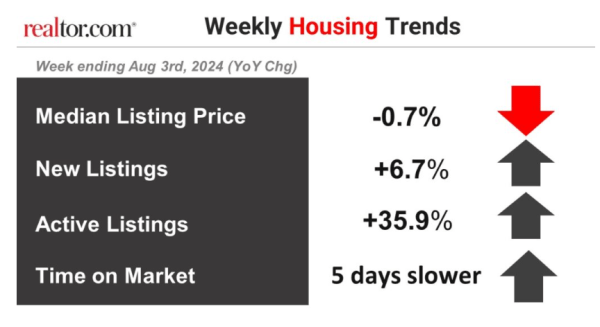
Active for-sale inventory rose 36% YOY, according to Realtor.com. The median listing price is down 0.7% YOY, while year-to-date listing prices are flat. Overall, we are getting to a more balanced home market.
The total value of US residential real estate rose to $49.6 trillion, according to research from Redfin. “The value of America’s housing market will likely cross the $50 trillion threshold in the next 12 months as there are not enough homes being listed to push prices down,” said Redfin Economics Research Lead Chen Zhao. “Mortgage rates have started falling, but many potential sellers and buyers are waiting to make a move, meaning we are likely to continue seeing a pattern where prices slowly tick up. That’s great news for the millions of American homeowners who see their equity rising, but first-time buyers are going to keep finding it tough to find an affordable home.”
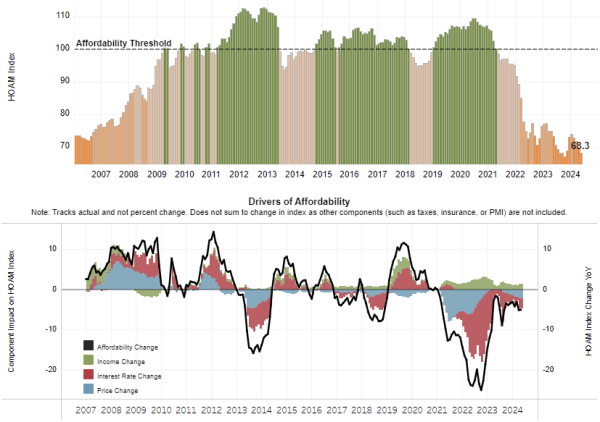
Affordability continues to be terrible however, according to the Atlanta Fed:
Stocks are lower this morning as tech continues to sell off. Bonds and MBS are up big on the disappointing jobs report.
The Bank of England cut rates this morning, which is also helping put global sovereign yields lower.
The economy added 114,000 jobs in July, which was below the Street estimate of 180,000. June was revised downward from 206,000 jobs to 179,000. The unemployment rate ticked up from 4.1% to 4.3%. The number of unemployed people ticked up to 352,000.
Average hourly earnings rose 3.6% YOY, and June’s 3.9% number was revised downward to 3.8%.
Overall, this was a disappointing jobs report, and strengthens the case for a September rate cut. The 10 year bond yield moved decisively lower, falling 14 basis points in the immediate aftermath of the report.
The manufacturing economy continues to deteriorate, according to the ISM Manufacturing Index. The index contracted for the fourth month in a row, and 20 out of the last 21 months. Employment contracted by quite a bit, however prices are still rising. “Demand remains subdued, as companies show an unwillingness to invest in capital and inventory due to current federal monetary policy and other conditions. Production execution was down compared to June, likely adding to revenue declines, putting additional pressure on profitability. Suppliers continue to have capacity, with lead times improving and shortages not as severe. Eighty-six percent of manufacturing gross domestic product (GDP) contracted in July, up from 62 percent in June. More concerning: The share of sector GDP registering a composite PMI® calculation at or below 45 percent (a good barometer of overall manufacturing weakness) was 53 percent in July, 39 percentage points higher than the 14 percent reported in June. Notably, all six of the largest manufacturing industries — Machinery; Transportation Equipment; Fabricated Metal Products; Food, Beverage & Tobacco Products; Chemical Products; and Computer & Electronic Products — contracted in July,” says Fiore.
Private residential construction spending fell for the second straight month in June, largely driven by a decline in single family building. We had been seeing a shift in building from multi-family to single family for the past 18 months or so, but now both are declining.
Stocks are higher this morning as earnings continue to come in. Bonds and MBS are down small.
The US Treasury expects to borrow $740 billion in the third quarter, which is down about $106 billion from the April estimate. It expects to borrow $565 billion in Q4.
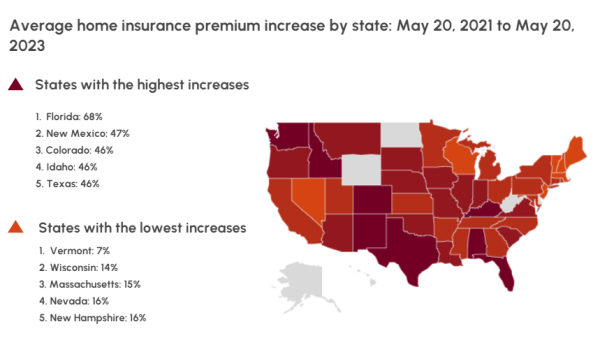
Home insurance premiums rose 21% last year. “The levels of risk and the kinds of hazards that a property can be exposed to are massively changing,” said Carlos Martín, director of the Remodeling Futures program at the Joint Center for Housing Studies of Harvard University.
“And right now there’s a lot of confusion, not just among the homeowners, but also among the insurers about how they should be pricing this actuarially,” he said.
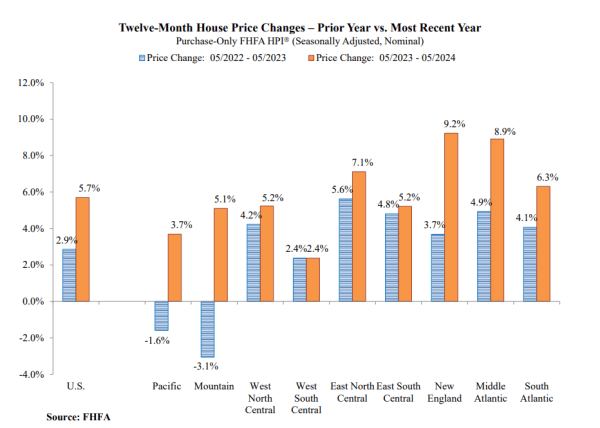
Home price appreciation was flat in May, according to the FHFA House Price Index. Over the past year, home prices rose 5.7%. “U.S. house price movement was flat in May,” said Dr. Anju Vajja, Deputy Director for FHFA’s Division of Research and Statistics. “The slowdown in U.S. house price appreciation continued in May amid a slight rise in both mortgage rates and housing inventory.”
The hot markets of the pandemic era are fading, while the post-2008 laggards are showing the most growth.
The Case-Shiller index showed a 5.9% annual gain in May. “While annual gains have decelerated recently, this may have more to do with 2023 than 2024, as recent performance remains encouraging,” says Brian D. Luke, Head of Commodities, Real & Digital Assets. “Our home price index has appreciated 4.1% year-to-date, the fastest start in two years. Covering the six-month period dating to when mortgage rates peaked, our national index has risen the past four months, erasing the stall experienced late last year. Collectively, all 20 markets covered continue to trade in a homogeneous pattern. Coming into the 2024 presidential election, traditional red states are in a dead heat with blue states, both averaging 5.9% gains annually.
“The Big Apple returned to the top of the leader boards, toppling San Diego from its six-month perch. New York’s 9.4% annual return outpaced San Diego and Las Vegas, by 0.3% and 0.7%, respectively. All 20 markets observed annual gains for the last six months. The last time we saw that long a streak was when all markets rose for three years consecutively during the COVID housing boom. This rally pales in comparison in both duration and annual gains, with above trend growth of 6.2%. The waiting game for the possibility of favorable changes in lending rates continues to be costly for potential buyers\ as home prices march forward.”
Stocks are lower this morning after lackluster earnings from Tesla. Bonds and MBS are flat.
Existing home sales fell 5.4% last month to a seasonally-adjusted annual rate of 3.89 million. “We’re seeing a slow shift from a seller’s market to a buyer’s market,” said NAR Chief Economist Lawrence Yun. “Homes are sitting on the market a bit longer, and sellers are receiving fewer offers. More buyers are insisting on home inspections and appraisals, and inventory is definitively rising on a national basis. Even as the median home price reached a new record high, further large accelerations are unlikely,” Yun added. “Supply and demand dynamics are nearing a balanced market condition. The months supply of inventory reached its highest level in more than four years.”
The median home price rose to 426,900, which was a 4.1% increase from a year ago. The first time homebuyer share fell from 31% to 29%, while investor purchases fell from 18% to 16%. The 3.9 million pace of existing home sales is pretty consistent for a housing recession. To put that number into perspective, we did something like 5.3 million in 2019.
Fannie Mae’s latest housing forecast is out. They see the 30 year fixed rate mortgage ending the year at 6.7%, and gradually falling to 6.2% by the end of 2025. Home price appreciation is expected to remain in the 6% range before falling into the 3% range in 2025. They expect to see 25 basis points in rate cuts this year and another 75 bp in 2025. The core PCE inflation rate is expected to fall to 2.7% this year and 2.3% next year.
PennyMac reported earnings that disappointed the Street. The company acquired $22.5 billion in loans in Q2, which was up 6% on a year-over-year basis. On the earnings conference call, CEO David Spector was asked about when we will start seeing more refi activity:
“Look, I think it’s a gradual decline down. I think if you look at originations post COVID, we kind of jumped and kind of ran through loans with 5% handle. And I think it’s really in the 6% to 7% range where you see a lot — and even north of 7%, where you see a lot of opportunity. It’s going to be — the way I think about it is it’s going to be the slow grind down. I think when rates get to 6.5%, that’s where it really picks up steam.
And I think at 6%, you’re in what I would deem a really robust refi market because it’s not just the existing first that are in the money. You could have loans that are 4% and 5%, taking out debt consolidation, cash refinance to either pay off existing HELOCs or closed-end seconds or other forms of debt. And so it’s really a function of what’s behind the first lien that helps drive the refinanceability. But I continue to believe that it’s 10-year around 3.75%, mortgage is down 50 basis points, that it really is to me, that’s the signal of a true new market or new phase of the refinanceability.”
Mortgage applications fell 2.2% last week as purchases fell 4% and refis rose 0.3%. “Mortgage rates continued to ease, with the 30-year fixed rate dipping to 6.82 percent, the lowest level since February 2024,” said Joel Kan, MBA’s Vice President and Deputy Chief Economist. “Refinance applications were up, driven by conventional and FHA application activity, as some borrowers took the opportunity to act. Furthermore, the conventional refi index was at its highest level since September 2022. Purchase applications decreased as ongoing affordability challenges persist with rates at their current levels and with home-price appreciation still strong in many markets.”
Stocks are higher this morning as earnings continue to come in. Bonds and MBS are up.
Jerome Powell spoke yesterday, and said that the Fed isn’t going to wait until inflation hits its 2% target before easing. “The implication of that is that if you wait until inflation gets all the way down to 2%, you’ve probably waited too long, because the tightening that you’re doing, or the level of tightness that you have, is still having effects which will probably drive inflation below 2%,” Powell said.
He also acknowledged the recent good inflation reports: “What increases that confidence in that is more good inflation data, and lately here we have been getting some of that,” he said.
The September Fed Funds futures now see a rate cut as a certainty.
Retail Sales were flat month-over-month in June, according to the Census Bureau. They rose 2.3% on a year-over-year basis. Since these numbers are not adjusted for inflation, real retail sales fell.
Non-store retailers (i.e. online shopping) and restaurants saw big increases. If you strip out motor vehicles, sales rose 0.4% MOM and if you exclude vehicles and gasoline, they rose 0.8%.
May’s retail sales numbers were revised upward.
When inflation rises, politicians invariably return to one of the dumbest ideas ever put forward – price caps. The idea is that we beat inflation by simply putting a ceiling on prices. Of course this has unintended consequences – the most common is that price controls create shortages – but those effects take time to play out, so it can often give a politician the veneer of “doing something” long enough to get through the election cycle before the unintended effects are visible.
I mention this because the Biden Administration wants to impose rent control nationwide, capping annual price increases at 5%. Of course since this doesn’t affect the costs that landlords bear, it will act to lower cap rates for multi-family developments, which will discourage investment.
Needless to say, industry groups oppose this. The MBA said “There are endless examples in localities in America and around the world that prove that rent control is a counter-productive policy idea that ultimately harms renters by distorting market pricing, discouraging new construction, and degrading the quality of rental housing. While the odds are stacked against this proposal ever passing Congress, a federal rent control law would be catastrophic to renters and our nation’s rental housing market.
The measure requires Congressional approval, so has little-to-no chance of getting passed, let alone in an election year, but it does demonstrate yet again that bad ideas are like Freddy Kreuger – they keep coming back
Stocks are lower despite a good CPI print. Bonds and MBS are up.
Inflation fell 0.1% MOM and 3.0% year-over-year. The Street was expecting an increase of 0.1%, so this was a good surprise for the bond market. Energy prices fell overall, which was offset by increases in shelter. Used Car prices were down 10% on a year-over-year basis.
If you strip out food and energy, prices rose 0.1% month-over-month and 3.1% year-over-year. This was again below expectations. The bond market reacted positively to the report, with the 10 year yield falling over 10 basis points to below 4.2%.
The September Fed Funds futures now see a 80% chance of a rate cut at the September meeting.
Over the past year, we have seen a lot of eye-popping payroll gains, which get revised downward in later months. The average downward revision this year has been 50,000 per month. The typical headline number has been around 275k, so this is a pretty big downward revision. What is going on?
The explanation may be that the numbers are less reliable due to lower response rates. The government estimates payroll growth by sending out questionnaires to businesses who report how many people they hired during the month. It goes out to some 600,000 businesses nationwide.
The response rate fell to a 21 year low in 2023, and has fallen even more this year. If less businesses respond to the survey, the less accurate it is. And with the big downward revisions, the labor market might be worse off than it initially appears.
One recent phenomenon has been the posting of “ghost jobs” which are job listings where the company really doesn’t intend to hire any one. They are there for HR window dressing and resume collection, but they don’t represent real hiring needs. If this behavior is affecting the JOLTs job openings number, then that is another employment statistic that is hiding a broader deterioration in the labor market.