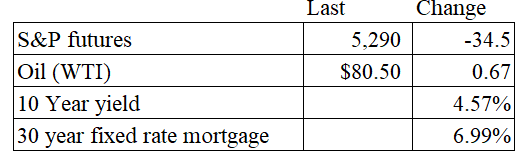Stocks are flattish as we head into earnings season. Bonds and MBS are up small.
The week ahead will have some important events, with Jerome Powell heading to the Hill on Tuesday and Wednesday for his semi-annual Humphrey-Hawkins testimony. We will get the consumer price index on Thursday, and earnings season kicks off with the big banks reporting on Friday.
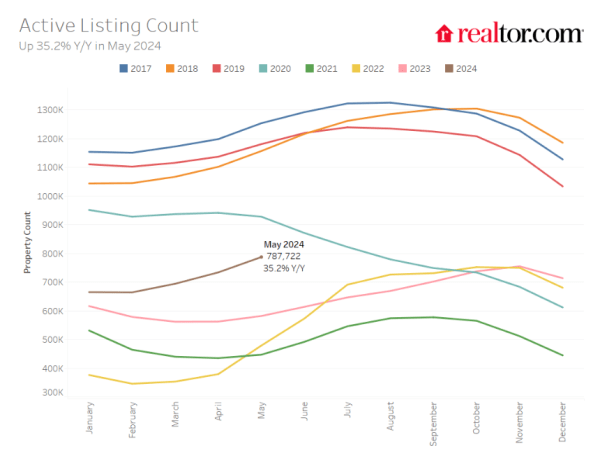
We are seeing for-sale inventory build, however we are still below pre-pandemic levels, according to research from Realtor.com. For-sale inventory rose 35% on a year-over-year basis, however median prices were flat. This might represent a mix shift, as prices rose on price per square foot basis.
While inventory is up 35% YOY, it is still about 35% below 2019 levels. Inventory is getting closer to balance in the South and West, where we saw a building boom over the past few years. Regions which saw muted growth post-2008 (lots of the Northeast and Midwest) are now catching up to the rest of the country.
Mark Zandi has come out in favor of rate cuts.
It’s time for the Federal Reserve to cut interest rates. That’s the message in today’s jobs report for June. Unemployment while still low is steadily notching higher. Job and wage growth while still strong are steadily moderating. The Fed has met its full employment mandate.…
Stocks are lower this morning on no real news. Bonds and MBS are up small.
Jerome Powell is speaking at 9:30 this morning.
The manufacturing economy contracted again in June, according to the ISM Manufacturing Report. “Demand remains subdued, as companies demonstrate an unwillingness to invest in capital and inventory due to current monetary policy and other conditions. Production execution was down compared to the previous month, likely causing revenue declines, putting pressure on profitability. Suppliers continue to have capacity, with lead times improving and shortages not as severe. Sixty-two percent of manufacturing gross domestic product (GDP) contracted in June, up from 55 percent in May. More concerning is the share of sector GDP registering a composite PMI® calculation at or below 45 percent — a good barometer of overall manufacturing weakness — was 14 percent in June, 10 percentage points higher than the 4 percent reported in May.”
Importantly, the prices index fell pretty dramatically, which helps support falling inflation.
The manufacturing economy expanded slightly in June, according to the S&P US Manufacturing PMI. New orders appear to be increasing, and input costs remain an issue. That said, business confidence hit a 19 month low. “Factories have been hit over the past two years by demand switching post-pandemic from goods to services, while at the same time household and business spending power has been diminished by higher prices and concerns over higher-for-longer interest rates. These headwinds persisted into June, accompanied by heightened uncertainty about the economic outlook as the presidential election draws closer. Business confidence has consequently fallen to the lowest for 19 months, suggesting the manufacturing sector is bracing itself for further tough times in the coming months.”
Stocks are higher this morning on no real news. Bonds and MBS are down.
The week ahead will have a lot of real estate data, with home prices and pending home sales. We will get the third revision to Q1 GDP and get personal incomes / outlays on Friday which will give us the all-important PCE Price Index.
Existing home sales fell 0.7% MOM in May, according to NAR. This is a decline of 2.8% compared to a year ago. The median home price rose 5.8% on a YOY basis to $419,300. There are about 1.28 million units for sale, which represents a 3.7 month supply at the current sales pace. A balanced market is 6 – 7 months’ worth of supply.
“Eventually, more inventory will help boost home sales and tame home price gains in the upcoming months,” said NAR Chief Economist Lawrence Yun. “Increased housing supply spells good news for consumers who want to see more properties before making purchasing decisions.” “Home prices reaching new highs are creating a wider divide between those owning properties and those who wish to be first-time buyers,” Yun added. “The mortgage payment for a typical home today is more than double that of homes purchased before 2020. Still, first-time buyers in the market understand the long-term benefits of owning.”
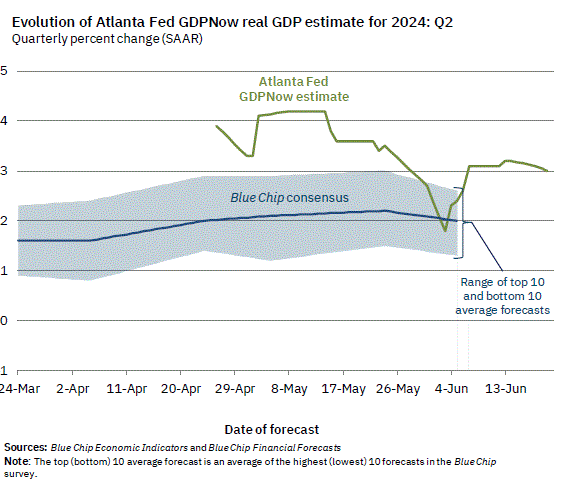
Q2 GDP is tracking around 3%, according to the Atlanta Fed GDP Now model.
Stocks are higher as markets digest the Fed decision. Bonds and MBS are down small.
As expected, the Fed maintained the Fed Funds rate at current levels. “Recent indicators suggest that economic activity has continued to expand at a solid pace. Job gains have remained strong, and the unemployment rate has remained low. Inflation has eased over the past year but remains elevated. In recent months, there has been modest further progress toward the Committee’s 2 percent inflation objective.” In the May statement, the Fed said that “In recent months, there has been a lack of further progress toward the Committee’s 2 percent inflation objective.” So there is a bit of an improvement in the language.
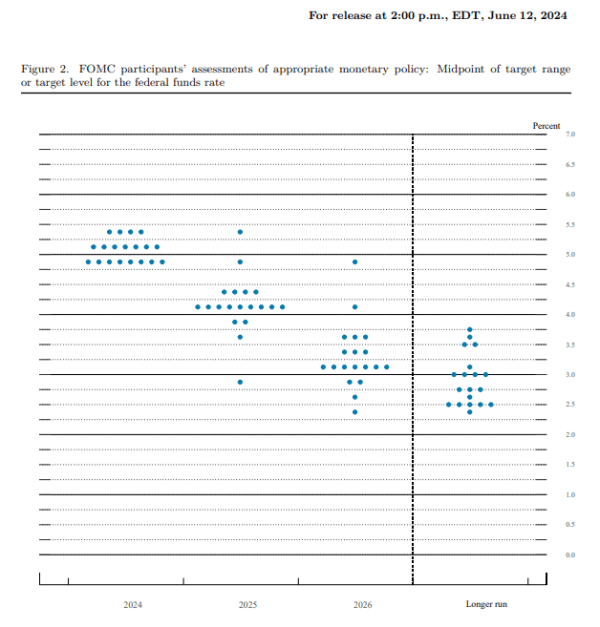
The dot plot showed the Committee expects to cut rates once this year. The economic forecasts didn’t move much, however they did bump up their inflation forecasts a tad, with the headline PCE forecast increasing from 2.4% to 2.6% and the core rate increasing from 2.6% to 2.8%.
We have another benign inflation report, with the producer price index actually falling 0.2% on a month-over-month basis and 2.2% on a year-over-year basis. About 60% of the decline was due to falling gas prices. Ex-food and energy, the index was flat and rose 2.3% on a YOY basis. Both numbers were below expectations.
More evidence of a weakening job market: Initial Jobless Claims rose to 242k last week. This is the highest level since August of last year.
The median home sale price in the US hit a record last week, according to Redfin. The median sale price hit $394,000 which is up 4.4% on a year-over-year basis. Asking prices appear to be leveling off however. The median mortgage payment fell to $2,829 due to falling mortgage rates. “The latest inflation report is good for homebuyers because it has already sent mortgage rates down, though this week’s Fed meeting will temper mortgage-rate declines,” said Chen Zhao, Redfin’s economic research lead. “But on the other side of the coin, if lower mortgage rates bring back more demand than supply, that could erase the possibility that home-price growth softens, and push prices up even further. Lower rates and higher prices may ultimately cancel each other out when it comes to homebuyers’ monthly paym
Stocks are lower this morning on no real news. Bonds and MBS are up.
Bond yields got pushed down on the softer-than-expected ISM survey yesterday. The market narrative seems to be shifting from persistent inflation to a slowdown.
The manufacturing economy deteriorated in May, according to the ISM report. “U.S. manufacturing activity continued in contraction after growing in March, the first expansion for the sector since September 2022. Demand was soft again, output was stable, and inputs stayed accommodative. Demand remains elusive as companies demonstrate an unwillingness to invest due to current monetary policy and other conditions. These investments include supplier order commitments, inventory building and capital expenditures. Production execution continued to expand but was essentially flat compared to the previous month. Suppliers continue to have capacity, with lead times improving and shortages not as severe. Fifty-five percent of manufacturing gross domestic product (GDP) contracted in May, up from 34 percent in April.
The prices measure improved from April, but is still above February and March.
Construction spending fell 0.1% MOM and rose 10% YOY. Residential construction rose 8.1% on a year over year basis. There is a massive bifurcation in the resi market, with single-family construction up 20.4% YOY and multi-family up 2.3%.
We are seeing signs that multi-family has reached saturation and projects that penciled out in the 0% free-money era of COVID no longer make sense. “We certainly are seeing a decline in construction,” said Robert Dietz, chief economist at the National Association of Home Builders. “Deals and financing have dried up.”
The boom in multi-family building was the biggest since the early 1970s.
The inventory issue is most acute in the markets which boomed during the pandemic years – Boise, Phoenix, Austin, etc.
For-sale inventory is becoming more aligned with demand, according to the ICE Mortgage Monitor. “With 30-year rates easing and affordability improving entering the year, unadjusted monthly price gains had been running above their same-month 25-year average since the start of 2024,” said Walden. “However, softening price growth in April has dropped us below that long-run average. We’ve seen the rate of appreciation slow on an adjusted level as well, with April’s +0.28% increase in home prices a marked downshift from +0.45% in March.
Stocks are lower this morning on global weakness and weaker bonds. Bonds got hammered yesterday after a lousy bond auction of 5-year notes, which sent the 10 year yield back above 4.5% to end at 4.55%. Bonds and MBS are weaker again today.
Minneapolis Fed President Neel Kashkari isn’t ready to start thinking about rate cuts yet, and warned about the possibility of another rate hike in an interview with CNBC yesterday. “Many more months of positive inflation data, I think, to give me confidence that it’s appropriate to dial back….I’m not seeing the need to hurry and do rate cuts. I think we should take our time and get it right.” On the subject of rate hikes, he said: “I don’t think we should rule anything out at this point”
Home prices rose 6.6% in the first quarter of 2024 compared to the first quarter of 2023. “U.S. house prices continued to grow at a steady pace in the first quarter,” said Dr. Anju Vajja, Deputy Director for FHFA’s Division of Research and Statistics. “Over the last six consecutive quarters, the low inventory of homes for sale continued to contribute to house price appreciation despite mortgage rates that hovered around 7 percent.”
Home price appreciation is accelerating again:
Home prices hit a new all-time high, according to the Case-Shiller Home Price Index. “This month’s report boasts another all-time high,” says Brian D. Luke, Head of Commodities, Real & Digital Assets at S&P Dow Jones Indices. “We’ve witnessed records repeatedly break in both stock and housing markets over the past year. Our National Index has reached new highs in six of the last 12 months. During that time, we’ve seen record stock market performance, with the S&P 500 hitting fresh all-time highs for 35 trading days in the past year.
“Regionally, the Northeast remains the top performer with an 8.3% annual gain, showcasing robust growth compared to other metro markets. Conversely, cities like Tampa, Phoenix, and Dallas, which saw top-tier performance in 2020 and 2021, are now growing at a slower pace. COVID was a boom for Sunbelt markets, but the bigger gains the last couple of years have been the northern metro cities,” Luke reported. “On a seasonal adjusted basis, national home prices have reached their ninth all-time high within the past year, with all 20 metropolitan markets posting positive annual gains for the fourth consecutive month, indicating widespread and sustained growth in the housing sector.”
It does seem to be a tale of two markets, where the Sunbelt struggles with a lot of new construction, while the two markets that have lagged the post 2012 real estate recovery – the Midwest and the Northeast – are gathering steam. Of course San Diego continues to perform well regardless, because it is, well, San Diego.
Consumer confidence improved in May, according to the Conference Board. “Confidence improved in May after three consecutive months of decline,” saidDana M. Peterson, Chief Economist at The Conference Board. “Consumers’ assessment of current business conditions was slightly less positive than last month. However, the strong labor market continued to bolster consumers’ overall assessment of the present situation. Views of current labor market conditions improved in May, as fewer respondents said jobs were ‘hard to get,’ which outweighed a slight decline in the number who said jobs were ‘plentiful.’ Looking ahead, fewer consumers expected deterioration in future business conditions, job availability, and income, resulting in an increase in the Expectation Index. Nonetheless, the overall confidence gauge remained within the relatively narrow range it has been hovering in for more than two years.”
The present situation index remains well above the expectations index. Fewer people thought jobs were hard to get and expectations improved slightly. That said, the expectations index remains firmly mired in recessionary territory, with inflation expectations increasing from 5.3% to 5.4%.
Note that inflationary expectations are a key input to Fed decision-making since there are all sorts of ancillary behavioral effects that go along with it. Based on inflationary expectations, real interest rates are more or less zero, which could explain why the economy (and inflation) has remained resilient even in the face of 525 basis points of tightening.
Finally, home purchase plans remain the lowest since the bottom of the housing bust in 2012.
Stocks are higher this morning after good numbers out of Nvidia. Bonds and MBS are flat.
Existing home sales fell 1.9% to a seasonally-adjusted annual rate of 4.14 million. “Home sales changed little overall, but the upper-end market is experiencing a sizable gain due to more supply coming onto the market,” said NAR Chief Economist Lawrence Yun.
Housing inventory is up, which is good news for activity overall. It rose to 1.21 million units which was a 9% bump from last month and 16% from a year ago. This represents a 3.5 month supply at the current sales pace. This is still on the low side – a balanced market is about six month’s worth – but at least we are off the record lows we have seen over the past couple of years.
The median home price rose 5.7% YOY to $407,600. “Home prices reaching a record high for the month of April is very good news for homeowners,” Yun added. “However, the pace of price increases should taper off since more housing inventory is becoming available.”
The FOMC minutes from the May meeting support the “higher for longer” narrative.
Participants noted that they continued to expect that inflation would return to 2 percent over the medium term. However, recent data had not increased their confidence in progress toward 2 percent and, accordingly, had suggested that the disinflation process would likely take longer than previously thought. Participants discussed several factors that, in conjunction with appropriately restrictive monetary policy, could support the return of inflation to the Committee’s goal over time. One was a further reduction in housing services price inflation as lower readings for rent growth on new leases continued to pass through to this category of inflation. However, many participants commented that the pass-through would likely take place only gradually or noted that a reacceleration of market rents could reduce the effect.
Participants discussed the risks and uncertainties around the economic outlook. They generally noted their uncertainty about the persistence of inflation and agreed that recent data had not increased their confidence that inflation was moving sustainably toward 2 percent. A number of participants noted uncertainty regarding the degree of restrictiveness of current financial conditions and the associated risk that such conditions were insufficiently restrictive on aggregate demand and inflation.
Some of the participants raised the possibility that unusually strong seasonal patterns might have been behind the negative surprises in inflation at the beginning of the year. They also noted signs that the consumer is beginning to run out of steam, noting increases in credit use and buy-now-pay-later program usage.
It looks like the economy slowed in April, according to the Chicago Fed National Activity Index (CFNAI). Consumption and Production indicators drove the decrease.
Stocks are flattish this morning after wholesale inflation came in higher than expected. Bonds and MBS are down.
Inflation at the wholesale level rose 0.5% month-over-month and 2.2% year-over year. Ex-food and energy, the index rose 0.5% MOM and 2.4% YOY. Most of the increase in the index was attributable to a 0.6% increase in final demand services, which generally means wages.
The New York Fed released its survey of consumer inflation expectations, which showed short-term inflationary expectations rose to 3.3% from 3.0%. On the positive side, we remain below the 3.5% trailing 12 month average. Inflationary expectations are falling, however we remain above the Fed’s target.
Inflationary expectations are a critical portion of the inflation problem, and the Fed will be reluctant to start cutting rates when expectations are rising.
Small Business Optimism improved in April, according to the NFIB. Confidence rose 1.2%, which was the first increase this year, however we are still below the long-term average for the index. “The Federal Reserve is trapped by its policies, unable to cut rates when inflation stays persistently high (well over the 2% goal). The decline in the inflation rate from 9% could justify a small policy rate cut, but overall, the Fed needs to see more progress on reducing the inflation rate. Historically, recessions accomplish this, that’s when price cutting becomes more common. Last month’s BLS job report suggests some weakening with only about half as many jobs created compared to the prior months. As things stand now, it is likely that there will be only one rate cut this year (seven were expected last January).”
Stocks are lower this morning on no real news. Bonds and MBS are down.
Minneapolis Fed President Neel Kashkari thinks the current rate regime will last a while. He didn’t rule out further rate hikes, although he doesn’t consider that a base case. “The FOMC targets 12-month headline inflation of 2 percent. While we saw rapid disinflation in the second half of 2023, that progress appears to have stalled in the most recent quarter (see Figure 1). The question we now face is whether the disinflationary process is in fact still underway, merely taking longer than expected, or if inflation is instead settling to around a 3 percent level, suggesting that the FOMC has more work to do to achieve our dual mandate goals.”
He also suggested that policy might not be super-restrictive given the strength of the housing market. He does mention some exogenous factors such as underbuilding post-2008, along with heavy immigration has increased demand for housing. “Policy actions by the FOMC have driven 30-year mortgage rates from around 4.0 percent prior to the pandemic to around 7.5 percent today. Perhaps that level of mortgage rates is not as contractionary for residential investment as it would have been absent these unique factors which are driving housing demand higher. In other words, perhaps a neutral rate for the housing market is higher than before the pandemic.” Since housing is the main driver of inflation these days, inflation (and therefore tight monetary policy) might stick around a while longer.
In an interview, he did say the bar is high to consider additional rate hikes, and also said we may be at current levels a while: “My colleagues and I are of course very happy that the labor market has proven resilient, but, with inflation in the most recent quarter moving sideways, it raises questions about how restrictive policy really is.”
Bottom line: if housing is the driver of inflation, and the neutral rate may be higher, then additional rate hikes might be needed to cool the housing market. Unfortunately, it is a catch-22: The problem for housing is limited supply, and higher rates don’t encourage building. But if they cut rates to stimulate building, they might stimulate speculation instead.
FWIW, I think a lot of the hottest markets (especially in FL) were driven by Air BnB speculators, and the Air BnBust is in full bloom. We are seeing price cutting in a lot of the hottest markets.
If these properties were financed with non-QM mortgages using DSCR programs, we could start seeing DQs pile up there.
Mortgage applications rose 2.5% last week as purchases rose 2% and refis rose 5%. “Treasury rates and mortgage rates fell last week on the news of a slowing job market, with wage growth at the slowest pace since 2021, and the Federal Reserve’s announced plans to ease quantitative tightening in June and to maintain its view that another rate hike is unlikely. The conventional 30-year rate dropped 11 basis points, and the FHA rate fell 17 basis points to 6.92 percent, back below 7% for the first time in three weeks,” said Mike Fratantoni, MBA’s Senior Vice President and Chief Economist. “Mortgage applications increased for the first time in three weeks, with refinances up 5 percent. Even with the increase, which included a 29 percent jump in VA refinances, refinance volume remains about 6 percent below last year’s already low levels.”
Stocks are lower this morning as the May FOMC meeting begins. Bonds and MBS are up.
Fed-whisperer Nick Timaros of the Wall Street Journal says the Fed is planning to signal to the markets that it is comfortable keeping rates higher for longer, while stopping short of introducing the possibility of raising rates further.
“Firmer-than-anticipated inflation in the first three months of the year has likely postponed rate cuts for the foreseeable future. As a result, officials are likely to emphasize that they are prepared to hold rates steady, at a level most of them expect will provide meaningful restraint to economic activity, for longer than they previously anticipated.”
“But a hawkish pivot, suggesting an increase in rates is more likely than a cut, appears unlikely, for now. Any such shift is likely to unfold over a longer period. It would require some combination of a new, nasty supply shock such as a significant increase in commodity prices; signs that wage growth was reaccelerating; and evidence the public was anticipating higher inflation to continue well into the future.”
The article suggests the Fed is close to tapering its balance sheet reduction (quantitative tightening) by reducing the runoff of its Treasury securities. In other words, this won’t affect mortgage backed securities. The runoff for mortgage backed securities continues, albeit at an organic pace driven by relocation and a few cash-out refis.
Compensation costs for civilian workers increased 1.2% in the first quarter, according to the Employment Cost Index. Wages increased 1.1%, as did benefit costs. For the past 12 months, compensation costs rose 4.8%. On a quarter-over-quarter basis, compensation costs rose from 0.9% to 1.2%, driven largely by an increase in benefit costs. Note this kind of contradicts the CPI data which claims that health insurance costs fell 15% in March.