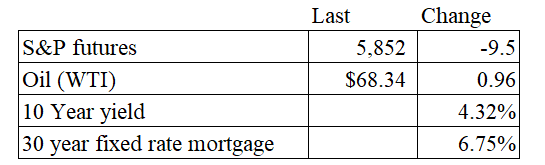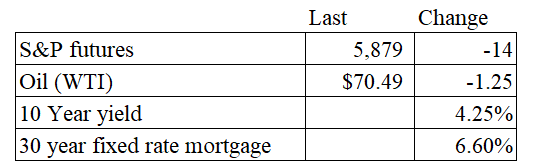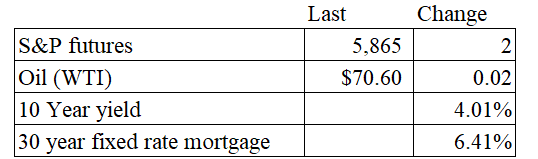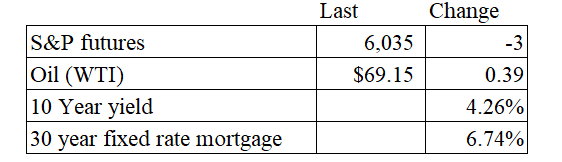
Morning Report: New home sales fall

Vital Statistics:

Stocks are flattish this morning on no real news. Bonds and MBS are up.

Third quarter GDP rose 2.8% in the second revision to the estimate. This was in line with Street expectations.

New Home Sales disappointed again, coming in at 610,000, which was well below the Street expectation of 725k. This was down 17.3% compared to September and down 9% compared to a year ago.

The median home price was $437,300, and the average price was $585,800. There was 9.5 months’ worth of supply.

The FOMC minutes were released yesterday. On the subject of inflation, the members sounded pretty confident:

With regard to the outlook for inflation, participants indicated that they remained confident that inflation was moving sustainably toward 2 percent, although a couple noted the possibility that the process could take longer than previously expected. A few participants remarked that insofar as recent robust increases in real GDP reflected favorable supply developments, the strength of economic activity was unlikely to be a source of upward inflation pressures. Participants cited various factors likely to put continuing downward pressure on inflation, including waning business pricing
power, the Committee’s still-restrictive monetary policy stance, and well-anchored longer-term inflation expectations.
Several participants noted that nominal wage growth had continued to move down and that the wage premium available to job switchers had diminished. In addition, some participants observed that, with supply and demand in the labor market being roughly in balance and in light of recent productivity gains, wage increases were unlikely to be a source of inflationary pressure in the near future.

Further into the minutes, they discussed that the economy has been stronger than expected, and that downside risks to the economy had become less prominent. The Fed Funds futures see a 66% chance of a 25 basis point cut at the next meeting in mid-December.

Mortgage applications rose 6.3% last week, as purchases rose 12% and refis fell 3%. “Purchase activity drove overall applications higher last week, as conventional purchase applications picked up pace and mortgage rates declined for the first time in over two months, with the 30-year fixed rate dropping slightly to 6.86 percent,” said Joel Kan, MBA’s Vice President and Deputy Chief Economist. With the growth in for-sale inventory and signs that the economy remains strong, buyers have remained in the market even though rates have increased recently. The increase in conventional purchase applications helped push the average purchase loan size to $439,200, its highest level in almost a month. The decline in refinance activity was driven by pullbacks in FHA and VA refinances. Applications were significantly higher than a year ago by most measures, but this was compared to the week of Thanksgiving 2023, which was a week earlier than this year’s holiday.”

The new FHFA limits are out, rising 5.2% to $806,500. The high balance limit (for expensive MSAs) is 150% of that or $1,209,750.

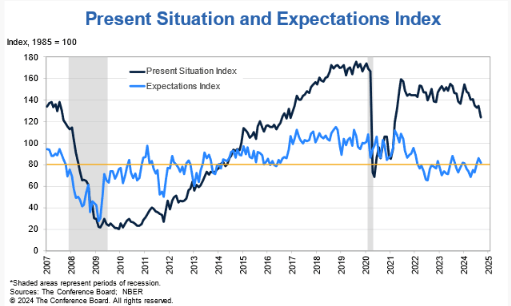
Consumer confidence improved in November, according to the Conference Board. “Consumer confidence continued to improve in November and reached the top of the range that has prevailed over the past two years,” said Dana M. Peterson, Chief Economist at The Conference Board. “November’s increase was mainly driven by more positive consumer assessments of the present situation, particularly regarding the labor market. Compared to October, consumers were also substantially more optimistic about future job availability, which reached its highest level in almost three years. Meanwhile, consumers’ expectations about future business conditions were unchanged and they were slightly less positive about future income.”

I am accepting ads for this blog if you would like to make an announcement, highlight something your company is offering or want more visibility. I am running a special for new clients as well. I offer white-label services which give you the ability to use this content for your own daily emails. The blog has thousands of subscribers / followers and an open rate around 50%. Please feel free to reach out to brent@thedailytearsheet.com if you would like to discuss this further

Morning Report: Housing starts fall

Vital Statistics:

Stocks are lower this morning on Ukraine / Russia fears. Bonds and MBS are up.

Housing starts fell to 1.311 million units in October, according to the Census Bureau. This is down 4% on a year-over-year basis. Building permits fell 7.7% on a YOY basis to 1.534 million units.

Homebuilder confidence improved in November as political uncertainty abated. “With the elections now in the rearview mirror, builders are expressing increasing confidence that Republicans gaining all the levers of power in Washington will result in significant regulatory relief for the industry that will lead to the construction of more homes and apartments,” said NAHB Chairman Carl Harris, a custom home builder from Wichita, Kan. “This is reflected in a huge jump in builder sales expectations over the next six months.”

“While builder confidence is improving, the industry still faces many headwinds such as an ongoing shortage of labor and buildable lots along with elevated building material prices,” said NAHB Chief Economist Robert Dietz. “Moreover, while the stock market cheered the election result, the bond market has concerns, as indicated by a rise for long-term interest rates. There is also policy uncertainty in front of the business sector and housing market as the executive branch changes hands.”

Nomura is out with a call saying that the Fed will not cut rates at the December FOMC meeting. Their argument is that the election of Trump will be inflationary due to tariffs, which will prevent the Fed from easing further. The bank sees the Fed skipping the December meeting and then cutting in May and June of 2025 by 25 basis points. After that, they see the Fed holding rates there.

FWIW, I doubt the Fed is letting policy speculation drive its decision-making. Inflation continues to fall towards the Fed’s 2% target, and policy remains restrictive.

Morning Report: Inflation rises

Vital Statistics:

Stocks are higher this morning despite a pick up in inflation. Bonds and MBS are down.

The headline consumer price index rose 0.2% MOM in October, according to the BLS. Shelter rose 0.4% and accounted for half the increase. Energy was flat after a big decline in September.

On a year-over-year basis, the headline CPI rose 2.6%. If you strip out food and energy, the CPI rose 0.3% month over month and 3.3% YOY.

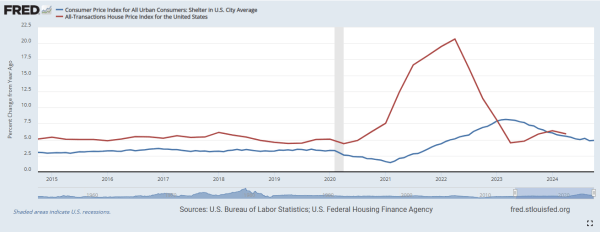
I graphed the CPI shelter index (blue line) versus the FHFA House Price Index (red line). You can see that the FHFA house price index leads the CPI shelter index, and FHFA’s house price growth is returning to pre-2020 levels. This should drag down the shelter component of CPI and return inflation back to pre-pandemic levels.

Mortgage applications increased 0.5% last week as purchases rose 2% and refis fell 2%. “Mortgage rates continued to increase last week, driven by higher Treasury yields as financial markets digested the likely impacts of a Trump presidency. The Federal Reserve’s 25-basis-point rate cut was already anticipated and did little to move the markets,” said Joel Kan, MBA’s Vice President and Deputy Chief Economist. “The 30-year fixed rate was at 6.86 percent last week, its highest since July 2024. However, despite the increase in rates, applications increased for the first time in seven weeks.”

Added Kan, “Purchase applications picked up and remained close to levels from a year ago. FHA and VA purchase applications drove the stronger overall purchase activity, increasing 3 percent and 9 percent, respectively. FHA mortgage rates bucked the overall trend and were lower over the week, which likely helped some borrowers. Conventional purchase applications were also up slightly. Meanwhile, the upward climb in rates led to refinance activity falling to its lowest level since May 2024.”  

Morning Report: Trump wins

Vital Statistics:

Stocks are higher this morning as markets digest the Trump victory. Bonds, on the other hand, are getting slammed.

The Trump trade is full swing, with stocks rising in anticipation of a more business-friendly environment. The action in bonds is probably to be expected, as investors adopt a risk-on position. Overall, Trump will probably be negative for long-term bonds for a few reasons. First, the risk-on aspect means that investors will prefer riskier assets like stocks to safe assets like bonds. Second, stronger economic activity will give the Fed less leeway to cut rates. And finally, hawkish trade policy is bad for Treasuries. The reason for this is that our trading partners run trade surpluses, which means they send us goods and services and we send them Treasuries in return. If trade declines, that means less demand for Treasuries and therefore higher rates at the margin.

All attention now turns to the Fed, which starts its meeting today. Longer-term, it will be interesting to see what happens to the GSEs.

The services economy expanded for the fourth consecutive month, according to the ISM Services Index. “The increase in the Services PMI® in October was driven by boosts of more than 4 percentage points for both the Employment and Supplier Deliveries indexes. The Business Activity and New Orders indexes both dropped by at least 2 percentage points. Each of the four subindexes are now above their averages for 2024. The Supplier Deliveries Index remained in expansion in October, indicating slower delivery performance. Concerns over political uncertainty were again more prevalent than the previous month. Impacts from hurricanes and ports labor turbulence were mentioned frequently, although several panelists mentioned that the longshoremen’s strike had less of an impact than feared due to its short duration.”

Mortgage applications fell 10.8% last week as purchases 5.1% and refis fell 18.5%. “Applications decreased for the sixth consecutive week, with purchase activity falling to its lowest level since mid-August and refinance activity declining to the lowest level since May. The average loan size on a refinance application dropped below $300,000, as borrowers with larger loans tend to be more sensitive to any given changes in mortgage rates”

Morning Report: The Trump Trade continues

Vital Statistics:

Stocks are lower this morning on no real news. Bonds and MBS are down yet again.

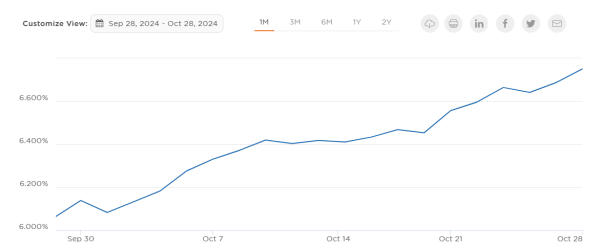
The move in mortgage rates over the past month has been astounding. This is the Optimal Blue Mortgage Market Index for the 30 year conforming mortgage.

The 10 year bond yield has risen as well, but MBS spreads are widening. The ^MOVE index, which tracks bond market volatility is up some 42% over the past month, so that is probably driving it as well.

The media is claiming that this rise in rates is due to fears that the deficit will rise after the election. I guess that is possible, but fiscal rectitude in Washington kind of left the building circa 2009, so I can’t imagine that it is all of a sudden mattering now. The trader in me thinks this will turn out to be a “buy the rumor, sell the fact situation” and rates will peak right before the election, and then come back down as people unwind their Trump trades.

Homebuilder D.R. Horton reported fourth quarter numbers that disappointed the Street, and the stock is getting slammed pre-open. Sales and guidance disappointed.

“Despite continued affordability challenges and competitive market conditions, our net sales orders in the fourth quarter increased slightly from the prior year to 19,035 homes. Our sales pace was in line with normal seasonality from the third to fourth quarter but was below our expectations. While mortgage rates have decreased from their highs earlier this year, many potential homebuyers expect rates to be lower in 2025. We believe that rate volatility and uncertainty are causing some buyers to stay on the sidelines in the near term. To help spur demand and address affordability, we are continuing to use incentives such as mortgage rate buydowns, and we have continued to start and sell more of our homes with smaller floor plans. The supply of both new and existing homes at affordable price points is still generally limited, and demographics supporting housing demand are favorable. With a focus on affordable product offerings, 37,400 homes in inventory and continued improvement in our construction cycle times, we are well positioned for fiscal 2025.”

Home prices rose 4.2% annually in August, which is below the 4.8% annual average. “Home price growth is beginning to show signs of strain, recording the slowest annual gain since mortgage rates peaked in 2023,” says Brian D. Luke, CFA, Head of Commodities, Real & Digital Assets. “As students went back to school, home price shoppers appeared less willing to push the index higher than in the summer months. Prices continue to decelerate for the past six months, pushing appreciation rates below their long-run average of 4.8%.

After smoothing for seasonality in the data, home prices continued to reach all-time highs, for the 15th month in a row. “Regionally, all markets continue to remain positive, barely,” Luke continued. “Denver posted the slowest annual gain of all markets this year, dropping below Portland for the first time since the spring. The Northeast remains the best performing region, with the strongest gains for over a year. Currently, only New York, Las Vegas, and Chicago markets are at an all-time high. Comparing average gains of traditional red and blue states highlight a slight advantage for home price markets of blue states. With stronger gains in the Northeast and West than the South, blue states have outperformed red states dating back to July 2023.”

Morning Report: Bonds and the Trump Trade

Vital Statistics:

Stocks are lower this morning as earnings continue to pour in. Bonds and MBS are down again.

Bond yields seem to be rising in lockstep with the probability of a Trump win. Although polling data indicates a close race, betting markets are increasingly predicting a Trump win. Both sides accuse the other of “painting the tape” with Democrats accusing foreign bad actors of placing big bets to influence the odds, while Republicans accuse Democrats of releasing partisan, over-D sampled polls into the overall mix.

Presumably, a Trump win would be bad for bonds as tariffs would raise prices, and a more pro-business regulatory regime would be better for the economy overall, which will keep the Fed from cutting rates as aggressively. A Trump Presidency would also bring back the debate over what to do with the GSEs.

Mortgage applications fell 6.7% last week as purchases fell 5.1% and refis fell 8.4%. “Mortgage rates saw mixed results last week, but the 30-year fixed rate remained unchanged at 6.52 percent. Application activity decreased to its lowest level since July, as both purchase and refinance applications saw declines,” said Joel Kan, MBA’s Vice President and Deputy Chief Economist. “Purchase applications continued to run stronger than last year’s pace for the fifth consecutive week. Even though rates have been on a recent upswing, they are over a full percentage point lower than a year ago, which has kept some homebuyers in the market. For-sale inventory has started to loosen, and home-price growth has eased in some markets, providing more options for buyers in combination with these lower rates.”

Home prices grew 0.5 MOM in September, according to data from Redfin. On a year-over-year basis, prices rose 6%. “There are around 20% fewer homes on the market today than there were five years ago, mainly because so many homeowners locked in a low mortgage rate during the pandemic,” said Redfin Senior Economist Sheharyar Bokhari. “With mortgage rates back above 6.5% this month—and unlikely to drop below 6% this year—home prices will likely continue their consistent climb until more inventory comes onto the market in the spring.”  

Morning Report: Morning Report: Fed officials open to slowing the pace of rate reductions

Vital Statistics:

Stocks are flattish this morning as earnings continue to come in. Bonds and MBS are up.

San Francisco Fed Chair Mary Daly is open to skipping a rate cut at one of the two remaining Fed meetings this year. “It’s clear that the direction of change is down,” but added “one or two cuts was a reasonable thing” provided that the economic data continues as expected. Atlanta Fed Head Raphael Bostic is also open to skipping a meeting.

The December Fed Funds futures still overwhelmingly see two more cuts this year:

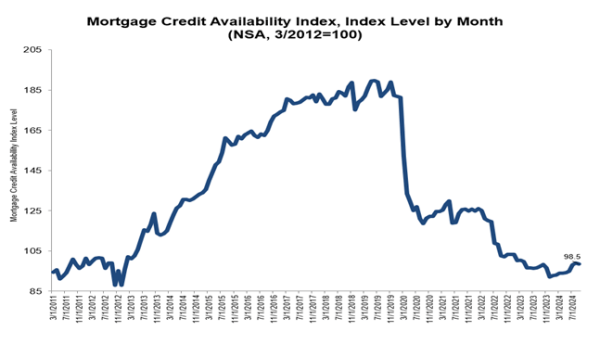
Mortgage credit availability decreased in September, according to the MBA. “Mortgage credit availability tightened slightly in September as lenders remained cautious in this uncertain economic environment,” said Joel Kan, MBA’s Vice President and Deputy Chief Economist. “There was a decline in loan programs for cash-out refinances, jumbo and non-QM loans, including loans that require less than full documentation. Most component indexes decreased over the month, but the government index increased, driven by more offerings of VA streamline refinances.”   

Mortgage applications fell 17% last week as purchases fell 7.2% and refis fell 17%. “ Mortgage rates moved higher for the third consecutive week, with the 30-year fixed rate increasing to 6.52 percent, its highest level since August,” said Joel Kan, MBA’s Vice President and Deputy Chief Economist. “The recent uptick in rates has put a damper on applications. Refinance applications fell 26 percent to their lowest level since August, with comparable drops in both conventional and government refinances. This pushed the refinance share of applications back below 50 percent for the first time in over a month. Furthermore, purchase applications also decreased but notably remain 7 percent higher than a year ago.”

US Bank reported better than expected earnings, although revenues missed. Mortgage origination volume improved markedly, rising 16.7% YOY to $11 billion. They are marking their $215 billion MSR portfolio at 4.9x. Provisions for credit losses increased 8% YOY.

Morning Report: Strong jobs report

Vital Statistics:

Stocks are higher this morning after a strong jobs report. Bonds and MBS are getting slammed.

The port strike has been suspended as the ports and Longshoreman’s union extended their contract through to Jan 15. The issue was almost certainly unhelpful to the Democrats for the upcoming election, so the fight has been tabled until it is over.

The economy added 254,000 jobs in September, according to the Employment Situation Report. This was well above the Street expectations of 132,000. The unemployment rate ticked down to 4.1%. The employment-population ratio ticked up, while the labor force participation rate was flat.

Average hourly earnings rose 4%, which was well above the 3.7% expectation. Overall, it was a strong report.

The early reaction in the bond market was negative, as it gives the Fed more leeway to move cautiously with rate cuts. The 10 year spiked to 3.99% before falling back.

The Fed Funds futures currently see 25 basis points in November and another in December.

The services economy expanded in September, according to the ISM Services Report. “The increase in the Services PMI® in September was driven by boosts of more than 6 percentage points for both the Business Activity and New Orders indexes. The Employment and Supplier Deliveries indexes had mixed results, with a 2.1-percent decrease and 2.5-percent increase, respectively. The Supplier Deliveries Index returned to expansion in September, indicating slower delivery performance. The stronger growth indicated by the index data was generally supported by panelists’ comments; however, concerns over political uncertainty are more prevalent than last month. Pricing of supplies remains an issue with supply chains continuing to stabilize; one respondent voiced concern over potential port labor issues. The interest-rate cut was welcomed; however, labor costs and availability continue to be a concern across most industries.”

Morning Report: Consumer confidence falls on weakening labor outlook

Vital Statistics:

Stocks are flat this morning on no real news. Bonds and MBS are flat as well.

Home prices hit a new record, according to the Case-Shiller Home Price Index. Prices rose 5.0% year-over-year in July, a deceleration from the 5.5% recorded in June. New York City led the charge, followed by Las Vegas and Los Angeles. “We continue to observe outperformance in most low-price tiers in the market on a three- and five-year horizon,” Luke continued. “The low-price tier of Tampa was the best performing market nationally with five-year performance of 88%. The New York market was the best market annually, posting a gain of 8.9%. New York’s low-tier index, which include home values up to $533,000, helped drive that growth with 10.8% annual gains. Over five years, markets such as New York and Atlanta saw low-price-tiered indices outperforming their market by as much as 20% and 18%, respectively. The relative outperformance of low-price-tiered indices has both benefited first-time homebuyers as well as made it more difficult for those looking for a starter home. The opposite is happening in California, which has the most expensive high-price tiers in the nation, all well over $1 million. The rich are getting richer in San Diego, Los Angeles, and San Francisco where their high-price-tiered indices outperformed on a one- and three-year basis.”

Consumer confidence declined in September, according to the Conference Board. “Consumer confidence dropped in September to near the bottom of the narrow range that has prevailed over the past two years,” said Dana M. Peterson, Chief Economist at The Conference Board. “September’s decline was the largest since August 2021 and all five components of the Index deteriorated. Consumers’ assessments of current business conditions turned negative while views of the current labor market situation softened further. Consumers were also more pessimistic about future labor market conditions and less positive about future business conditions and future income.

The Present Situation Index has moved down markedly over the summer and continues to fall. Inflationary expectations remained elevated at 5.2%.

Mortgage applications rose 11% last week as purchases rose 1.4% and refis rose 20%. “Mortgage applications increased to their highest level since July 2022, boosted by a 20 percent increase in refinance applications after a large increase the prior week. The 30-year fixed rate decreased for the eighth straight week to 6.13 percent, while the FHA rate decreased to 5.99 percent, breaking the psychologically important 6 percent level,” Joel Kan, MBA’s Vice President and Deputy Chief Economist. “As a result of lower rates, week-over-week gains for both conventional and government refinance applications increased sharply. The refinance share of applications is now at 55.7 percent, and while the level of refinance activity is still modest compared to prior refi waves, they now account for the majority of applications, given the seasonal slowdown in purchase activity.”

Morning Report: Retail sales rise

Vital Statistics:

Stocks are higher this morning as the Fed begins its meeting. Bonds and MBS are up.

Retail Sales rose 0.1% MOM in August, according to the Census Bureau. This was better than the -0.3% expectation. July retail sales were revised upward by 0.1% to 1.1%. On a year-over-year basis, they rose 2.1%. Since these numbers are not adjusted for inflation, retail sales actually fell slightly YOY on an inflation-adjusted basis.

If you strip out vehicles and gasoline, retail sales rose 0.2% MOM and 3.3% YOY. This was a touch above inflation. Overall, it looks like the consumer remains in decent shape as we head into the back-to-school and holiday shopping seasons.

The Fed begins their FOMC meeting today. The Fed Funds futures have been more volatile than I can remember before a Fed meeting. The current handicapping has a 2/3 chance of a 50 basis point cut and a 1/3 chance of 25.

CNBC’s survey of money managers is leaning 86% towards a 25 basis point cut, FWIW. “We believe that the equivalent of eight cuts in six meetings is more than what will happen,″ John Donaldson, director of fixed income, Haverford Trust Co. wrote in response to the survey. “That forecast is more in line with a hard landing than a soft landing.”

Barry Knapp from Ironsides Macroeconomics says, “We suspect the FOMC will either under-promise or under-deliver, perhaps both.”

The December futures are still predicting a total 125 basis points in cuts this year.

Home prices rose 0.5% MOM in August, according to research from Redfin. On a year-over-year basis, they rose 6.7%. “Prices kept creeping up during this unusually slow summer for home sales as mortgage rates came down and supply remained stubbornly low,” said Redfin Senior Economist Sheharyar Bokhari. “If mortgage rates fall further this fall—and we expect they will—price growth will likely pick up as more prospective homebuyers come off the sidelines .”