

No MR this week either. Working on the West Coast and the tech gremlins aren’t cooperating. Will try later this week, but so far having too many difficulties..
Filed under: Morning Report | 1 Comment »
No MR this week either. Working on the West Coast and the tech gremlins aren’t cooperating. Will try later this week, but so far having too many difficulties..
Filed under: Morning Report | 1 Comment »
Vital Statistics:
| Last | Change | Percent | |
| S&P Futures | 1362.1 | -9.8 | -0.71% |
| Eurostoxx Index | 2258.5 | -44.0 | -1.91% |
| Oil (WTI) | 90.8 | -1.9 | -2.01% |
| LIBOR | 0.452 | -0.001 | -0.22% |
| US Dollar Index (DXY) | 83.29 | 0.408 | 0.49% |
| 10 Year Govt Bond Yield | 1.46% | -0.05% | |
| RPX Composite Real Estate Index | 184.8 | 0.0 |
Equity markets are weaker this morning in spite of a deal to rescue the Spanish banks and decent earnings reports out of Google and GE. There is no economic data to speak of. Bonds are up a point and MBS are up as well.
Bloomberg has a good article discussing the state of the mortgage industry and how much capacity has been drained from it. “Efforts by Obama and Bernake to help homeowners get cheaper loans and spur the economy have been slowed by lack of staff at lenders and less competition.” Fears of buyback risk are also making lenders more cautious.
SIFMA (which oversees the To-Be-Announced mortgage securities) weighs in on the eminent domain issue. They are instituting a policy that would exclude municipalities that institute eminent domain claims on mortgages from the TBA market. Without getting into the gory details, the TBA market is the way newly originated mortgages get packaged into Fannie / Freddie / Ginnie mortgage backed securities. Punch line: It will be very difficult to get a mortgage in San Bernardino because the lender will have a tougher time disposing of the loan. I am surprised at how little interest the press has shown regarding this issue.
No MR for the next week – I will be on vacation.
Filed under: Morning Report | 47 Comments »
Vital Statistics:
Markets are generally higher this morning on hopes of further stimulus measures and some decent earnings reports out of Ebay and IBM. Morgan Stanley missed. Spain raised 3 billion euros but paid dearly for it. Bonds are down almost a point and MBS are down a tick or two.
Initial Jobless Claims for the week of 7/14 came in at 386k, more in line with typical readings. Last week’s low 350k print was revised upwards, but still looks like a statistical fluke. Separately, it looks like another round of job cuts is on the way in the banking sector.
In other economic data, existing home sales fell by 5.4% month-on-month to an annualized pace of 4.37MM units. The Street was expecting 4.62MM. The Leading Economic Indicators index posted a negative number in June, the second negative number in 3 months.
The Philly Fed survey reported weak business conditions. Ominously, they reported declines in employment and shorter work hours.
FHA is conducting another mass distressed loan sale. Buyers will not be permitted to initiate foreclosure proceedings for 6 months. The loans are concentrated in hard hit areas like Phoenix, Tampa, Chicago, and Newark.
The Fed is considering another measure to ease up credit – allowing banks to borrow from the Fed at even lower interest rates provided the money is used to lend, not buy Treasuries. The Fed is really scraping the bottom of the barrel at this point – I guess the next step would be to allow the banks to repo the water cooler and office furniture.
Chart: Initial Jobless Claims:

Filed under: Morning Report | 15 Comments »
Vital Statistics:
| Last | Change | Percent | |
| S&P Futures | 1354.8 | -3.7 | -0.27% |
| Eurostoxx Index | 2257.6 | 6.9 | 0.31% |
| Oil (WTI) | 88.99 | -0.2 | -0.26% |
| LIBOR | 0.455 | 0.000 | 0.00% |
| US Dollar Index (DXY) | 83.24 | 0.210 | 0.25% |
| 10 Year Govt Bond Yield | 1.48% | -0.03% | |
| RPX Composite Real Estate Index | 184.5 | 0.4 |
Markets are a little weaker on no real news. A slew of banks reported earnings this morning, and most were better than expected. Bond yields are back below 1.5% and MBS are up slightly. The Bernank’s testimony continues today.
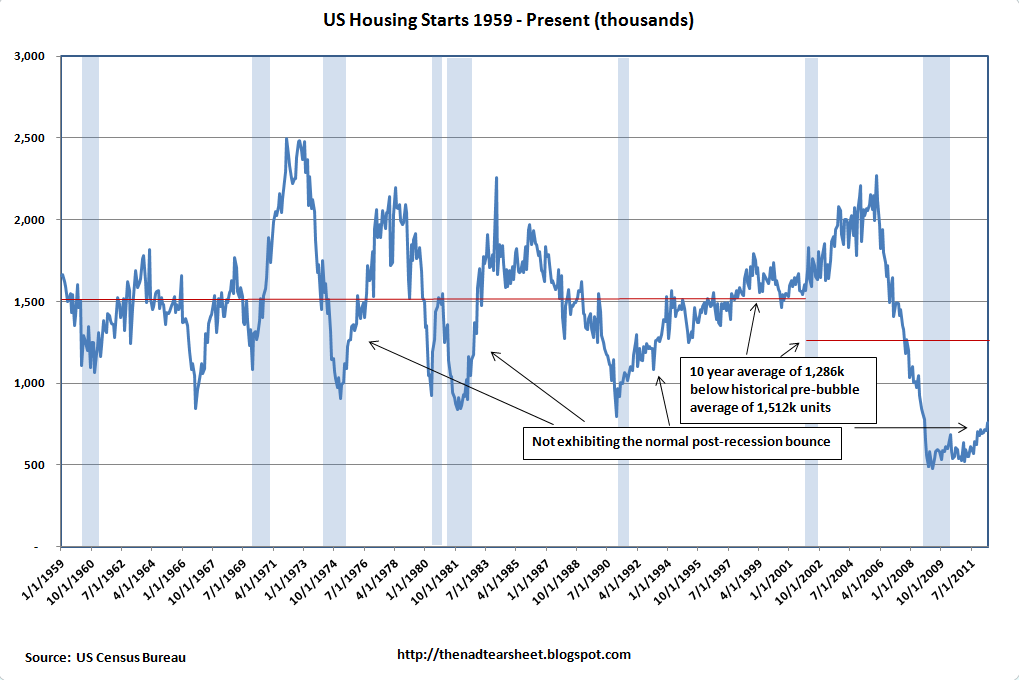
Housing starts came in at 760k in June, an increase from a revised 711k in May. While most other sectors in the economy are decelerating, the housing construction sector is accelerating. That said, housing starts are a long way from normalcy. Sentiment in the homebuilders has been improving as well, with the NAHB Builder Confidence Index rising smartly in July.
Housing Starts:
NAHB Housing Index

On the heels of San Bernardino’s eminent domain proposal, Georgetown Professor of Law lays out another avenue to deal with underwater equity – “quasi-voluntary” principal reductions. In his paper Clearing the Mortgage Market Through Principal Reduction, he makes the case that negative equity is the reason why the housing market hasn’t bottomed and we need a policy response to it. The solution – make the banks an offer they can’t refuse: Either reduce the principal on your underwater mortgages to home value or we’ll take away your ability to deal with the GSEs or FHA. Since this more or less is a “reduce principal or get out of the business” it isn’t much of a choice. While he mentions that there could be political consequences of these various actions (he looks at involuntary takings as well), he never mentions the possibility that lenders may in fact decide to adjust their risk calculations accordingly, thus drying up credit even more. What good is a new re-negotiated mortgage to the system if the existing homeowner can only sell to cash buyers or buyers that put up 40%? Amazingly, he doesn’t consider the knock-on effects to lender behavior at all. He assumes that things will just continue as before and lenders will write off this intervention as a necessary “one-off” that is really good for them and good for the country. If that is an indication of how liberal policy makers in general think – that the private sector will not react to their policy changes – that explains a lot.
Filed under: Morning Report | 10 Comments »
Vital Statistics:
| Last | Change | Percent | |
| S&P Futures | 1352.3 | 4.9 | 0.36% |
| Eurostoxx Index | 2266.2 | 14.3 | 0.63% |
| Oil (WTI) | 88.68 | 0.3 | 0.28% |
| LIBOR | 0.455 | 0.000 | 0.00% |
| US Dollar Index (DXY) | 83.12 | 0.021 | 0.03% |
| 10 Year Govt Bond Yield | 1.49% | 0.02% | |
| RPX Composite Real Estate Index | 184.2 | 0.1 |
Markets are firmer this morning on an earnings “beat” out of Goldman. I put “beat” in quotation marks because the report was actually lousy as revenues are at a 7 year low. Expectations are way low going into this earnings season. As we approach August, the European newsflow should grind to a halt. Bonds are down a half a point, and MBS are down a tick or two. The Bernank is testifying in front of Congress at 10:00 this am. Expect a lot of newly-minted LIBOR experts to opine on the subject.
The CPI came in flat for June on falling energy prices. That is about to be offset by increased food prices as corn approaches $8.00 a bushel due to drought conditions in the Midwest. Industrial Production rose, while capacity utilization fell.
Bill Gross is warning of a recession “when measured by employment, retail sales, investment, and corporate profits.” Investment banks are taking down their economic forecasts in a large steps – Jan Hatzius of Goldman took his 2Q estimate to 1.1% from 1.3%, while Deutsche Bank’s Joe LaVorgna took down his forecast to 1% from 1.4%. These estimates would put the economy firmly in the “stall speed” range.
The WSJ notes that asking prices are rising as supply decreases. Asking prices are up 2.7%, while the number of homes listed for sale is down 19.4% from a year ago. Banks are holding back foreclosures from the market, and are often times finding bids on the courthouse steps from professional investors looking for rental properties. Median age has been falling as well.
Filed under: Morning Report | 12 Comments »
Vital Statistics:
| Last | Change | Percent | |
| S&P Futures | 1346.3 | -5.4 | -0.40% |
| Eurostoxx Index | 2246.9 | -12.2 | -0.54% |
| Oil (WTI) | 86.57 | -0.5 | -0.61% |
| LIBOR | 0.455 | 0.000 | 0.00% |
| US Dollar Index (DXY) | 83.63 | 0.285 | 0.34% |
| 10 Year Govt Bond Yield | 1.46% | -0.03% | |
| RPX Composite Real Estate Index | 184.1 | 0.3 |
RIP Barton Biggs.
Markets are weaker this morning on disappointing retail sales data. June retail sales fell 50 basis points in June while the Street was expecting a 20 basis point rise. The 10-year continues to grind higher,with the yield now at 1.46%. Mortgage backed securities are up small. A lot of market heavyweights report earnings this week with Johnny John, Coca-Cola, Intel, Honeywell, Yum, Amex, Ebay, IBM, and Google, among others.
Citigroup beat analyst expectations with a $1.00 per share second quarter earnings report. Revenues were weaker than expected. Book Value increased to $62.21. The stock is up about 2.5% pre-open.
The NY Fed’s Empire State Manufacturing Survey showed an uptick in July. Manufacturer Optimism remains on the positive side, but is lower than earlier this year. Input Prices fell.
Reuters has a dour outlook on the housing market, suggesting we may be in for a lost decade with house prices. They cite the usual litany of problems with the housing market – immobile underwater homeowners, heavy debt burdens, a lousy job market – but they ignore how fundamentally cheap housing is right now. And that is why prices are stabilizing – eventually a market gets so cheap it cannot be ignored. And that has happened in housing.
Taxmageddon: The game of chicken is on.
Filed under: Morning Report | 21 Comments »
Vital Statistics:
| Last | Change | Percent | |
| S&P Futures | 1331.8 | 2.6 | 0.20% |
| Eurostoxx Index | 2234.7 | 6.7 | 0.30% |
| Oil (WTI) | 86.72 | 0.6 | 0.74% |
| LIBOR | 0.455 | 0.000 | 0.00% |
| US Dollar Index (DXY) | 83.66 | -0.002 | 0.00% |
| 10 Year Govt Bond Yield | 1.48% | 0.01% | |
| RPX Composite Real Estate Index | 183.8 | 0.2 |
Happy Friday the 13th. Markets are slightly higher this morning on no real news. The Producer Price Index showed inflation is being contained. Bonds and MBS are down slightly.
JP Morgan and Wells Fargo announced earnings this morning. JPM is going to restate Q1 earnings, and is laying the groundwork for claiming the huge prop loss was a rogue trader problem. Good luck with that one, Jamie. Wells announced a settlement with the regulators over redlining and announced it is exiting the wholesale mortgage business. Last one out, please shut off the lights.
Rep. David Schweikert weighs in on San Bernardino’s Eminent Domain proposal. He makes the point that whatever intrepid capital has waded back into the mortgage market will probably flee if the government starts seizing underwater mortgages. No kidding. I am surprised President Obama has not seized upon this opportunity to establish his capitalist bona-fides. It could be his “Sister Soulja” moment.
Documents suggest that Tim Geithner was aware of the LIBOR-rigging scandal in 2007 and tried to do something about it.
CoreLogic reported that 11.4 million homes were in negative equity in Q1, down from 12.1 million in Q411. Negative Equity and near-negative equity (< 5%) accounted for 29% of all residential properties with a mortgage.
Filed under: Morning Report | 18 Comments »
Vital Statistics:
| Last | Change | Percent | |
| S&P Futures | 1327.5 | -8.8 | -0.66% |
| Eurostoxx Index | 2230.1 | -16.1 | -0.72% |
| Oil (WTI) | 84.73 | -1.1 | -1.26% |
| LIBOR | 0.455 | -0.001 | -0.22% |
| US Dollar Index (DXY) | 83.75 | 0.185 | 0.22% |
| 10 Year Govt Bond Yield | 1.49% | -0.02% | |
| RPX Composite Real Estate Index | 183.8 | 0.2 |
Markets are lower this morning on global slowdown fears. There was no real catalyst for the sell-off, just general malaise. The 10-year is yielding below 1.5% and MBS are up a couple of ticks.
Initial Jobless claims came in lower than expected, at 350k vs 372k. The Labor Department noted that the typical temporary seasonal factory shutdowns haven’t happened this year as the automakers fulfill demand and replenish inventories. A Labor Department spokesman refers to it as a “distortion”, so don’t read too much into the number.
There was nothing really earth-shattering in the minutes from the last FOMC meeting released yesterday. People looking for more aggressive action out of the Fed were disappointed. Operation Twist will continue through the end of the year, and the Fed will take further action if the economy deteriorates. The minutes did discuss Taxmageddon and also noted that defense contractors were already laying off people if the sequestration spending cuts kick in. Surprisingly, they mentioned the Facebook fiasco as well.
RealtyTrac reported that foreclosure activity increased 9% sequentially in May, but is still down 4% on an annual basis. Pre-foreclosure sales are rising as banks focus more on short sales. Pre-foreclosure home sales have an average $27,000 price than the average bank-owned home. Since distressed sales are still driving the market, this could account for some of the increases we are seeing in the overall home price indices. Another interesting tidbit: Judicial states posted a 26% year-over-year increase in overall foreclosure activity, while non-judicial states posted a 20% decrease.
The House Committee on Financial Services held a hearing yesterday on Dodd-Frank, mortgages, and the CFPB. It was a mix of industry groups and consumer advocates. The fault lines appeared at the definition of a qualified mortgage, where industry groups wanted bright lines and safe harbor provisions while consumer advocates disagreed.
Finally, Paul Krugman isn’t too happy with CNBC.
Filed under: Morning Report | 37 Comments »
Vital Statistics:
| Last | Change | Percent | |
| S&P Futures | 1337.7 | 2.2 | 0.16% |
| Eurostoxx Index | 2246.3 | 4.4 | 0.20% |
| Oil (WTI) | 84.94 | 1.0 | 1.23% |
| LIBOR | 0.456 | -0.002 | -0.33% |
| US Dollar Index (DXY) | 83.24 | -0.161 | -0.19% |
| 10 Year Govt Bond Yield | 1.51% | 0.01% | |
| RPX Composite Real Estate Index | 183.7 | 0.1 |
Markets are rebounding after yesterday’s bloodbath. Market participants await the minutes of the FOMC meeting later this afternoon and will look for more granularity regarding the economic outlook for 2H and the possibility for further quantitative easing. Bonds are down 1/4 point while MBS are flat.
On the way into work, Bloomberg had a depressing interview with TCW strategist Komal Sri-Kumar. He is predicting a recession in 2H, driven by Europe, political uncertainty over the election, and fears of taxmageddon. His forecast is a 15% to 20% drop in the S&P 500 and a 10-year bond yield of 1.25%.
Earnings season has started out as a mixed bag. Alcoa beat estimates, while Applied Materials, Advanced Micro and Cummins missed. Later this week we have some financials with JPM, Wells, and Citi reporting. The season gets into full gear next week.
CNBC points out that the overall increase in house prices has been driven by dynamics in the distressed market that make the growth somewhat artificial. The demand has been coming from the most fickle of investors – pros and the first time homebuyer – and one characteristic of these transactions is they are one-sided – investors and first time homebuyers aren’t selling one home to buy another, they are just buying. This effect, along with the fact that the banks are dragging their feet releasing inventory into the market, is driving price increases at the low end which is masking weakness in the non-distressed end. FWIW, I believe housing is fundamentally cheap and pent-up demand is building, however housing cycles are very long and markets can remain fundamentally cheap or expensive for a very long time.
San Bernardino County (the ones taking an expansive view of eminent domain) has filed for BK.
Filed under: Morning Report | 37 Comments »
Vital Statistics:
| Last | Change | Percent | |
| S&P Futures | 1351.5 | 2.3 | 0.17% |
| Eurostoxx Index | 2253.9 | 26.0 | 1.17% |
| Oil (WTI) | 85.39 | -0.6 | -0.70% |
| LIBOR | 0.458 | 0.000 | 0.00% |
| US Dollar Index (DXY) | 83.18 | 0.023 | 0.03% |
| 10 Year Govt Bond Yield | 1.52% | 0.01% | |
| RPX Composite Real Estate Index | 183.6 | 0.3 |
Markets are slightly higher this morning on moves by European Finance Minsters to lend to Spanish banks and a positive surprise in UK factory output. Alcoa reported better than expected sales and profits last night. Bonds are down a couple ticks.
The National Federation of Independent Businesses reported a 3 point drop in their Small Business Optimism Index in June. The only bright spot in the report is that small businesses expect credit conditions to continue to improve, but all other components were down. On the employment front, 9% of firms added 2.6 workers, while 12% cut employment by 2.8 workers. The rest were unchd. Punch line: The economy slowed, but so far it doesn’t appear that we are headed into a recession. Political uncertainty remains at historic highs. Note the SC decision on obamacare was not reflected in this report.
Fannie Mae’s National Housing Survey reports that consumer optimism in the housing sector continues to improve, even in the face of weakness in other areas. But is the optimism being artificially driven by tight inventories which is primarily due to negative equity?
The Consumer Financial Protection Bureau has put out a 2000 page phonebook on how to address high cost mortgages. It plans to ban balloon payments and prepayment penalties. Of course, prepayment penalties merely make the cost of the embedded prepayment option explicit, as opposed to being hidden in the interest rate. This would be the equivalent of the SEC decreeing that all mutual funds must be no-load. They also cut the size of permissible late payments and an assortment of other things. By ending balloon payments, the CFPB is effectively ending the hard money mortgage market, leaving those that can’t qualify for a normal mortgage unable to borrow.
Filed under: Morning Report | 14 Comments »

