Morning Report – No we are not in another housing bubble 3/26/15

Stocks are lower worldwide as the Saudis bomb Shiite rebels in Yemen and the semiconductor sector gets taken tot the woodshed. Bonds and MBS are down. The bombing in Yemen is putting a bid under oil.

In economic data this morning, initial jobless claims fell to 282,000 last week from 291,000. This is the lowest reading in 5 weeks. The Markit US Composite PMI rose to 58.5 in March, while the US Services PMI rose to 58.6. Bloomberg Consumer Comfort rose to 45.5 last week.

It is looking like the Germanwings crash was a deliberate act. Note that the new security measures designed to keep bad guys out of the cockpit can also keep the good guys out if the bad guy is already inside.

Senator Richard Shelby suggests that GSE reform probably isn’t happening this year. And since the following year is an election year, you can probably forget about anything happening until 2016 at the earliest.

In the “what passes for analysis” category, CNN wonders if we are in another bubble. Why? Because the Homebuilder ETF (XHB) is back at 2007 levels. Setting aside the idea that ETF valuations can somehow predict where real estate prices go, bubbles require a mindset on the part of buyers and bankers that the asset in question is “special” and cannot fall in value. We will never see another housing bubble in the US, but our grandkids may at some point.

Ara Hovnanian weighs in on the housing market and the state of the first time homebuyer.

Morning Report – Rising Rents are pushing Millennials to buy 3/25/15

Markets are flat this morning on no major news. Bonds and MBS are flat as well.

Mortgage Applications rose 9.5% last week as purchases rose 4.9% and refis rose 12.3%. Refis were 60.5% of all applications last week.

Durable Goods orders fell 1.4% in February. Cap Goods Orders Non-Defense / Ex-air (a proxy for business capital investment) fell 1.4%, while January was revised downward from .6% to -.1%. Corporate America is not increasing capacity at all, and is not pursuing expansion opportunities.

What do companies with cash burning a hole in their pockets do when there are no great expansion opportunities out there? Buy each other. In a bit of a complicated deal, Heinz is buying Kraft. As oil stays down here, I expect to see some deals in the energy patch. The last time oil was this low (aside from the financial crisis days) we saw some huge deals:  Exxon buying Mobil, Conoco buying Philips, and BP buying Amoco.

Rents are rising so fast that they are forcing Millennials to buy houses. In fact, Millennials are now a bigger homebuying cohort than Generation X. Student loan debt remains the biggest hurdle, however. As the economy recovers, a lot of pent-up demand is going to be unleashed. We have gone from a glut of housing to an extreme shortage, which means the builders are going to have to bump up production. The economy is already reasonably strong with only 1.1 million housing starts. If we get back to normalcy (1.5 million), that will provide a big boost. Plus construction employs a lot of people.

Morning Report – New Home Sales rise, but still a production deficit 3/24/15

Markets are higher this morning as oil picks up a bid. Bonds and MBS are flattish.

The FHFA House Price Index rose .3% in January, lower than expectations. Prices are up 5.1% year-over-year and are now within 3.5% of their peak levels, which corresponds to December 2005 levels.

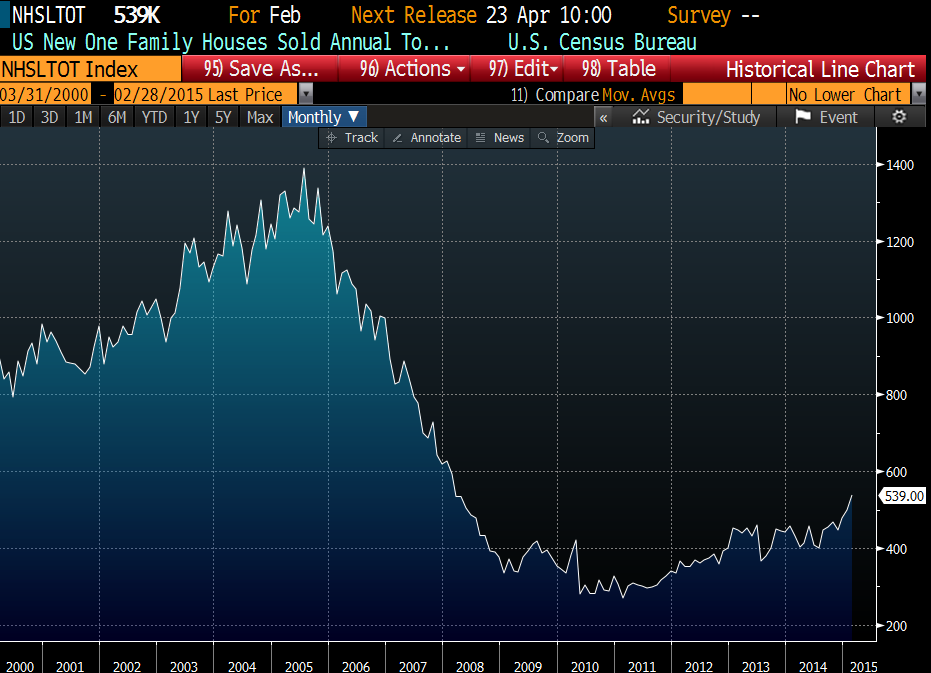
New Home Sales rose in February to a 539k pace from an upward-revised 500k pace in January. New Home Sales are hitting post bubble highs, but are still about 40% of previous peak levels, which were hit about 10 years ago.

On Lennar’s first quarter earnings conference call, CEO Stuart Miller had this to say about new home sales: “Pent-up demand is derived from a now multi-year production deficit that is continuing to grow even at current production levels (emphasis mine) At the same time, volume growth has been constrained by overly conservative lending standards, a regulatory environment that discourages mortgage lending and a negative consumer bias overhang against homeownership….While the relationship between pent-up demand, rental rates and mortgage availability continues to direct the housing market, it’s becoming more apparent that the mortgage market is loosening incrementally with time and enabling more demand to be realized as household formation begins to return to more normalized levels. We have believed and we continue to believe that the downside in the housing market is very limited and the upside is very significant (emphasis mine). We believe that the market is downside supported by the many years of production deficits that have yielded a limited supply of both rental and for-sale housing in the country. Any pullback in the housing market would be short-lived as there’s a need for shelter across the country and there’s very little inventory, and almost no likelihood of mortgage foreclosures (emphasis mine) given the stringent underwriting standards of the past years.

Inflation is still pretty much nowhere to be found, as the consumer price index rose .2% in February. On a year over year basis, it is flat, while ex-food and energy it is up 1.7%. Certainly if the Fed wants an excuse not to hike rates in June, the lack of inflation is giving them one. Note the Fed prefers to use PCE inflation, not CPI.

The Markit US Manufacturing PMI rose in March to 55.3 versus 55.1. Manufacturing continues to rebound, although it doesn’t employ as many people as it used to. Meanwhile one study shows that up to half of all jobs can be automated over the next 10 – 20 years.

The Richmond Fed Manufacturing Index fell to -8 from 0 last month.

Morning Report – Existing Home Sales rise 3/23/15

Markets are flat this morning on no real news. Bonds and MBS are up.

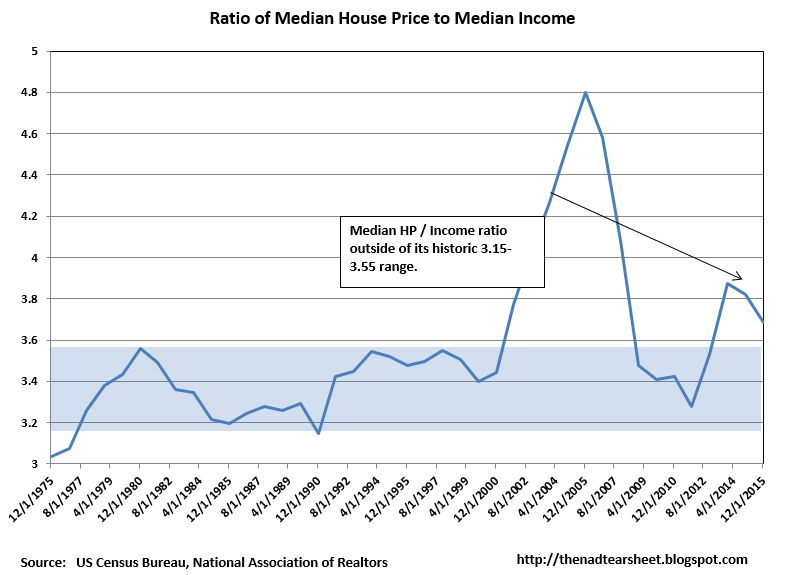
Existing Home Sales rose to an annualized pace of 4.88 million in February, up slightly from 4.82 million in January. Note this is probably a weather-driven number and February is still in the seasonally slow period. The median home price was $202,700 which is up 7.5% year-over-year. Median income is about $55,000 or so, which means the median house price to median income ratio is sitting at 3.68x, which is on the high side. Historically, that ratio has sat in a range of 3.15x – 3.55x. It means that house prices are probably not going to flatten until we start seeing wage inflation.

The Chicago Fed National Activity Index slipped in February as production-related indicators fell. Employment related indicators slipped however were still positive. Poor weather undoubtedly played a role.

The housing reform bill is making its way into the House. This bill, called The Partnership to Strengthen Homeownership Act envisions winding down Fan and Fred, and increasing the role of Ginnie Mae. Private mortgage insurance will bear the first 5% of severity with the government bearing losses beyond that. It sounds like this bill is gaining support of Congressional Republicans as well, however understand this bill is the left’s wish list. The left wants to continue social engineering via the housing market while the right wants to decrease the government’s footprint. The social engineering (aka “affordable housing”) stuff will probably be the biggest sticking point. The plan envisions Ginnie Mae’s 10 basis point guarantee fee will be used for affordable housing goals. Note the government plans to wipe out Fannie and Freddie stockholders, although those two stocks are litigation lottery tickets at this point.

The low price points in urban areas are beginning to decline again. In many urban areas, the suburbs have recovered, while the inner cities remain weak. I wonder how much property in the inner cities was bought by professional investors who are starting to eye the exit. Rental prices continue to rise, but at some point pros will want to monetize these investments. Of course this also demonstrates one of the issues with the CRA: it demands that bankers ignore location when considering the riskiness of the underlying collateral when pricing credit, when location clearly matters.

Morning Report – Lenders more optimistic about 2015 3/20/15

Markets are higher this morning on no real news. Bonds and MBS are up.

Slow news day.

There is no economic data this morning and much of the Street will be exiting early ahead of yet another snowstorm.

Now that we no longer can rely on housing equity extraction to fund consumption, the correlation coefficient between spending and wages is higher than ever.  One more reason why the Fed will probably not begin raising rates too aggressively until we start seeing real wage growth. As of now, we are seeing about 2% annual wage growth versus slightly below 2% inflation. So real wages are in fact growing, just not by much.

Mortgage lenders are more optimistic about 2015 than mortgage consumers, according to the Fannie Mae quarterly survey of lender sentiment.

Morning Report – Stocks and Bonds rally on the FOMC announcement 3/19/15

Stocks and bonds are lower after yesterday’s furious post-FOMC rally. MBS are flattish.

Initial Jobless Claims rose to 291k from 290k last week. Consumer comfort fell to 51.5 from 54, according to the Bloomberg Consumer Comfort Index. In other economic indicators, the Philly Fed Index was largely flat at 5, while the Index of Leading Economic Indicators was flat at .2%.

The Fed did indeed remove the word “patient” from the FOMC statement. However, they noted that growth moderated, which is unsurprising given the weather in the Northeast. They did take down their economic projections for unemployment, GDP, and inflation. 2015. GDP is now forecasted to be in the 2.3% – 2.7% range, which was revised lower from their 2.6% – 3.0% forecast at the December 2014 meeting. Unemployment was taken down to 5.0% – 5.2% from 5.2% to 5.3% in December, and inflation was taken down to 0.6% to 0.8% from 1.0% to 1.6%.

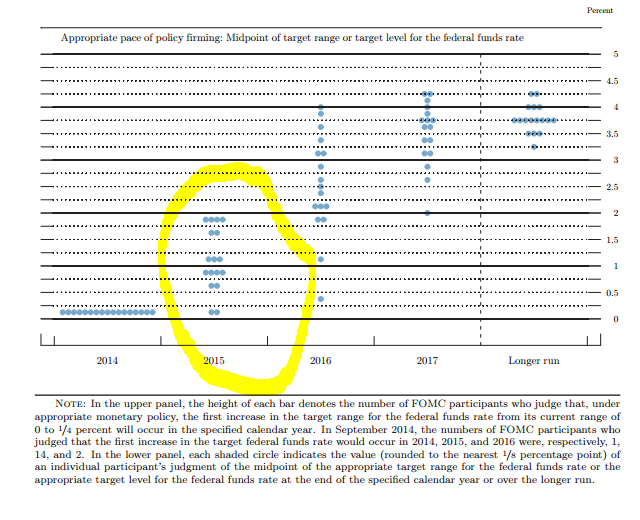
The dot graph was what got the markets all excited. The Fed is forecasting a flatter trajectory to higher rates than they were in December. In the march dot graph, it looks like the median projection by the members is 50 basis points for a year end Fed Funds rate.

Compare that to the December forecast, where the median was closer to 75 basis points or so.

It looks like the 2016 and the 2017 forecasts are slightly lower as well. These dot graphs are what got the market going (although a major bond rally in Europe yesterday probably contributed to the move). Note the makeup of the FOMC is different now than it was in December, and decidedly more dovish. The flatter trajectory for higher rates clearly calmed the markets. The Fed made no change in its plan to shrink its balance sheet. For the time being, they will continue to re-invest maturing proceeds back into Treasuries and MBS.

Homebuilder Lennar reported good earnings this morning. Revenues were up 21%, while gross margins held up surprisingly well at 23.1%. Average selling prices increased about 3% to 326k, which shows that builders have hit the ceiling on price hikes. Incentives increased slightly. New orders were up 18% in units and 25% in dollar value.

Stuart Miller, Chief Executive Officer of Lennar Corporation, said, “Despite severe weather conditions which constrained production and sales in parts of the country, the housing market continued its slow and steady recovery. Early signals from this year’s spring selling season indicate that the housing market is improving, and disappointing single family starts and permits numbers should rebound shortly. The sizable production deficit of the past years continues to drive demand improvement in spite of the constrained mortgage market.” 

Lennar will hold a conference call this morning around 11:00 am. The stock is up about a buck and quarter (or about 2.5%)

Morning Report – Fed Day 3/18/15

Stocks are lower this morning as we await the Fed’s decision at 2:00 pm. Bonds and MBS are higher as worldwide sovereigns mount a ferocious rally. Oil continues its slide, down $1.20 a barrel to $42.26.

While the Street will undoubtedly focus on the removal of the word “patient” from the FOMC statement, Janet Yellen will probably stress that this change in language merely opens the door for a June rate hike, and does not mean they have already decided to do so. The Fed will remain data-dependent and will probably want to see some sort of rebound from the weather-driven weakness of Q1. It is interesting to see the US exit ZIRP when countries like Sweden are implementing NIRP, where the Riksbank cut rates to -0.25%.

Mortgage Applications fell 3.9% last week. Purchases fell 1.5% while refis fell 5.2%. This was the week after the jobs report where interest rates spiked to 2.24% and then slowly came back.

Macroeconomic bellwether FedEx reported better than expected numbers this morning, however it took down 2015 numbers based on dollar strength. This will probably become a bit of a trend as we enter pre-announcement season and the big multinationals take down their full year forecasts. Earnings season is only two weeks away.

Morning Report – Housing Starts disappoint 3/17/15

Markets are lower this morning as housing starts disappoint and oil continues to fall. Bonds and MBS are up.

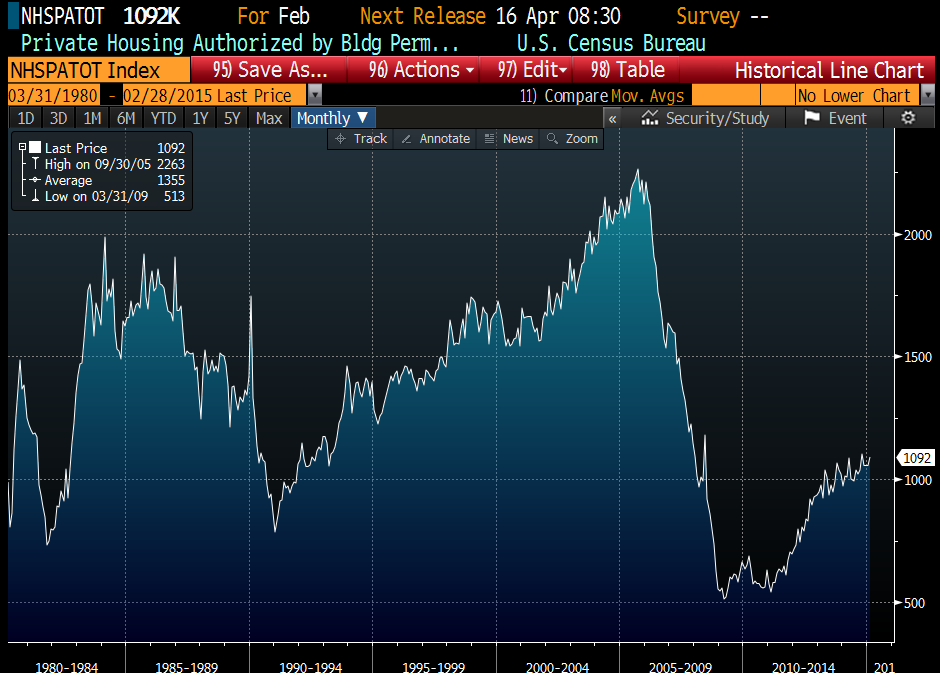
Housing Starts fell to an annualized pace of 897k in February from an upward-adjusted 1.08 million in January. While it is tempting to blame this on the weather (and undoubtedly some of this is due to the weather), you had an 18% drop in the West as well. Building Permits rose to 1.09 million, however from an upward revised 1.06 million. While this is an improvement from the post-bubble years, we are still operating well below historical norms.

Today begins the two-day FOMC meeting. Aside from the word patient, the Street will be focusing on the Fed’s economic projections, particularly inflation. At the December FOMC meeting, the Fed was projecting GDP growth of 2.6% – 3.0%, unemployment of 5.2% to 5.3% and PCE inflation of 1.0% to 1.6%. Given that six of the last seven PPI prints have been negative, it will be interesting to see what the Fed does with their inflation forecasts. If it gets too low, will the Fed hold off raising rates? Certainly the dovish wing of the FOMC will argue for caution.

Great article on the bubblicious tech company valuations. All sorts of games are being played in order to boost the valuations of companies like Uber, AirBnb, Dropbox, etc. Mark Cuban has described the current bubble in these private companies to be bigger than the internet bubble of the late 90s. FWIW, Henry Blodgett (who would know a thing or two about bubble valuations) thinks Uber could go public at $50 – $100 billion in a few years. That makes it worth about the same as Allergan or ConocoPhillips.

Morning Report – All we need is a little patience 3/16/15

Markets are higher as oil continues to fall. Bonds and MBS are up small.

Industrial production rose .1%, lower than expectations, however that was probably due to the weather. Capacity Utilization fell to 78.9%, which was negative as well. Weather probably had a lot to do with the disappointing numbers, but January’s numbers were revised downward in a big way, with industrial production being revised to -0.3% from 0.2% and capacity utilization revised from 79.4% to 79.1%.

Homebuilder Sentiment fell to 53 in March from 55 in February.

This week is all about the word “patient.” The FOMC meets Tuesday and Wednesday and the Street will be keying on the word “patient” – in the context of “The Fed can be patient in waiting to raise rates. Janet Yellen characterized patient to mean “two more FOMC meetings.” In other words, if the word is gone from the statement, the market will take it to mean the Fed is moving in June. Given this is a March meeting, we will have updated projections for GDP, unemployment, and inflation as well as a press conference.

The biggest issue facing the Fed is wage growth. Why are we not seeing wage growth with unemployment pushing “full employment?” It is a vexing question. The answer is that we have a huge reservoir of people who are considered not part of the labor force, but want to be. As these people return to the labor force, wage inflation will remain low until these people are all employed. Mark Zandi of Moody’s believes that this will take about a year, and by this time next year, we will start seeing wage inflation.

US Treasuries are getting a bid courtesy of the Japanese, who are selling JGBs to pick up yield wherever they can. US debt probably provides the best value out there.

OT: Shameless Plug: Did you know financial professionals rock? This one does. Check out my entry for the Jamtrackcentral 2015 guitar solo contest and give me a like. I appreciate it.

Morning Report – 2015 could be the best year for housing since 2007 3/13/15

Markets are lower this morning on no real news. Bonds andMBS are flattish.

Inflation at the wholesale level remains nowhere to be found, as the Producer Price Index fell .5%. You can’t blame this on oil, as the index fell .5% ex-food and energy. Six out of the last seven months have been negative on the headline number.

Consumer sentiment fell to 91.2 from 95.4 in February, according the University of Michigan. Current conditions are down, but expectations fell quite a bit. Does a lot of snow make people depressed?

Freddie Mac is saying that 2015 could be the best year for housing since 2007. Given the carnage in housing over the past 8 years, that is like discussing the best season for the Detroit Lions under Matt Millen. They are forecasting housing starts of 1.18 million, mortgage originations of $1.3 trillion (of which 40% are refis), and home sales of 5.6 million.

The NYT has a good article on parsing the Fed’s language. Next week we will get the FOMC decision, and everyone will be looking for the presence of absence of the word “patient.” (In the context of “the Fed can be patient in raising interest rates.). If that word is removed, the market will take it to mean the Fed will hike rates at its June FOMC meeting. For LOs with borrowers who are floating, let them know that next Wed could be a big day in the bond market.