Morning Report: Hospital Thataway 4/15/15

Markets are higher this morning as ECB President Mario Draghi speaks and bank earnings continue to trickle in.

Mortgage Applications fell 2.3% last week. Purchases were down 3.1%, while refis were down 1.8%.

Some weaker economic data this morning: the Empire Manufacturing Index fell steeply in April, to -1.19 vs. 6.9 expected, while industrial production fell .6% and capacity utilization fell to 78.4%. Can’t blame this on the weather – blame the dollar.

Bank of America reported that mortgage originations increased 18% QOQ and 54% on a YOY basis. Between JPM, BAC, and WFC, it looks like the mortgage business is improving quite a bit. Maybe the long-awaited turn in the real estate sector is upon us. We will get more data tomorrow with housing starts and building permits.

Hillary officially launched her campaign over the weekend, unveiling her new logo, which looks like “Hospital Thataway.”  Suffice it to say, the H logo appears to be a bomb, and the interwebs are already making fun of it.

Best one so far:

original

Morning Report – Bank earnings pile in 4/14/15

Markets are lower this morning as bank earnings pile in. Bonds and MBS are up on the back of a strong bond market rally in Europe.

Retail Sales came in weaker than expected, although some of that is due to falling commodity prices (especially gasoline). The headline number was +0.9% versus +1.1% expected. The control group, which strips out some of the more volatile components increased .3%.

Wells reported that originations increased to $49 billion in Q1 versus $44 billion in Q4. Margins expanded, with gain on sale margins increasing from 1.80% to 2.06%. Given that mortgage banking is so seasonal, it is surprising Wells reports quarter over quarter comparisons. J.P. Morgan reported first quarter originations were up 7% QOQ and up 45% YOY. MSR valuations got hit – their MSR book is valued at 2.53x versus 2.8x at the end of the year and 2.86x last year.

Inflation remains muted at the wholesale level, with the Producer Price Index coming in at .2% month-over-month and falling 0.8% year over year. While the Fed prefers to look at Personal Consumption Expenditure Inflation instead of CPI / PPI, markets still pay attention. This is the other reason why bond yields are so much lower this morning.

Things are still somewhat “meh” for small business, according to the National Federation of Independent Business. The NFIB attributes some of the weakness to the weather.

We haven’t talked about European bond yields in a while, but they continue to fall, which is keeping a bid under Treasuries. The German Bund (their 10 year bond) yields 13.7 basis points. The Swiss 10 year yields negative 12.4 basis points. Yes, it will cost you money to lend to the Swiss government for 10 years. How about the PIIGS (remember them? Portugal, Ireland, Italy, Greece, and Spain) The Irish 10 year yields 68.3 basis points. The US 10 year yield is higher than all but one of the erstwhile PIIGS – Greece.

Bubbles, bubbles everywhere, but especially in Asia. where the Chinese real estate bubble is beginning to deflate, and the Chinese economy begins to slow. Asian stocks are ignoring this however – the Nikkei 225 is up 43% over the past year, while the Hang Seng is up almost 11% in the first two weeks of April. While these markets are still well below their all-time highs, and no one is suggesting stock market bubbles, the Asian markets look frothy. China’s real estate bubble is epic and as it bursts, China will export deflation around the world. Yet another reason for the Fed to sit on their hands.

But we don’t have any bubbles in the US, right? Well, according to Bill Ackman, we do. The student loan debt market is about $1.3 trillion all in, and about 9% is in default. As he points out, there is almost no way that gets repaid. He sees some administration doing a mass debt forgiveness.

Morning Report – GE is exiting financial services 4/10/15

Stocks are higher this mornings on no real news. Bonds and MBS are up.

Import prices fell .3% in March and are down 10.5% year over year. As we are seeing in the data elsewhere, the strong dollar is beginning to affect the economy. Q1 earnings will be interesting – how many multinationals will report weaker numbers due to weaker overseas demand.

GE is ending its decades-long dalliance into financial services, by selling its lending business and real estate assets. GEFS basically has been a Old timers will remember when GE owned an investment bank – Kidder Peabody – which blew up in the 90s. Investors like the news – GE is up about 7% pre-open.

Hillary Clinton announced she will announce her candidacy on Sunday, supposedly via Twitter. Are you ready?

Christine Lagarde of the IMF is warning that the financial markets could get bumpy when the Fed starts raising rates. Consider this: the Fed hiked rates in 94, 99, and 05. In the process, they blew up the MBS market (remember Orange County?), the stock market, and the real estate market. Asset prices are handicapping a 100% probability that the Fed can raise interest rates without any one blowing up. The Fed may in fact be able to stick the landing and exit ZIRP without a crisis, but that is not a foregone conclusion. The old market saw of “sell in May and go away” may turn out to be good advice this year.

Morning Report – FOMC minutes review 5/9/15

Stocks are lower this morning as the ECB raises aid to Greece. Bonds and MBS are flat.

The FOMC minutes really didn’t have much new information in it and bonds ignored the release for the most part. The decision to remove the word “patient” was not intended to signal that a raise is imminent, just that they will continue to be data-dependent. The strong dollar is beginning to have an effect on the economy, or at least the big multinationals. The stronger dollar is what drove them to revise their near-term GDP forecasts down.

They didn’t discuss housing much except to say that the pace of activity was “slow” and noting the decrease in starts. FWIW, the homebuilders seem to be seeing a bit brighter picture. We’ll get a better idea when D.R. Horton and Pulte report in a couple of weeks. Regarding credit, they said that credit conditions were pretty much easy for everything but mortgages, where credit remains tight. For borrowers who can qualify, rates are low.

Alcoa kicked off earnings season last night with a miss on the top line as demand for aluminum is expected to grow at 6.5% in 2015 compared to 9% last year. They see a glut lasting through 2015. Interestingly, Alcoa continues to shutter production while China increases output. They already have tremendous overcapacity in steel, and are contending with a deflating real estate bubble.

Initial Jobless Claims came in at 281k, more or less in line with expectations. The Bloomberg Consumer Comfort Index rose to 47.9. Wholesale inventories rose while sales fell in February.

Consumers are getting a little more bullish on housing, according to the Fannie Mae National Housing Survey. They expect home prices to rise 2.7% over the next 12 months. Last February had a blip where more people thought the economy was on the right track than the wrong track, but it has reverted back to normalcy.

Morning Report – Awaiting the FOMC minutes 4/8/15

Markets are higher this morning as we await the FOMC minutes. Bonds and MBS are up small.

Earnings season kicks off this afternoon with the traditional report from Alcoa. The deluge of releases begins next week with the banks reporting.

The FOMC minutes will be released around 2:00 pm. The markets will be focusing on the discussion around the removal of the word “patient” and will also want to see if the Fed believes that the Q1 weakness was transitory or not. The “weather” excuse has worn out its welcome given that the March data (payrolls especially) came in weaker than expected. The Street has been backing away from their forecast of a June rate hike, and Goldman has it as a toss-up between September and December.

The elephant in the room will be the Fed’s massive bond portfolio. The Fed owns $4.2 trillion worth of Treasuries and MBS. They have already said they do not plan to sell their MBS holdings, but Treasuries are more interesting. As of now, all maturing proceeds are being re-invested back in the market. Next year, about $216 billion will come due, which is about 5 months worth of peak QE buying.

The other big concern at the Fed is the shape of the yield curve. They generally prefer a steeper, upward sloping yield curve. The fear is that an increase in short term rates would make the dollar so attractive that foreign money piles into Treasuries, making the yield curve flatter.

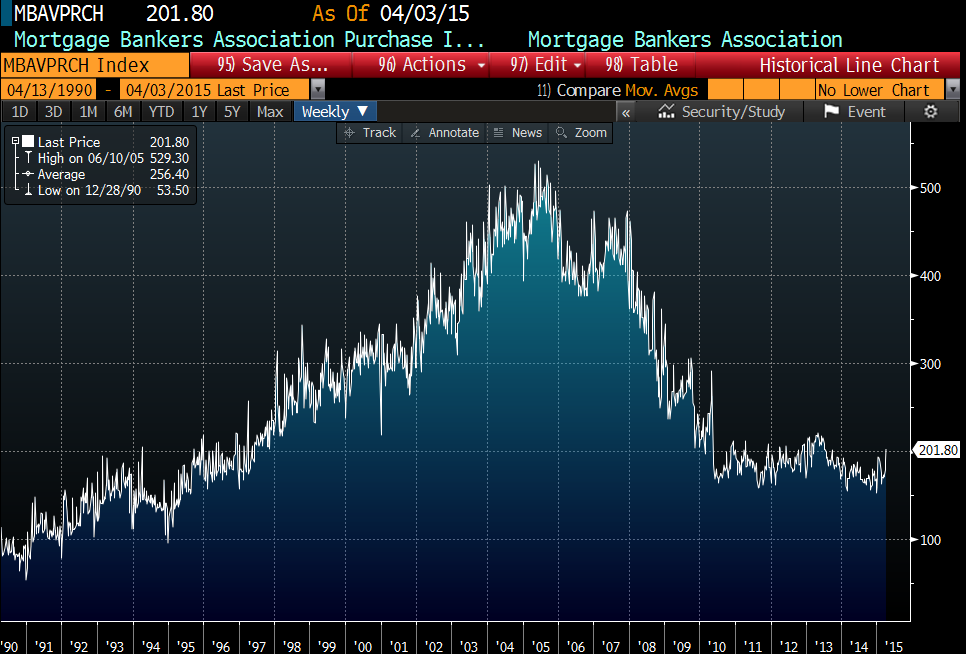
Mortgage Applications increased .4% last week, which is impressive because it was a short week. Purchases were up 6.8% while refis were down 3.3%. Purchases are the highest they have been since early 2013, which bodes well for the spring selling season. That said, we are still way below normalcy, and you would have to go back to 1997 to see similar levels pre-bubble.

Morning Report – The low end of the housing market is outperforming 4/7/25

Markets are flattish this morning on no real news. Bonds and MBS are down small.

The ISM Services index slipped to 56.5 in March, while job openings hit their highest yet at 5.1 million.

It looks like the big bond rally on the weak jobs report was overdone. That said, there is no denying it was a lousy report, with payrolls coming in at 126k versus 245k expected, and the labor force participation rate falling back to its post-disco lows of 62.7%. About the only bright spot was the increase in wages. Can’t blame this jobs report on the weather, although we may be starting to feel the effects of the stronger dollar.

Tomorrow, we will get the minutes from the FOMC meeting last month. The focus will be on the thinking behind the removal of the word “patient.” Given the weakness in the economic data lately, the Fed may choose to make its first move in September.

We are starting to see the low end of the housing market outperform the high end, according to CoreLogic. Prices rose 5.6% in February and remain about 12% below the peak. House prices at the lower price points increased over 9%, while the high end increased about 5%. CoreLogic says this is the hottest price appreciation prior to the Spring Selling Season in 9 years. They are forecasting another 5% increase in prices this year.

Morning Report – ADP Employment misses 4/1/15

Stocks are lower this morning after the ADP jobs data came in light. Bonds and MBS are up.

Construction spending fell by .1% in February and January was revised down by 1.7%. Residential construction continues to lag the economy, however office construction is picking up. Surprising since vacancy rates are still somewhat elevated.

The ISM Manufacturing Index fell to 51.5 in March, showing some of the slowdown is not simply weather-related.

Payrolls increased by 189k in March, according to ADP. The Street is currently predicting that Friday’s jobs report will show an increase of 245k. Note that the government will be open on Good Friday however the stock markets will be closed and bonds will have an early close. We could see some volatility in bonds if the payroll data is unusually weak or wage inflation in unusually high.

It looks like the dumb money is piling into the Chinese stock market, and much of it is leveraged. This was after the government started telling people that stocks were cheap. The government already has problems with an over-built real estate market and is pulling policy levers to support prices. Historically governments have never been able to manage the deflation of asset prices in an orderly manner, and it is unlikely the Chinese government will be able to either. Their banking system is already on shaky ground. What that means for the US is unclear. We should see Chinese money exit the luxury real estate market in the US, but what happens to Treasuries is anyone’s guess.

Student loan debt is a big problem for the first time homebuyer, as everyone knows. At the same time, there is a movement to begin debt strikes, where students refuse to pay back their loans. At the moment, it is limited to the failing private for-profit universities, however if this gains traction, it could spread. The left, led by Elizabeth Warren, has been egging this on a bit, but they are playing with fire. The government backs these loans and will have to eat the losses if this movement grows.

Morning Report – More bond market volatility ahead? 3/31/15

Markets are lower on no real news. Bonds and MBS are up.

Home Prices rose .87% month-over-month and 4.56% year-over-year according to Case-Shiller. This is January data. The West and Southwest continues to outperform the Midwest and Northeast. A measure of housing market “healthiness” indicates the housing market is in the best shape since 2001.

It looks like we are close to an agreement to extend talks with Iran for 90 days and to outline the big steps needed to get a deal. The main sticking points seem to revolve around the actual mechanics of lifting the sanctions. The main thing to keep in mind is that one way or another, the sanctions will probably be lifted and a big new oil producer will begin dumping crude on world markets.

As we get closer to “liftoff,” which is Fed-speak for increasing interest rates, market professionals are worried about the possibility of more volatility in the bond markets. They point to one trading day in October, where the 10 year bond yield traded in a 40 basis point range intraday. A combination of automated trading and the unintended consequences of regulation have hampered liquidity in Treasury markets during periods of volatility.

Speaking of bond market volatility, the government will release the jobs report on Friday as scheduled, however the stock market will be closed and SIFMA is recommending a noon close in bonds. Suffice it to say that trading desks will be thinly staffed and we could see some volatility in rates. I don’t anticipate much of a reaction in the bond market unless payrolls fall off a cliff or we see a big uptick in wages.

Morning Report – Ben Bernanke has a blog 3/30/15

Markets are higher this morning on overseas strength. Bonds and MBS are up small.

Personal Income came in at .4%, higher than the Street estimate. Personal Spending however disappointed. The PCE Core rate (the inflation rate preferred by the Fed) came in at 1.4%, lower than the Fed’s 2% target.

Pending Home Sales rose 3.1% in February, higher than the estimate. The Northeast was affected by the weather, but the Midwest jumped. February is a short month and during the seasonal slow period, so it is hard to read too much into these numbers.

Beard has a blog. Supposedly he will dish on his critics and go after the “audit the Fed” crowd. It might be interesting as a “Talking Points Memo” on monetary policy, where surrogates argue with critics, leaving the official participants out of it.

Morning Report – Q4 GDP disappoints 3/27/15

Markets are lower this morning after the final revision to fourth quarter GDP came in lower than expected. Bonds and MBS are up.

The final revision to fourth quarter GDP came in at 2.2%, flat with the second revision and below the 2.4% street estimate. Personal Consumption was revised upward to 4.4% from 4.2%. The core Personal Consumption Expenditures Index (the preferred measure of inflation for the Fed) came in at 1.1%, well below their 2% target.

The University of Michigan Consumer Sentiment index rose to 93 in March.

At 1:30 Janet Yellen will be speaking in San Francisco about monetary policy. She probably won’t say anything market-moving, but just be aware.

Senate Minority Leader Harry Reid is retiring. NY Senator Chuck Schumer is the favorite to replace him. NV will almost undoubtedly swing Republican. Schumer is generally financial sector friendly, so that should help the business, for what it is worth. Democrats are worrying about 2016 and the fact that their war on Wall Street means banks are pulling back campaign contributions. Also, affordable housing advocates are getting sick and tired of tight credit.

Reinhart and Rogoff have another paper about high levels of government debt. It looks at how governments have handled these situations over the past two centuries. Governments will need to be creative in dealing with it, and the solutions will probably involve confiscatory taxes, default, and inflation.