MEET PUPPA, MY CHRISTMAS MIRACLE

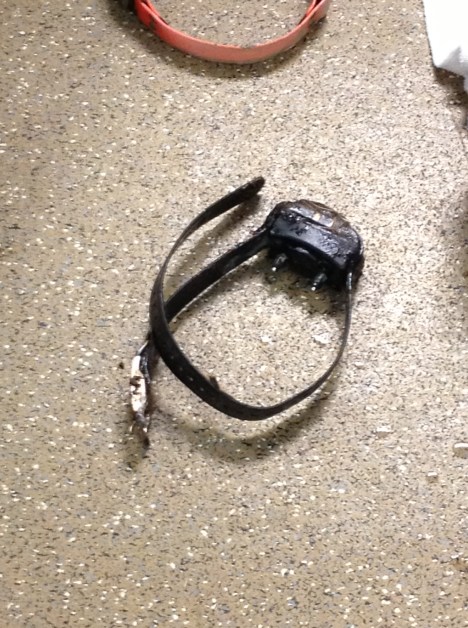
I hope everyone’s holidays are going well. I wanted to show you some pictures of a dog my wife and I rescued, we call him Puppa. About 6 months ago he showed up in my neighborhood, starving and looking forlorn. Whoever had him had put a shock collar on him:puppa starving
Puppa was very scared of people, yet wanted companionship. If you walked a dog, he’d follow you, but at a distance of no less than 10 feet. We took to feeding him, he loves hot dogs, and leaving out water. It took us two months to lure him over to my street and in front of my house. We couldn’t catch him however. No matter what we did, he’d never come any nearer than 10 feet. we even got some tranquilizers from my vet, with no luck. On Christmas morning I went out to feed him his holiday hot dogs when a SUV approached me, a woman inside asked me if Puppa was my dog. I told her it was a stray that I’d been trying to catch. It turns out she lives in an adjoining subdivision, works for a private animal rescue, and had noticed Puppa on a walk with her dog. She agreed to set up a trap that day, and if we caught him, to get him to the vet. Well, sure enough it worked! That afternoon, Puppa was in the trap!puppa trapped
The vet cut off the shock collar:photo (94) though I wont torture you with pictures of the horrible wound it left.

I take Puppa home on Wednesday and have visited him everyday. Yesterday he put his paw on my hand: Puppa

I haven’t had all that great a year, but it sure is ending well.

I miss commenting here, so I am going to resume

Merry Christmas and a Happy New Year!

George

Morning Report – On the Waterfront Edition 12-28-12

Vital Statistics:

  Last Change Percent
S&P Futures  1401.8 -8.9 -0.63%
Eurostoxx Index 2633.2 -26.8 -1.01%
Oil (WTI) 91.01 0.1 0.15%
LIBOR 0.308 -0.003 -0.96%
US Dollar Index (DXY) 79.81 0.188 0.24%
10 Year Govt Bond Yield 1.70% -0.03%  
RPX Composite Real Estate Index 192.3 0.0  

Stock index futures are lower on pessimism about a budget deal. Obama will meet with Congressional leaders today to see if they can hammer out a deal. The House will meet on Sunday night. The same story remains – stocks are worried about going over the cliff, while the bond market seems skeptical.  For a laugh, check out Rick Santelli’s rant about the way the markets are handicapping it. 

One other possible headwind for the economy in Q1 – a longshoreman’s strike that would close cargo ports on the Eastern Seaboard and the Gulf Coast. This would not only limit raw material supplies to US factories, it would also push many logistics workers, truck drivers, etc on to the unemployment rolls. Some economists estimate that a strike could cost the US economy $1 billion a day. Will Obama risk alienating his labor base to intervene?  Fun fact:  the average compensation for a longshoreman in $124k.

Yesterday’s consumer confidence numbers took a step downward, and seem to back up reports that this year’s holiday sales were weak.The outlook for business conditions and labor markets fell. 

Chart:  Conference Board Consumer Confidence:

 In spite of the pessimism over the fiscal cliff, luxury homes priced over $1 million are making a comeback. Sales have risen by 9% for the first 9 months of 2012.  Strong foreign demand has been driving up prices in Manhattan and the Hamptons. In terms of foreclosures over $1 million, the NYC suburbs hold 4 out of the top 10 zip codes, with New Canaan taking the lead.  This is still the wreckage from the bust, where lots of $1 million a year guys lost their jobs in 2007 and haven’t worked since.

Morning Report – the Mod Squad 12-27-12

Vital Statistics:

Last Change Percent
S&P Futures 1416.2 2.7 0.19%
Eurostoxx Index 2665.1 16.6 0.62%
Oil (WTI) 91.18 0.2 0.22%
LIBOR 0.311 0.001 0.32%
US Dollar Index (DXY) 79.44 -0.182 -0.23%
10 Year Govt Bond Yield 1.77% 0.01%
RPX Composite Real Estate Index 192.3 0.5

Markets are quiet again as desks are understaffed both in Europe and the US. Initial Jobless Claims fell to 350k, back to the bottom end of our 350k – 390k range. Bonds and MBS are down small and continue to dismiss the possibility of a cliff-induced recession.

President Obama heads back to Washington to try and craft a deal to avert the fiscal cliff. The WH seems to have backed off its proposal to increase taxes at 400k and has moved back to 250k. It is looking more and more like we will go over the cliff on Jan 1 and then pass some sort of tax cut package soon thereafter.  Treasury informed Congress that we will hit the debt limit on Monday, but they can play some games to keep the government funded through Feb.

Of course, once we climb the fiscal cliff, we will go right into the battle of the debt ceiling. Moody’s has already fired a shot across the bow, saying that they expect the government to raise the limit, but they may downgrade the U.S.’s credit rating unless we get a decrease in the debt / GDP ratio.

Yesterday’s WSJ report on possible new initiatives to mitigate the effects of the housing bust have already been met with skepticism. The first plan involved allowing deeply underwater non-agency loans to refi into Fan and Fred loans.  James Pethokousis of the American Enterprise Institute points out that allowing the GSEs to refi underwater non-agency mortgages is a non-starter with virtually all Republicans and many Democrats as it shifts risk from the private sector to the public sector.  Plus, you have to get the originators on board, and they won’t make 125%+ LTV loans without some sort of safe harbor against buyback risk.

A second plan would further expand HAMP, by changing the definition of “in danger of imminent default” to include anyone who is has a LTV over 125%, even if they are current on their mortgage. Such a move would not require Congressional approval. The American Securitization Forum is against the idea, given that these loans are worth their weight in gold.  They are current, have above-market coupons, and have virtually no chance of being prepaid for years. If enacted, investors would take an income hit (although Treasury would pay them the coupon difference for 5 years), and would see a capital loss as well. My sense is that ASF’s argument will be met with very little sympathy in the Administration, although state and federal pension funds will be quietly making the same argument as well. Still another hurdle would be servicers, who would have to buy off on the idea that modding a current loan is somehow good for the investor.

Morning Report – Case-Schiller 12/26/12

Vital Statistics:

  Last Change Percent
S&P Futures  1422.7 2.9 0.20%
Eurostoxx Index 2648.5 -2.6 -0.10%
Oil (WTI) 89.09 0.5 0.54%
LIBOR 0.31 0.000 0.00%
US Dollar Index (DXY) 79.66 -0.015 -0.02%
10 Year Govt Bond Yield 1.78% 0.00%  
RPX Composite Real Estate Index 191.8 0.1  

Markets are quiet this morning, as most of Europe is shut for Boxing Day. Bonds and MBS are flat.

Not much is happening on the fiscal cliff front, although Obama plans to cut his vacation short and return to Washington to try and hammer out a deal. Chances of any sort of grand bargain are virtually nil; all that could be accomplished at this point is some sort of fig leaf. In spite of the political and economic uncertainty, and the early indications of a weak Christmas, the bond market still refuses to price in the possibility of a recession. 

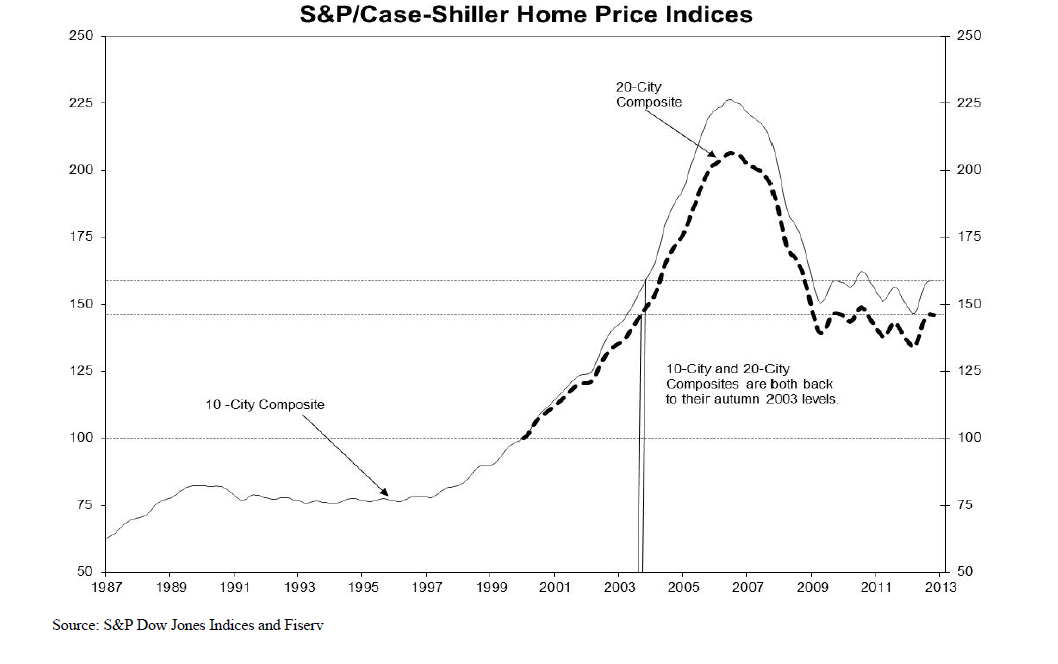
The S&P / Case-Schiller index of home values came in at  145.93 for the month of October, up 4.3% year-over-year and up 66 basis points month-over-month. The hardest-hit MSAs continued to show the biggest gains, with prices up 22% in Phoenix and 10% in Detroit. The Northeast MSAs (Boston and NY) are showing the smallest increases.

Chart:  S&P / Case-Schiller:

The Obama administration is considering expanding its mortgage-refinancing program to include underwater borrowers with non government loans.  Such a move would require legislation to change Fannie and Fred’s charters and would also involve a bump in the guarantee fee to price in the additional risk. It will also require the blessing of FHFA, which has indicated general support for the program.  Finally, it will require some sort of immunity from buy-back risk in order to get originators on board. 

A new study confirms what many have thought about high-frequency trading:  It is highly profitable and adds no value to the system as a whole. Aggressive, liquidity-taking high frequency trading (in other words, front-running) does the best. The profitability of HFT seems to be persistent – new entrants are less likely to be profitable and are more likely to exit. Speed matters above all, and that is why James Simons is so consistently profitable.

Merry Christmas, ATiM

This is Christmas!

So, Mark, does your family do what Elena Kagan does (or at least claimed she does in her confirmation hearings) and get Chinese food on Christmas day?  I think “Seinfeld” was where I heard that first.  And there’s always “A Christmas Story” and the introduction to Chinese turkey:

For some reason I can’t find either of these whole cartoons on youtube, but here’s the part that’s the core of the Charlie Brown special,

and here’s my very favorite song of the season

Don’t ask me why, but that song just struck me as wonderful when I was a little kid.  My parents tell me that I would get up and dance around to it every year when we watched the special on TV–maybe it’s that amazing bass voice.  But it’s also hard to top Nat King Cole:

At any rate, I hope that this holiday season has been a joyous, peaceful, and love-filled one for all of you.  And may 2013 be even better!

Morning Report – Merry Christmas edition 12/24/12

Vital Statistics:

Last Change Percent
S&P Futures 1421.8 -4.1 -0.3%
Eurostoxx Index 2648.3 -3.0 -0.15%
Oil (WTI) 88.38 -0.28 -0.31%
LIBOR 0.31 0.000 0.00%
US Dollar Index (DXY) 79.46 0.156 0.15%
10 Year Govt Bond Yield 1.77% +0.04%
RPX Composite Real Estate Index 191.8 -0.1

Markets are quiet this morning as most shops have skeleton crews on the desk.  Stock and Bond markets will be open until 1:00 pm.  There is no economic data this morning. Bonds are down while MBS are flat.

The fact that bonds have not rallied in the face of the machinations of the fiscal cliff has me scratching my head. Mohammed El Arian of PIMCO believes a recession is now more likely. If we enter a recession, we could be looking at a 1.25% 10-year.  We broke 1.4% in late July. Yet here we sit at 1.77%.  Liquidity is typically low this time of year, so you can’t read too much into it, but unless we get a deal on the cliff soon, we could be looking at a big rally in Treasuries come January.

With the collapse of Boehner’s Plan B, all attention turns to the Senate which hopes to devise some sort of band aid to prevent the worst of the fiscal cliff. In particular, Mitch McConnell has been more of an observer than a participant as negotiations have centered on the WH and House. Apparently Joe Biden has better luck dealing with the Minority Leader than Obama, and has earned the reputation as the “McConnell Whisperer.” Democrats are urging Boehner to re-enter negotiations with a bipartisan bill. Ironically, by rejecting Boehner’s Plan B, Tea Party Republicans in the House have lost their seat at the table.

Lender Processing Services is out with their first look at November delinquency numbers. Delinquencies are up sequentially, while foreclosures are down.

The Fed is disappointed that mortgage rates are not responding to the Fed’s MBS purchase program. At least the story mentions the reason – increases in guarantee fees. Most stories about this (The Washington Post is absolutely terrible on this) don’t mention the fee increase. Even the WSJ does it, by mentioning “higher fees charged by Fan and Fred” in a generic fashion, as if they are inconsequential.  People don’t understand how much G-fees matter. There is the perception in Washington that lenders are simply pocketing the difference when in reality their costs have increased. The media has glommed onto the idea that the financial industry is inherently crooked and there is no disabusing them of that.

Merry Christmas to all.

Morning Report – Over the cliff we go 12/21/12

Vital Statistics:

  Last Change Percent
S&P Futures  1418.4 -22.2 -1.54%
Eurostoxx Index 2645.3 -13.0 -0.49%
Oil (WTI) 89.04 -1.1 -1.21%
LIBOR 0.31 0.000 0.00%
US Dollar Index (DXY) 79.38 0.116 0.15%
10 Year Govt Bond Yield 1.75% -0.04%  
RPX Composite Real Estate Index 191.8 -0.1  

Stock index futures are getting crushed this morning after House Speaker John Boehner postponed a vote for Plan B, which would have raised taxes on millionaires, after he couldn’t get enough Republican votes.  He has scheduled a press conference for 10:00 am. This is probably the final nail in the coffin for a deal before the end of the year.  It also could mean Speaker Cantor.  

So, what are the options now on the fiscal cliff?  John Boehner could continue to work with the President on a deal that can garner bipartisan support in the House.  Second, the House could pass the Senate bill, with Republicans voting “present.” Finally (and probably the most likely outcome) is that we go over the cliff and immediately pass tax cuts in the new year. It goes without saying that all of this is dependent on the world not ending today.

On the economic data front, Personal Income and Spending came in better than expected.  Durable Goods were higher than expected and the Chicago Fed National Activity Index rebounded. Of course none of that matters right now. Bonds are up a point, while MBS are up 1/4. In view of what is happening in Washington, I wouldn’t want to be short bonds right now.

Morning Report: Merger Mania on Wall Street 12/20/12

Vital Statistics:

Last Change Percent
S&P Futures 1430.2 -2.9 -0.20%
Eurostoxx Index 2654.9 0.2 0.01%
Oil (WTI) 89.7 -0.3 -0.31%
LIBOR 0.31 0.000 0.00%
US Dollar Index (DXY) 79.12 -0.145 -0.18%
10 Year Govt Bond Yield 1.78% -0.03%
RPX Composite Real Estate Index 191.8 -0.1

Markets are slighly lower after a slew of economic data this morning.  3Q GDP was revised upward to 3.1%.  Initial Jobless Claims came in at 361k. Consumption rose 1.6%.  The November Index of Leading Economic Indicators fell .2%.  Bonds and MBS are flat.

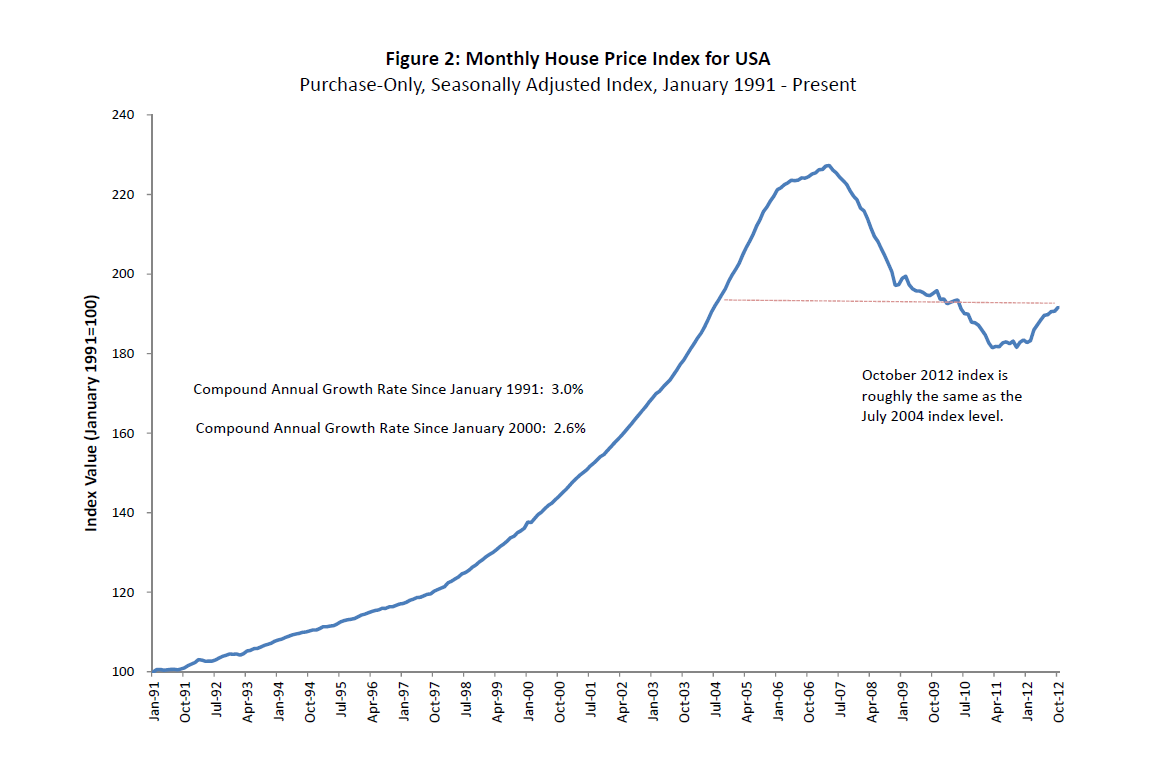
The FHFA House Price Index rose a half of a percent in October.  Sep was revised downward.  Prices are up 5.6% YOY and the index is 15.7% below its peak in April 2007.  We are more or less back to Summer of 2004 levels.

 The Intercontinental Exchange (ICE) has agreed to buy NYSE Euronext for $8.2 billion.  It shows just how much the importance of trading equities has fallen.  Who would have thought a 12 year old scrappy upstart from Atlanta would end up buying the New York Stock Exchange, Paris Bourse, and the Amsterdam Exchange?  The floor of the New York Stock Exchange is more or less just a museum these days.  Separately, Knight Capital Group, the Nasdaq market-maker which lost $460 million on a computer glitch earlier this year, agreed to deal with Getco, the Chicago-based leader in high frequency trading.

On the fiscal cliff front, the House plans to vote on a measure that increases taxes on millionaires.  Obama has already threatened to veto it. The current bid / ask spread is 400 – 1000, meaning that Obama wants the threshold for higher taxes to start at 400k, while Boehner wants it to start at 1 million. Bloomberg has a good backgrounder on the relationship between Obama and Boehner.

KB Home announced their 4th quarter and full year earnings this morning.  Deliveries were up 6% and average selling prices increased 10% sequentially and 23% year-over-year. Backlog is up 35% and that potential revenue would be the highest since Q407. Larger homes were the driver, which accounts for the jump in ASPs.

Hometown in the NYT

A new mixed-used town center that I frequent was featured in the NYT. Thought I’d pass along so those who are interested can get a sense of life inside (or in this case barely outside) the beltway. My home is about 10 minutes from here. With the new HOT (High Occupancy Toll) lanes on the beltway, it’s about 3 mins and 30 cents. Or free if the whole entire family is in the car. If the development continues, it will be accessible by bicycle. Too much traffic for that now.

The story neglects the best part of the movie theater: the full service bar.

We considered the town homes that are for sale, but decided to stick with our home.

Morning Report: Fannie Mae’s 2013 forecast for economics and housing 12/19/12

Vital Statistics:

  Last Change Percent
S&P Futures  1445.2 4.1 0.28%
Eurostoxx Index 2659.8 16.3 0.62%
Oil (WTI) 88.4 0.5 0.53%
LIBOR 0.31 0.001 0.32%
US Dollar Index (DXY) 79.04 -0.319 -0.40%
10 Year Govt Bond Yield 1.82% 0.00%  
RPX Composite Real Estate Index 191.9 0.2  

Markets are higher this morning on optimism over the fiscal cliff.  John Boehner introduced a Plan B yesterday in case bipartisan talks fail, but markets / observers still seem optimistic that a deal can get done. Bonds and MBS are flat

Housing starts came in at an annualized 861k pace in November, somewhat below expectations.  This is undoubtedly a Sandy-influenced number.  Building Permits came in at 899k, above expectations. This is the strongest 3 months in four years. The NAHB Builder Confidence Index rose in Dec. Overall, the housing sector has turned the corner and is now an engine for growth, not a drag. 

Fannie Mae is out with their Economic and Housing Outlook for 2013.  Here is their forecast for 2013:

  • GDP +2.2%
  • Unemployment 7.5%
  • 10 year bond yield: 1.7%
  • Housing starts:  949k
  • House Price appreciation:  + 1.7%
  • 30 year fixed rate mortgage 3.4%
  • Purchase originations + 15%
  • Refinances: – 29%

I am surprised at their forecast for a drop in refis given that they think rates will stay low.  

Peter Eavis of the NY Times discusses the state of play with the qualified mortgage.  Consumer advocates are pushing for a broad definition of a qualified mortgage in order to increase credit availability, but they are are reluctant to give banks any legal protection. The big banks are saying that they won’t relax credit standards unless they are given some protection. Consumer advocates point out that that a shield will still presume the banks have met the standards, and merely allows the consumer to rebut that presumption, which means the lender has the upper hand to begin with.

Given the focus on the election and the fiscal cliff, fears of a European implosion seem to have fallen by the wayside.  The markets seem relatively sanguine about the prospect of a Euro debt crisis as sovereign yields have fallen since early Summer. Here is a chart of the Greek 10-year bond yield, post-re-org:

Actually, it isn’t just Greece – all of the PIIGS are rallying. All things considered this is a huge accomplishment.  Time should have named Mario Draghi Person of the Year instead of Barack Obama.