Posted on October 27, 2014 by Brent Nyitray
US stocks are lower as overseas weakness spills over. Stress tests for the European banks showed Italian banks with some weaknesses. Bonds and MBS are higher.
Pending Home Sales rose .3% in September, slightly below expectations. They are up 1% year-over-year. Pending Home sales rose in the Northeast and the South, while they fell in the West and Midwest.
We have the FOMC meeting this week, which will probably dominate trading in the bond markets. This one will not have any new economic projections, however. In spite of Bullard’s musings last week, the consensus is that QE ends at this meeting. I suspect all of the action will be in the minutes, which will be released at a later date, not the FOMC statement. Here is Goldman’s take on the meeting.
Interesting backstory to the big capitulation in the bond market last week. When yields crashed through 2%, dealers turned off their automated market-making systems and executed trades over the phone. They widened bid ask spreads and decreased the size of their markets. In other words, when the markets most needed liquidity, it evaporated, making the move more pronounced.
Someone is betting on Detroit – buying 6,000 foreclosures for $500 a pop. Would be interested to hear the business plan.
Filed under: Morning Report | 18 Comments »
Posted on October 24, 2014 by Brent Nyitray
Markets are flattish on no real news. Bonds and MBS are flat as well.
New Home sales rose .2% in September, to 467k while August sales were revised down in a big way, from 504k to 466k.
PulteGroup announced earnings last night which matched the Street. Revenues increased by 4%, driven by an 8% increase in prices and a 4% drop in deliveries. Pulte, which targets the first time homebuyer, applauded the new moves by FHFA to increase access to credit. However, not all builders are on board. Luxury builder Toll Brother founder Robert Toll characterized the proposed loosening of credit standards as “a really dumb-ass idea.” So there you have it.
That said, I think fears that loosening credit standards will fuel another real estate bubble are overblown. Bubbles are psychological phenomenons where people believe an asset can only go in one direction – up. People thought that way about stocks in the late 90s, and about real estate in the mid 00s. If there is going to be a next bubble, it will be in sovereign debt, not real estate. The baby boom has plowed into Treasuries after losing their shirts in stocks and real estate. And investors can play Treasuries through 2x and 3x levered ETFs. We won’t see another real estate bubble in our lifetimes, but our grandkids might.
Amazon.com reported lousy earnings yesterday, and gave a disappointing holiday forecast. Given that back-to-school was nothing all that great, this isn’t surprise.
Filed under: Morning Report | 9 Comments »
Posted on October 23, 2014 by Brent Nyitray
Markets are higher as earnings come in decent and we get some positive economic surprises this morning.
In economic data, the Chicago Fed National Activity Index rebounded strongly to +.47 from -.25. Initial Jobless Claims rose to 283k, which is still an incredibly strong number. September’s initial jobless claims were the lowest since 2000. The Bloomberg Consumer Comfort index rose to 37.7 from 36.2, but is still below 50, which is “normalcy” and shows why Democrats are looking at losing the Senate this fall in spite of stronger economic data. Finally, the index of leading economic indicators rose to +0.8% from flat in August. So overall, strong data, but the consumer remains unhappy.
The FHFA Home Price Index rose .5% in August and is up 4.8% year-over-year. The index is within 5.8% of its August 2007 peak. Remember the FHFA index only looks at homes with conforming mortgages, so it ignores the very high end and distressed sales which are usually cash. As a result, it is more of a central tendency index than either Case Shiller or CoreLogic. It has still been a case of two markets, however with the West Coast and Mountain states outperforming the East Coast and Midwest by a large margin:

Ocwen cannot get out of its own way. The stock is down 68% over the past year. NY AG Eric Schneiderman announced that he found evidence of backdating of letters sent to borrowers. Wall Street BFF Elizabeth Warren is piling on, prodding the GAO to look at nonbank servicers. Note that this could affect MSR valuations, which would pressure on nonbank lenders in general by reducing the fair value of MSRs on their balance sheets and also depressing SRP schedules.
Why have the regulators have changed their opinion on risk retention rule?. Because the full housing recovery has taken longer than expected. Tight credit is holding back the recovery, and they are correct. Unfortunately for Mel Watt, just saying “everybody back in the pool” won’t be enough. Banks are run by the business discouragement units (aka compliance) these days, and consider regulatory risk, not credit risk as the thing to be most mindful of. Note that the article speculates that FHA might be lowering the fees it charges (Mel Watt’s first act was to freeze Ed DeMarco’s planned FHA fee hike) in addition to lowering the downpayment on conforming loans. So, even if conforming loans go to 3%, FHA loans might still be competitive.
Filed under: Morning Report | 31 Comments »
Posted on October 22, 2014 by Brent Nyitray
Stocks are rising in the US as European markets rally. Bonds and MBS are down.
Mortgage applications increased 11.6% last week on the bond market rally. Purchases actually fell 4.8%, while refis rose 23.3%. The contract interest rate on the 30 year fixed dropped from 4.2% to 4.1%. Refis jumped to 65% of all applications.
The MBA is forecasting that mortgage volume will increase 7.4% in 2015. Given most people are thinking that home prices will increase by mid single digits, that is not a lot of unit growth.
Inflation at the consumer level remains muted, with prices rising ,1% month-over-month, and 1.7% on an annualized basis. Again, I simply do not see the Fed raising rates except for a symbolic amount to get off the zero bound until we start seeing 4%+ wage inflation. And that is not yet happening.
The final rules for QRM are out, and there weren’t a lot of surprises. It generally follows the QM framework, and conforming loans will be exempt from the retained risk feature. They also dumped the minimum down payment for language that requires “sound and responsible underwriting.” Not surprising since the government is now looking at 3% down conforming loans.
In case you missed it, here are the prepared remarks from Mel Watt, speaking at the MBA conference. Here are the prepared remarks by HUD secretary Julian Castro. The theme is to increase access to credit, largely by promising the lending industry more safe harbor. However not everybody is thrilled about this – see below.
Did you know the entire mortgage industry got together and decided that they will extort the government by overly restricting credit in order to make more money down the road when regulations ease up? I guess I must be a nobody since I wasn’t invited to the big pow-wow. Maybe Rob Chrisman was. Anyway, this is what passes for analysis nowadays in the left-wing fever swamp. The author thinks that Wall Street is unnecessarily restricting credit and blaming the government in a scheme to supposedly bring back the good old days. How he imagines hundreds of companies in the most fragmented, competitive business on the planet are going to come up with a scheme to voluntarily lose money on a bet that regulations might change in the future is beyond me. However, it is a window into how many in DC view us. What is common sense to practitioners is not necessarily apparent to many of the opinion makers who politicians listen to. While Mel Watt may not believe this nonsense, influential politicians like Elizabeth Warren probably do. Note Bene.
Filed under: Morning Report | 5 Comments »
Posted on October 21, 2014 by Brent Nyitray
Stocks are up this morning, following Euro markets as they speculate on added stimulus measures out of the ECB. Bonds and MBS are down.
Mel Watt addressed reps and warranties concerns at the MBA conference. He acknowledged uncertainty over putback risk is encouraging lenders to put overlays on Fan and Fred loans, which is excluding many borrowers who should be eligible for a conforming loan. In order to encourage lenders to lend through the entire spectrum of Fannie’s tolerances, rules regarding putback risk will be tightened up. Life of loan exclusions (in other words putback risk for the life of the loan) will be clarified. Watt didn’t go as far as to announce a new 97 LTV Fannie loan, but he did say FHFA was working withe GSEs to develop them.
Existing Home Sales bounced back in September to 5.17 million, the highest pace this year. Sales increased everywhere but the Midwest. The median house price was $209,700, up 5.6% for the year. Total housing inventory fell 1.3% to 2.3 million homes, which represents a 5.3 month supply. 6 months supply is considered a balanced market. All cash sales fell to 24% in September, down from 33% a year ago. 20% cash buyers is more or less the historical norm.
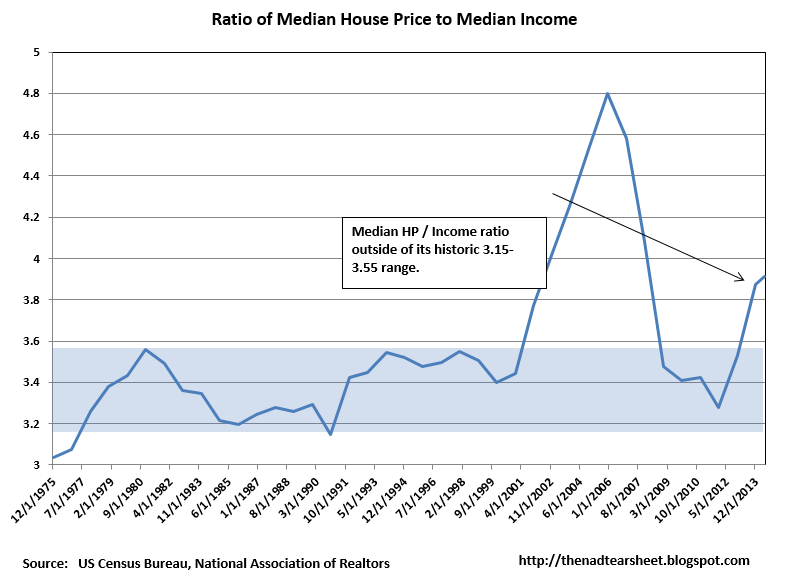
The median home price to median income ratio is now 209,700 / 53,589 = 3.9x. Historically, that number has been in a range of 3.2 – 3.6. So house prices could be vulnerable or stagnate until we start seeing wage inflation.

Mortgage REIT CYS Investments reported earnings last night. In spite of a small bond market rally, they still experienced mark-to-market hits on their portfolio of MBS as these securities cheapened on fears of a Fed rate hike. Since TBAs correlate with existing RMBS, this means TBAs underperformed as well. This is further evidence that mortgage rates simply did not correlate with Treasuries very strongly on the bond market rally this summer. So, if a borrower says “I saw on CNBC that interest rates were going down in a big way, how come your rates aren’t falling as well?” you can explain that mortgage rates have been lagging the bond market rally all summer, and the securities that set mortgage rates simply haven’t been performing as well as Treasuries. CYS did not attribute this to the end of QE however – in spite of the drop in Fed buying, the lack of volume as refis dried up has been the dominant effect, and there is strong demand for whatever RMBS issuance remains.
Filed under: Morning Report | 13 Comments »
Posted on October 20, 2014 by Brent Nyitray
Earnings will dominate the week. Tonight we will hear from mortgage REIT CYS investments. Later this week homebuilder PulteGroup will report, along with more regional banks. Apple will report after the close today.
The Mortgage Bankers Association Conference will be going on today and tomorrow. Secondary desks and dealers will probably be understaffed until Thursday.
Mel Watt is expected today to unveil new measures to increase access to credit in the mortgage market this week. The biggest one is a new Fannie Mae product for the first time homebuyer with a 3% down payment. Another is a program which gives the first time homebuyer a break on mortgage insurance if they go through a counseling program. FHFA is also expected to make some clarifications regarding buyback risk.
Why were US stocks rocked so violently last week on European weakness? Remember the old adage – during a crisis, you sell what you can, not what you want to. US stocks remain the most liquid risk asset. On a side note, almost $1 trillion worth of Treasuries traded on Wednesday last week, a record. That is looking more and more like the big capitulation trade and should be the top of the bond market for a while.
Left wing Jared Bernstein on how the Fed can reduce income inequality. Proving once again that the left learned absolutely nothing from the real estate bubble. It still thinks it can prevent asset bubbles by regulating Wall Street.
Filed under: Morning Report | 15 Comments »
Posted on October 17, 2014 by Brent Nyitray
Markets are higher as yesterday’s rally carries through. Bonds and MBS are down.
Housing Starts came in at 1.02 million, while building permits came in at 957k. Normalcy is 1.5 million, and that doesn’t even take into account population growth. We should be seeing starts coming at double what they are. Single family starts came in at 646k. Single fam has been relatively stable, while multi-fam has been extremely volatile.
Fed Head James Bullard made some dovish comments yesterday,which really turned around the market. The statement that got everyone’s attention was his suggestion that the Fed should consider maintaining QE for the time being. However, his point was not really all that dramatic – just that given the volatility in the markets, (coming primarily from Europe) and the fact that inflation expectations are falling with commodity prices, it might make sense to end QE at the December meeting, not the October one. He also stated that he believes we are a couple of jobs reports away from reaching historical norms in unemployment and the fundamentals of the economy are strong. He is not suggesting that we delay increasing interest rates, which is what people were hoping. Note that the Fed Funds futures moved pretty dramatically this week as they re-assessed their forecast for the first interest rate hike. The central tendency moved to late 2015 from mid 2015.
Wednesday’s pre-market bottom in the 10 year is feeling more and more like a capitulation. Look at the intra-day chart of the 10 year bond yield this week. It looked like a perfect storm of flight-to-safety, convexity buying, shorts throwing in the towel, and algo trading. The thing was trading like a tech stock. Again, I think of the roller coaster metaphor for the market – dizzying climbs, sickening drops, you end up in the same place where you started with less money in your pocket.

Filed under: Morning Report | 26 Comments »
Posted on October 16, 2014 by Brent Nyitray
Markets are still heavy this morning as Europe sells off. Bonds continue to rally, with the 10 year yielding 2.07%.
Is Ebola driving the correction in the stock market? FWIW, I don’t think so – I think it is European markets, which are collapsing. The Eurostoxx 50 index is down 13.5% over the past month. Note that Bullard is saying the same thing right now, and also suggesting that the Fed consider delaying the end of QE. Which begs the question – why? Rates are falling all on their own – does the Fed really need to keep purchasing bonds to drive the 10 year below 2%? Regardless, these dovish comments should be market positive, though how it affects the 10 year is an open question.
Was yesterday’s pre-market print of 1.95% on the 10-year the capitulation point? Could be, but watch credit spreads and the PIIGS. If spreads continue to widen, all bets are off.
Initial Jobless Claims fell to the lowest since 2000, with 264k people filing for first time unemployment. Continuing Claims rose 1,000.
Industrial Production rebounded in September after a dismal August, increasing by 1%. Capacity Utilization rose to 79.3%. Philly Fed fell to 20.7 from 22.5.
The NAHB Housing Market Index fell from 59 to 54. While builder sentiment dipped in October, they are still positive on the housing market. Given we are now in the seasonally slow period for the builders, I don’t know how much to read into this. Of course the big drop in rates could change that.
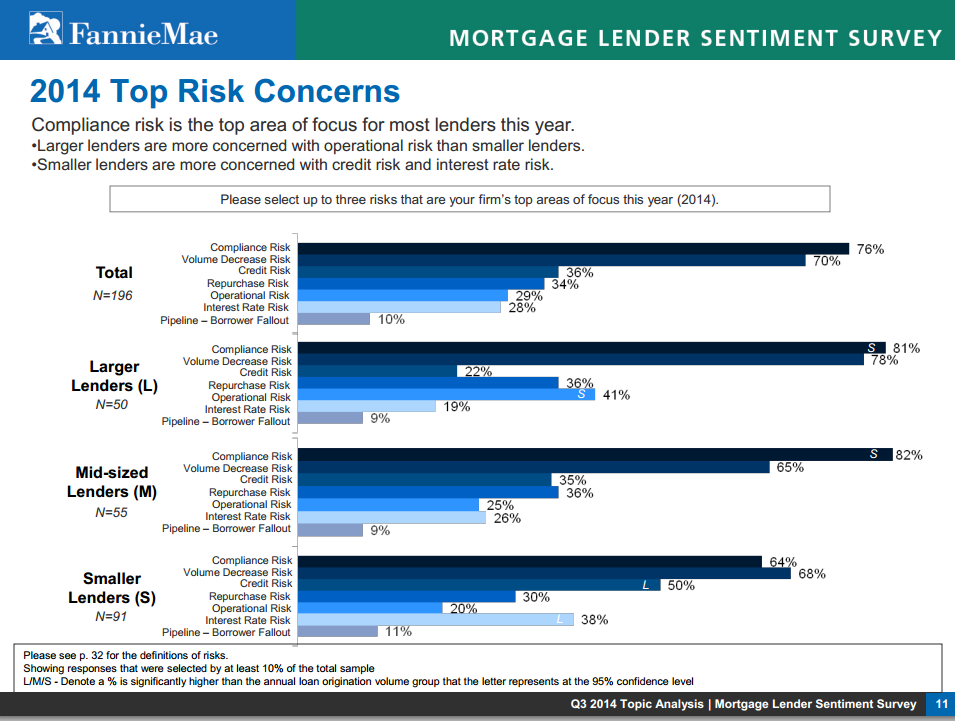
The latest Fannie Mae Lender Sentiment Survey discusses compliance costs and how much it costs. Most lenders (72%) reported that recent regulations have had a “significant” effect on their business. Mid-sized lenders reported a 50% increase in compliance spending. Note that most lenders are worried more about compliance risk than volume decrease risk.

Not housing related, but Lockheed Martin thinks we could have nuclear fusion within a decade. This is almost limitless power, without the radioactive waste that we get from nuclear fission, which is how we power our reactors today. It would also make a huge dent in CO2 emissions if it could be done on a large scale. This is a game changer on so many levels – strategic and economic.
Filed under: Morning Report | 6 Comments »
Posted on October 15, 2014 by Brent Nyitray
Markets are getting hammered this morning on global economic weakness. Bonds are flying.
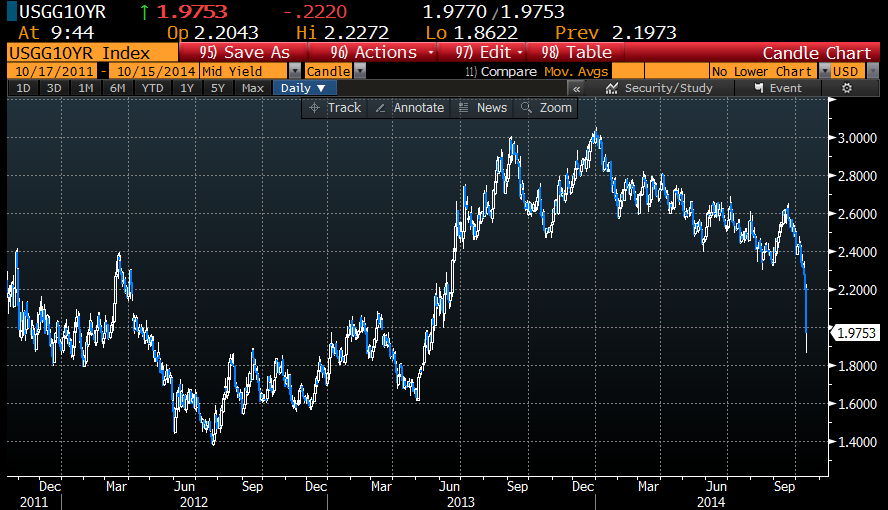
Bonds are on fire this morning. The 10 year is trading below 2% level, and European bond yields are posting new lows. The German Bund now yields 73 basis points. Oil is getting smacked and the stock market futures are down hard.
Look at the chart of the 10 year yield – it is simply collapsing:

LOs should be pinging borrowers about refinancing. This rally could be a huge gift. Look at possible VA IRRLs.
Retail Sales fell .3% in September on falling energy prices. Ex autos and gas, they still fell .1%
The Producer Price Index fell .1% in September. Ex food and energy, it was flat. No inflation anywhere.
Mortgage Applications rose 5.6% last week. Purchases fell .7% while refis rose 10.6%. The 30 year fixed rate mortgage fell to 4.2%.
Not to sound Cassandra-ish, but when bond yields are collapsing like this, it is often a signal that something is very wrong in the plumbing of the financial system. Bonds simply don’t behave like this on a weak inflation number or a downgrade of Germany’s economic growth by 50 basis points.
I’ll conclude with this observation: Bond yields are at these levels without much in the way of QE any more. We could have gotten these yields without the Fed buying 3.5 trillion worth of assets?
Filed under: Morning Report | 23 Comments »
Posted on October 14, 2014 by Brent Nyitray
Stocks are higher this morning as bank earnings come in generally good. Bonds are flying on European weakness, and the 10 year hit an intraday low of 2.175 as Germany cut their 2014 – 2015 growth forecast by a pretty sizeable amount.
We had earnings from some big banks this morning. Citi and Wells beat numbers, while JP Morgan missed. On the origination side, Wells reported an $48 billion in originations, an increase of a billion from the previous quarter. Gain on sale margins increased from 1.41% to 1.82%. JP Morgan announced the bank had gained market share in mortgages, however they cut 6,000 jobs in the space and will probably cut another 1,000. For JP Morgan, originations were 21.2 billion, down 48% from a year ago, but up 26% quarter-over-quarter.
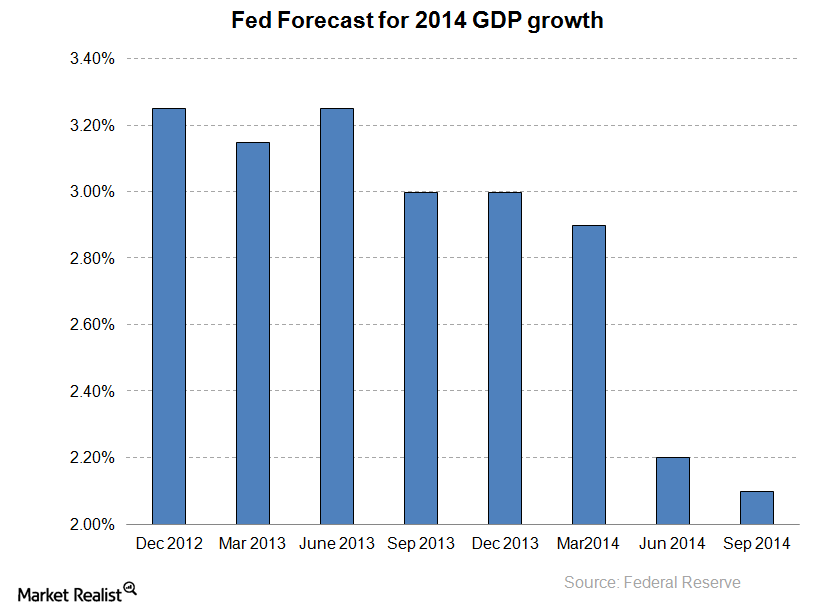
The NFIB Small Business Optimism Survey came in at 95.3, a drop from the prior month and below expectations. On the plus side, firms added .24 workers on average during the month. On the downside, only 22% of owners expect to make capital expenditures over the next 3 to 6 months. They note that the Fed has indicated it will raise rates in 2015, however the Fed’s forecasts for GDP have been over-optimistic. Take a look at the chart below. This is the Fed’s forecast for 2014 GDP growth starting at the December 2012 FOMC meeting and continuing through the September 2014 meeting. You can see how they have consistently cut their forecast.

Speaking of GDP growth, consumption is the biggest driver. It is looking like the holiday shopping season could be weak, with PriceWaterhouseCoopers predicting average holiday spending per household will fall to $684 this year from $735 in 2013. The National Retail Federation is more optimistic, predicting growth of 4.1%. Blame rising healthcare, childcare, and housing costs versus a backdrop of stagnant wages. Offsetting that of course is energy, with oil slipping below $85 a barrel. FWIW, the Back-To-School shopping season was meh, which is usually a good predictor of holiday sales.
Filed under: Morning Report | 11 Comments »


 Brent Nyitray
 Fairlington Blade
 Let the mutherfuker burn!
 jnc4p
 Kevin S. Willis
 Michigoose
 lmsinca
 markinaustin
 Arcanaut
 novahockey
 quarterback
 ScottC
 yellojkt