Morning report: complacency reigns 5/9/17

Vital Statistics:

Last Change
S&P Futures 2397.5 2.5
Eurostoxx Index 396.1 2.0
Oil (WTI) 46.4 -0.1
US dollar index 90.5  
10 Year Govt Bond Yield 2.39%
Current Coupon Fannie Mae TBA 102.6
Current Coupon Ginnie Mae TBA 103.81
30 Year Fixed Rate Mortgage 4.05

Markets are flattish on no real news. Bonds and MBS are flat as well.

Bond yields have been moving higher after the French election. Given that the result was not really a surprise there shouldn’t be too much in the way of follow through, but Euro bonds are selling off, which will translate into rising yields in the US on the relative value trade.

Job openings were flat in March at 5.74 million, which was slightly above estimates. The quits rate, which is a key indicator was up slightly YOY at 2.4% or about 3.1 million workers.

Small Business Optimism slipped in April, according to the NFIB Small Business Optimism Index. We are still at historically high readings, but the dimming prospect of tax reform in DC has hit the future expectations components of the index. The bright spot was hiring, as firms added .19 workers on average in April. 33% of respondents reported job openings they could not fill, which is the highest since 2000. Finding quality workers is a significant concern for many employers, although sales and regulatory issues are the biggest problems.

Radian’s Green River unit, which provides broker price opinions on residential real estate is the subject of a SEC probe. The feds are looking to see if BPOs were inflated on some bond deals where the interest was paid from the REO to rental trade. BPOs are cheaper than appraisals and are based on “drive by” evaluations. Many bond ratings agencies haircut BPO values in their assessments. If it turns out BPOs are inflated, it will probably have a dampening effect on bonds used to finance the activity. The plus side is that if private equity firms begin to unwind the trade, it will add some much needed supply to the market, especially at the lower price points.

Seriously delinquent loans and and foreclosure rates continue to fall, according to CoreLogic. The past due percentage dropped to 5%, the lowest level in 10 years. This is a decline from 5.5% a year ago. While rates have dropped nationally, they remain elevated in New York and New Jersey as well as some Mid-Atlantic states. We are seeing the biggest increases in the oil states.

Fannie and Freddie are looking at lending to borrowers with manufactured homes. FHFA needs to approve the program which is intended to increase credit to low-income borrowers, especially in rural areas.

The Fannie Mae Home Sentiment Index increased in April. Respondents are more constructive on real estate prices and the stability of their job situation, which was the catalyst to push the index up. The number of people who though now was a good time to buy increased by 5 percentage points. Respondents are also forecasting a 3% increase in home prices over the next 12 months.

5 things your appraiser wishes you knew. A big one is that the return on some home improvement projects are relatively low. A new kitchen will help, but you will be lucky to see a fraction of that expenditure translate into a higher home price. Pools are even worse. The biggest one? Finishing a basement. Most appraisers aren’t allowed to even count that square footage so that investment is valueless, at least as far as the appraisal is concerned.

Fear in the market is the lowest since 1993. The VIX index, which measures the price of options protection has been in the single digits lately. Does that portend anything? The old saw is “VIX is low, time to go. When VIX is high, time to buy.” VIX can stay low for extended periods, so the first part of that adage probably isn’t the greatest advice. Earnings growth has generally been good so far, which supports markets.

Want to really measure complacency in the market? Remember the PIIGS (Portugal, Italy, Ireland, Greece, and Spain) which were the ne’er do wells of the European sovereign market? You can now lend money to the Greek government for the princely rate of 5.5%. They peaked at 27% or so. That said, German Bund continues to experience higher yields, and you can now get 44 basis points for tying up your money with Angela Merkel for the next 10 years. Gotta pay her 66 for two though.

The mortgage interest deduction is being targeted by the left, who claim it increases inequality. This debate will get interesting as it creates an unusual alliance between limited government flat tax types, and social justice types. IMO, the mortgage interest deduction is simply too popular to eliminate but we could see a cap on it, which would probably hit homes at the high end the most.

Morning Report: Globalism wins in France 5/8/17

Vital Statistics:

Last Change
S&P Futures 2395.0 -2.8
Eurostoxx Index 393.7 -0.9
Oil (WTI) 46.2 0.0
US dollar index 89.9  
10 Year Govt Bond Yield 2.37%
Current Coupon Fannie Mae TBA 102.6
Current Coupon Ginnie Mae TBA 103.81
30 Year Fixed Rate Mortgage 4.05

Stocks are lower after Emmanuel Macron won the French election. Bonds and MBS are flat.

The election in France is perceived as a rejection of Trumpism (or whatever you want to call it). It was a return to the globalist left. Seems to be a little “buy the rumor, sell the fact” going on in the markets.

James Bullard is saying that the Fed Funds rate is close to where the Taylor Rule calculation would recommend they be set. The economy is in a low growth regime, but the labor force is in a high growth regime. As long as the labor market is still taking up slack, we won’t see much in the way of wage growth, which should keep the Fed from having to normalize too quickly. Depending on how you set some of the variables, the correct Fed Funds rate is anywhere from 67 basis points to 155 basis points.

The week after the jobs report is generally pretty data-light so we shouldn’t have that much in the way of market-moving data. The biggest chance of market-moving data is Friday when we get retail sales and the consumer price index. We do have Fed-speak every day except for Thursday.

Where are robots more likely to replace workers? It turns out that the upper Midwest is ground zero, however parts of the Northeast are as well. Out West, we see very little of it. This could partially explain why the real estate markets out West are red-hot, while markets in the Rust belt and the Northeast are tepid at best. Automation means jobs are being lost, which results in a declining population. For decades now, the general trend of population growth has been similar to what you would see if you picked up the United States by Maine, dangled it and shook it. Of course robots are a symptom of a bigger problem – some of these industries have high cost structures, and they will either automate or go out of business. Note that the West may not be immune – the next shoe to drop will be artificial intelligence and machine learning which will replace a lot of white collar workers as it develops.

robots

Compare this to the CoreLogic real estate heat map:

corelogic MSAs

Definitely seems to be a correlation between overvalued (red) and undervalued (green) real estate markets and the presence of automation. It makes sense. If people are leaving the green areas, you would expect to have a harder time selling a home (or easier time buying) than in places that are experiencing an increase in population.

Buffetapalooza or Capitalist Woodstock (the Berkshire Hathaway shareholders’ meeting) was over the weekend in Omaha, where you can sing with the Fruit of the Loom guys, eat at Warren’s favorite steak house, eat Sees candy, etc. He did have a few words about Wells’s scandal (BRK is WFC’s biggest shareholder).

Morning Report: Strong Jobs Report 5/5/17

Vital Statistics:

Last Change
S&P Futures 2389.0 3.5
Eurostoxx Index 391.7 -0.3
Oil (WTI) 45.1 -0.4
US dollar index 89.9
10 Year Govt Bond Yield 2.34%
Current Coupon Fannie Mae TBA 102.625
Current Coupon Ginnie Mae TBA 103.625
30 Year Fixed Rate Mortgage 4.02

Stocks are up after the strong jobs report. Bonds and MBS are up as well.

Jobs report data dump:

  • Nonfarm payrolls + 211,000
  • Unemployment rate 4.4%
  • Labor force participation rate 62.9%
  • Average hourly earnings up 0.3% MOM / 2.5% YOY

Overall a strong jobs report. The unemployment rate is the lowest in a decade, reaching close to the cyclical low right before the real estate bubble blew up. Despite the low numbers we have yet to see much in the way of wage growth. The employment-to-population ratio, which is the Fed’s preferred employment indicator, rose to 60.1%.  The U-6 unemployment indicator (which is more broad and includes the long-term unemployed) fell sharply during the month from 8.9% last month to 8.6%. U-6 is down 1.1% YOY. U-6 measures how much slack there is in the labor market, and as that slack is taken up wage inflation should return. This report shouldn’t really move the needle for the June FOMC meeting and the Fed.

Yesterday, the House passed narrowly its Obamacare replacement bill, and it will now head to the Senate where it will be ignored and slow-walked. The House bill was never scored by the CBO, and pushed through on short notice, which pretty much tips the GOP’s hand that this was never intended to actually become law and has a 0% chance of surviving intact. FWIW, the bill is really the Republican Primary Prevention Act of 2017, which is to say merely a political gambit. The Senate may also be waiting to see what insurance rates look like for 2018 and also how many drop out of the exchanges. The only way to get Democrats and moderate Republicans on board is if they see the Obamacare exchanges failing.

Now that Obamacare is out of the way in the House, their attention will turn to tax reform. Individual tax reform will get zero support from Democrats, however there might be some common ground on corporate taxes.

Fannie Mae reported income of $2.8 billion for the first quarter, all of which will go to the government sometime in June. Total equity has fallen from $6.1 billion at the end of last year to $3.4 billion at the end of Q1. This is the problem the government has to address with the current regime: sending all profit to Treasury is eroding Fannie’s capital. This is one motivation to get the government serious about GSE reform, although it isn’t a high priority in Washington at the moment.

Inflation continues to be tame, and part of that is being driven by oil, which has fallen 15% over the past few weeks. The rally in oil that began with OPEC’s plan to cut production has been completely given back. While the Fed will undoubtedly characterize oil as a transitory phenomenon it does flow through to other products and can help drive inflation.

Morning Report: Fed still constructive on the economy 5/4/17

Vital Statistics:

Last Change
S&P Futures 2389.5 6.3
Eurostoxx Index 391.1 1.7
Oil (WTI) 46.9 -0.9
US dollar index 90.1
10 Year Govt Bond Yield 2.34%
Current Coupon Fannie Mae TBA 102.84
Current Coupon Ginnie Mae TBA 103.92
30 Year Fixed Rate Mortgage 4.04

Stocks are higher as the GOP votes on the Obamacare replacement. Bonds and MBS are down.

The Fed made no changes to policy yesterday. Bonds sold off a few ticks on the announcement, which was constructive on the economy. Specifically, they noted that job gains remained solid, despite a slowdown in economic growth. Consumption remains an issue, but much of that is due to an increase in the savings rate post-crisis.

Job cuts decreased in April, according to outplacement firm Challenger, Gray and Christmas. Just over 36,000 job cuts were announced in April, which is down 15% from March and 43% from April last year. Retailers announced the most cuts, with autos and healthcare coming in second and third.

Initial Jobless Claims fell to 238k last week, which is still at the lowest levels since the early 1970s.

Productivity fell 0.6% in the first quarter while unit labor costs rose 3%. This reading certainly makes sense in light of the weak Q1 GDP print. The conundrum of the past decade has been the drop in productivity growth, which drives wage growth and increases in standards of living. While there is a definite measurement issue (for example the plethora of free information available on the internet would certainly seem to boost productivity, however because it is free, it doesn’t show up in the calculations). Last year’s productivity growth was 1.4%, which was well below the historical average of 2.2%. Theoretically, low productivity would lower the growth ceiling on the economy which would make inflation emerge quicker and force the Fed to act more aggressively, however inflation is nowhere to be found and while there are labor shortages we aren’t seeing any real wage inflation yet.

Donald Trump has mentioned breaking up the big banks and a return to some sort of Glass-Steagall regime. That said, it doesn’t appear to be a priority, and the administration barely discusses it. Any discussion of breaking up the big banks would probably be limited to Bank of America, JP Morgan, and Citi. Any sort of break-up of these 3 would probably have limited impact on the mortgage market, as non-banks now dominate the space and Wells Fargo really doesn’t have the investment banking footprint the big 3 have.

The continuing resolution was passed by the House which should take the risk of a government shut down off the table until later next year.

Morning Report: Fed day 5/3/17

Vital Statistics:

Last Change
S&P Futures 2382.3 -3.5
Eurostoxx Index 389.0 -0.4
Oil (WTI) 47.8 0.2
US dollar index 89.8  
10 Year Govt Bond Yield 2.29%
Current Coupon Fannie Mae TBA 102.84
Current Coupon Ginnie Mae TBA 103.92
30 Year Fixed Rate Mortgage 4.04

Markets are quiet ahead of the Fed decision this afternoon. Bonds and MBS are flat.

Back from the MBA Secondary Conference. Q1 was dismal for pretty much everyone, but people are thinking interest rates are heading lower not higher.

The FOMC decision will be out at 2:00 pm EST. Nobody expects the Fed to make any policy changes, but the wording in the statement could move markets. Just be prepared for some volatility around that time and be careful with locks.

The ADP jobs report came in at 177k, a little bit better than the 170k forecast. The Street is looking for 185k jobs in this Friday’s employment situation report.

Mortgage Applications fell 0.1% last week as purchases rose 4% and refis fell 5%.

Personal incomes rose 0.2% last month and consumer spending was flat. The core PCE index (the inflation measure preferred by the Fed) came in at 1.8%, below the Fed’s 2% target rate.

The ISM manufacturing Index slipped to 54.8 from 56, while the ISM non-manufacturing index improved to 57.5 from 55.8.

Home prices rose 1.6% MOM and are up 7.1% YOY according to the CoreLogic Home Price Index. The index is within 2.8% of its April 2006 peak. The FHFA House Price Index has already recouped its losses from the bubble years. They forecast a 5% increase this year and see the index recouping the bubble losses in late summer. Here is a map of the overvalued (red) and the undervalued (green) MSAs.

Given that the house price indices are approaching or have already surpassed their past peaks, you would figure that most houses in the US would be at those levels as well. Unfortunately, they are not. In fact, Trulia estimates that only 1/3 of houses have recouped the losses from the bubble. There is a huge dispersion as well – only 3% of homes in Fresno or Las Vegas or the NYC suburbs have surpassed their prior peak levels, while 94% of homes in Denver or San Francisco have. The problem with these home price indices is that they use a repeat sales methodology, which tends to over-emphasize hot markets. Real estate prices in states exposed to the tech sector and the energy sector are performing the best. Surprisingly, flyover America is doing better than Coastal America. On the link, you can do a county-by-county analysis to see where you stack up.

Housing continues to punch below its weight in terms of contribution to GDP. Residential construction has historically been around 2% of GDP, and based on the first quarter estimate it was closer to 1.3%. We have incredibly tight demand for homes, so why aren’t we seeing building? It depends on who you ask. If you ask a builder in a hot market, the problem is lack of skilled labor. In other areas, regulation and credit are the culprits. The housing market continues to be a conundrum for policy makers and analysts.

Morning Report: Q1 GDP weakest in 3 years 4/28/17

Vital Statistics:

Last Change
S&P Futures 2387.0 1.0
Eurostoxx Index 386.8 -1.0
Oil (WTI) 49.5 0.6
US dollar index 89.7
10 Year Govt Bond Yield 2.32%
Current Coupon Fannie Mae TBA 102.63
Current Coupon Ginnie Mae TBA 103.68
30 Year Fixed Rate Mortgage 3.98

Stocks are flattish after first quarter GDP misses expectations. Bonds and MBS are down.

First quarter GDP came in at 0.7%, which was lower than the 1.1% consensus forecast. A decline in spending on motor vehicles was a drag on Q1, which has been weak the past several years for some reason. The personal consumption expenditure (the inflation measure most preferred by the Fed rose 2.4%, which is higher than their target rate. This was the highest reading in several years, which means the Fed might be forced to move even though growth is weak. The savings rate jumped from 5.5% to 5.7%, which means consumers are still using increases in income to pay down debt. Inventory depletion and a drop in government spending, along with weak consumption were the main drivers. Note that this is just the advance estimate, and will be revised twice in the next month.

Employment costs rose 2.8% annualized in the first quarter, according the BLS. Wages and salaries rose 2.5% while benefit costs increased 2.2%. We have been seeing a gradual tick up in this index, however wages are still well off their pre-crisis historical trend.

Trump’s tax plan was short on specifics, but it certainly looks like wealthier residents in high tax states will feel it the most. Killing the state and local tax deduction has been fraught with risk, but given that it will largely affect the blue states it might have a chance. Eliminating the mortgage interest deduction will be a poison pill, IMO. Will tax reform hit the residential real estate market? Probably not, as tight inventories are the dominant factor driving pricing right now.

The homeownership rate ticked down slightly in the first quarter to 63.6% from 63.7% in the fourth quarter. It looks like it is on the rebound, however the first time homebuyer really needs incomes to rise in order to catch an asset that is increasing 7% a year. More starter home construction would help too, but multi-fam seems to be the interest of builders. Vacancy rates are largely flat MOM and YOY.

The Chicago Purchasing Manager Index rose last month, while consumer sentiment slipped.

Housing Wire’s home price forecast for the rest of the year. Overall, looking at 3.5% growth, with a range of anywhere from 1% to 10%.

Morning Report: Pending Home Sales fall 4/27/17

Vital Statistics:

Last Change
S&P Futures 2385.0 2.8
Eurostoxx Index 387.6 -1.2
Oil (WTI) 48.7 -0.9
US dollar index 89.7  
10 Year Govt Bond Yield 2.31%
Current Coupon Fannie Mae TBA 102.63
Current Coupon Ginnie Mae TBA 103.68
30 Year Fixed Rate Mortgage 3.98

Stocks are mixed this morning as markets digest the ECB non-move. Bonds and MBS are down small.

Pending Home Sales fell 0.8% in March as tight inventory reduced transactions. On a YOY basis, they are up 0.8%, as February was an unusually strong number. NAR chief economist, says sparse inventory levels caused a pullback in pending sales in March, but activity was still strong enough to be the third best in the past year. “Home shoppers are coming out in droves this spring and competing with each other for the meager amount of listings in the affordable price range,” he said. “In most areas, the lower the price of a home for sale, the more competition there is for it. That’s the reason why first-time buyers have yet to make up a larger share of the market this year, despite there being more sales overall.”

Durable Goods orders rose 0.7% in March, lower than the 1.1% estimate. Ex transportation and defense, they rose 0.1%. Capital Goods orders, which is a good proxy for business capital investment, rose 1.2%. Yet another data point where the hard data isn’t confirming the buoyant soft data.

Initial Jobless Claims rose slightly to 257k last week, while retail inventories rose 0.4% and wholesale inventories fell 0.1%. The consumer comfort index edged up as well.

Regular readers of this blog know I have been discussing the post-Trump interest rate sell-off for months. I lay out the full case in the latest issue of the Scotsman Guide: Finding Comfort in History. I discuss why the Fed might not move 3 times this year (because they have invariably been high in their GDP estimates), why a 75 basis point move in the Fed Funds rate won’t necessarily translate into a 75 basis point hike in mortgage rates (because the yield curve usually flattens), and why the end of QE reinvestment won’t have a dramatic effect on mortgage rates.

Trump’s tax plan which was unveiled yesterday was really more of a guidance to Congress than an actual plan. FWIW, legislation originates in Congress, not the White House, so it is unrealistic to expect a detailed, CBO-scoreable plan. That said, we know that the basis plan will be to reduce the number of tax brackets, lower the rates, increase the standard deduction, and to limit itemized deductions. What does that mean for real estate? Nobody knows for sure, but the National Association of Realtors is weighing in already, urging the government to maintain the mortgage interest deduction and the state / local tax deductions. Trump’s plan will probably ding upper middle class homeowners in high tax states the hardest.

Morning Report: Is the Trump Reflation Trade dead? 4/26/17

Vital Statistics:

Last Change
S&P Futures 2384.0 -1.0
Eurostoxx Index 387.2 0.2
Oil (WTI) 49.2 -0.4
US dollar index 89.8 0.3
10 Year Govt Bond Yield 2.31%
Current Coupon Fannie Mae TBA 102.625
Current Coupon Ginnie Mae TBA 103.68
30 Year Fixed Rate Mortgage 3.98

Stocks are flat as markets await Donald Trump’s tax plan. Bonds and MBS are down small.

Trump is expected to unveil his plan for a 15% corporate tax rate today. This rate is a negotiation posture and it will almost certainly increase to 20% or higher. Trump is not only negotiating with Democrats, he is also negotiating with Paul Ryan, who wants to implement a border adjustment tax which will offset the revenue lost from the tax cut. If the tax cut is not revenue-neutral, it will need 60 votes in the Senate, which will doom it. The other option, which would be a temporary reduction in the rate, would probably not influence corporate decision making, especially if it was only for a few years.

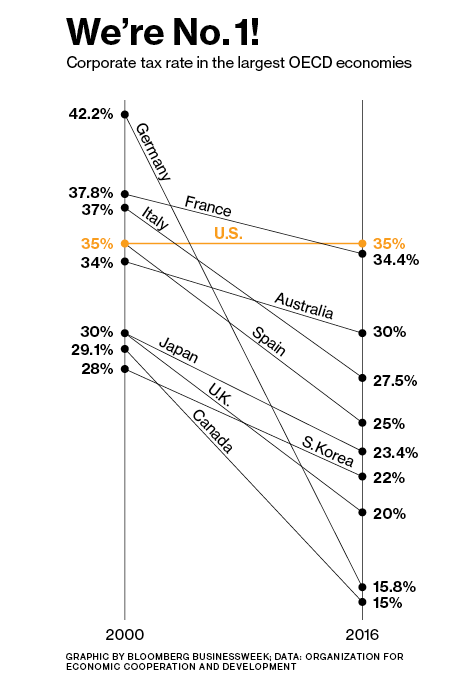
Note that our current tax rate of 35% is the highest in the world, and our competitors are in the mid 20s. Germany has been the biggest tax cutter, taking its rate from 42% to 16% over the past 16 years. Does the Laffer Curve apply to corporate taxes? The Laffer Curve (pictured below) basically showed that tax receipts don’t increase monotonically as the rate increases – it is a curve. When taxes are 0% or 100% the government will raise nothing. In between those numbers there is an optimal point. The debate in Washington has been over which side of that point we are on. The curve for corporations is influenced not only by tax policy influencing corporate incentives, it is also influenced by competition from other jurisdictions. The reason why Corporate America has trillions stashed overseas is testament to this. Outsized corporate taxes compared to our competitors incentivizes corporations to maximize overseas income and minimize domestic income. This amounts to a subsidy to foreign governments. While the CBO (who will score the proposal) poo-poos the idea of dynamic scoring, in this case it is probably appropriate, even if you discount the effect on economic growth, simply because it removes this perverse incentive.

Will the potential tax cut breathe new life into the Trump reflation trade? A revenue-neutral tax reform will probably not be massively stimulative (it can’t be, by definition) however removing these perverse incentives will certainly help. If Trump can get some foreign tax repatriation deal, that will help. The left will probably balk if there are no strings attached to it, as they fear it will only go to dividends and buybacks. However, there could be a way to convince them to go along, if some of the savings are applied to things like increasing payroll, increasing training, etc. Infrastructure spending is also going to be a hard sell, both to Democrats, who despise the privatization of infrastructure, and the Freedom Caucus, who despises government spending in general.

Punch line: The Trump reflation trade is probably going to be based on revenue-neutral tax reform and some sort of stripped-down infrastructure spending plan (if one even materializes). The single best effect will be regulatory reform, however none of this should really push inflation higher, which is what the Trump reflation trade was all about in the first place.

Mortgage Applications increased 2.7% last week as purchases fell 1% and refis rose 7%. The average 30 year rate fell 6 basis points. Note last week was a holiday-shortened week, which probably affected the purchase number.

Republicans have floated a bill that funds the government through the rest of the fiscal year without funding the wall. Funding for the wall has been a sticking point and Democrats have vowed to shut down the government over it.

Fannie Mae is rolling out new products designed to help borrowers with student loan debt. This includes cash-out refis that allow a borrower to consolidate student loan debt into a mortgage, Other measures will allow borrowers to exclude debt paid by others, and another will allow lenders to accept student loan information on credit reports. Given the high home price appreciation we have been seeing, the first time homebuyer needs all the help it can get.

Morning Report: Strong new home sales 4/25/17

Vital Statistics:

Last Change
S&P Futures 2375.3 5.3
Eurostoxx Index 387.5 1.4
Oil (WTI) 49.2 0.0
US dollar index 89.5 0.1
10 Year Govt Bond Yield 2.31%
Current Coupon Fannie Mae TBA 102.625
Current Coupon Ginnie Mae TBA 103.68
30 Year Fixed Rate Mortgage 3.98

Stocks are higher this morning as it looks like cooler heads are prevailing in the continuing resolution negotiations. Bonds and MBS are down small.

New home sales increased to an annualized rate of 621k, well above the Street expectations of 587k. New Home Sales is a notoriously volatile number, but it looks like the Spring Selling Season is off to a good start.

Pulte announced earnings this morning, with a 14% increase in revenues and a 17% increase in earnings. CEO Ryan Marshall had this to say about the spring selling season: “Buyer interest during the spring selling season of 2017 has been high and points to the ongoing strength in recovery for the housing industry. Strong buyer demand continues to be supported by an improving economy and resulting employment and wage gains, high consumer confidence, a low inventory of new and existing homes, and the powerful demographic forces of Millennials and Baby Boomers. Given the strength of our land pipeline and our disciplined investment practices, PulteGroup is well positioned to grow its market presence and improve its financial performance within this operating environment.” Note that gross margins fell by 230 basis points, which shows costs are outpacing price growth.

In other economic data, consumer confidence slipped in April, but is still strong, while the State Street Investor Confidence Index unexpectedly rose. The Richmond Fed Manufacturing Index improved as well.

Home price appreciation accelerated in February, according to the FHFA House Price Index. Prices were up 0.8% MOM and are up 6.4% annually. Prices have risen 6.2% annually since bottoming in early 2012. Regionally, the Mountain states had the biggest increase, coming in at 9.5%. Even New England, historically a laggard, increased by 6.5%. The worst area – Mid atlantic – rose 4.6%.

Meanwhile, the Case-Shiller Home Price Index rose 0.7% MOM and is up 5.9% YOY.

In politics, Donald Trump seemed to moderate his comments about marrying the wall with funding the government through the end of the fiscal year. Given that Republicans hold all 3 branches of government, why does Trump need Democrats? The reason is the same thing that vexed Obama: The House Freedom Caucus, who won’t support anything that doesn’t repeal Obamacare or cut spending enough. This gives Chuck Schumer and the Democrats more leverage than they would ordinarily have. Note Congress can play some accounting games to move the deadline back a couple of weeks, so this Friday isn’t necessarily a drop-dead date. A government shutdown is probably unlikely, but LOs should be thinking about ordering 4506-Ts if they need them.

Donald Trump is targeting a corporate tax rate of 15%, which will be unveiled tomorrow. House Speaker Paul Ryan is closer to 20%, and believes that 15% is too low to be revenue-neutral. While even Democrats recognize our corporate taxes are too high, they won’t get onboard anything that amounts to a tax cut. Take a look at the chart below. It has our taxes (and our competitors’) tax rates from 2000 to 2016. Pretty much everyone has cut taxes except for us. Trump will also reveal a plan for individual income taxes as well.

US taxes

Having trouble saving? There’s an ap for that. New fintech companies are micro-analyzing an individual’s earnings and spending patters, and using credit and savings sweeping to normalize their client’s income (think a freelancer or an Uber driver). Some will pay all your bills for you, and others will ensure your checking account doesn’t overdraft. Some will extend credit at high rates, however those rates are generally better than payday lenders.

Another blow for cheap new housing construction. The US is imposing tariffs on Canadian softwood exports in an ongoing trade dispute. Softwood (basically pine) is primarily used for framing in housing, so we could see lumber prices increase further. While “sticks and bricks” are not the main driver of housing construction cost, this doesn’t help matters. It is getting to be a problem when the typical starter home is unaffordable to its target market.

The MBA has rolled out its plan for the GSEs. The idea would be to turn Fannie and Freddie into public utilities and to take steps to open up the market for private mortgage guarantors. They estimate it could take up to 10 years to implement. Note the clock is ticking: As the government continues to sweep all of Fannie’s profits to Treasury, their net worth is decreasing.

Morning Report: Markets rally on the French election 4/24/17

Vital Statistics:

Last Change
S&P Futures 2374.8 27.3
Eurostoxx Index 386.0 7.9
Oil (WTI) 49.9 0.3
US dollar index 89.5
10 Year Govt Bond Yield 2.29%
Current Coupon Fannie Mae TBA 102.78
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 3.98

Stocks are higher this morning after the French election had no surprises. Bonds and MBS are down on the risk-on trade.

We will have a lot of real estate related economic releases this week, however we don’t have much in the way of market moving data until Friday when we get the first look at Q1 GDP. We have Fed-Speak today and Friday.

The French election will pit a centrist against a right wing candidate. The far left candidate did not make it to the next round. Given this is just a first round election, the market’s sugar high probably won’t last all that long.

After the French election, the next big event is the the potential government shutdown on Friday. The sticking point is that Trump wants funding for the border wall, which Democrats are calling a non-starter. If Trump and the Democrats can’t get a deal (or Trump can’t get Republicans to help him out), we will get a partial government shutdown starting Saturday. This will be the big event this week, although markets are probably used to this sort of drama.

It is humorous to pick up the way the potential shutdown is spun in the media. When obama had to deal with shutdowns, it was the irresponsible Republicans who controlled Congress who were the villains. Now that Democrats won’t vote for a CR, the villain is now Trump. Plus ca change…

Note that the last time we had a shutdown, people weren’t able to get 4506-T’s out of the IRS during the shutdown. LO’s should plan accordingly to keep closings on track.

Economic activity took a step back in March, according to the Chicago Fed National Activity Index. Employment related indicators drove the decrease. Not sure how much of that is coming from retailers, who have been struggling as of late. This is a meta-index of leading and lagging indicators, however it certainly shows that the hard data (actual spending / employment / production numbers) is not catching up to the soft data (sentiment surveys).

Tight inventory has home prices on a tear, with the Black Knight Home Price Index up 0.8% MOM and 5.7% YOY. The index has now passed its bubble peak and is making new highs. The FHFA index and the CoreLogic indices have hit new highs as well, leaving only the Case-Shiller index still underwater. Mortgage originators are issuing tons of pre-qual letters, but the offers are not forthcoming since the market is so competitive. Buyers are now making offers without contingencies in order to get the home they want. The hottest market? Seattle, where prices rose 2.7% on a month-over-month basis. This is hard for the first time homebuyer who often needs some help paying closing costs. VA loans allow for seller’s concessions (which don’t cost the seller any money), which means you can get up to a 103% LTV loan.

Chris Whalen has a good piece on what the origination business will look like for 2017. Punch line: lower volumes, increasing purchase activity, and a widening of the credit box. He also speculates that CFPB Chairman Richard Cordroy’s response to Trump staffer Gary Cohn’s request to resign was to launch a new assault on Ocwen. There are rumors that JP Morgan might get back into the FHA lending business, and Wells has cut pricing on FHA loans as well. In terms of home price appreciation, housing affordability is stretched, but low inventories will proved price support.

Homebuilder DR Horton reported strong Q2 earnings as revenues and income rose 17%. New orders were up 14% in units and 17% in value. They took up guidance as well.