Morning Report: Government still shut down 1/22/18

Vital Statistics:

Last Change
S&P Futures 2811.5 0.5
Eurostoxx Index 401.9 1.0
Oil (WTI) 63.3 -0.1
US dollar index 84.4 -0.1
10 Year Govt Bond Yield 2.65%
Current Coupon Fannie Mae TBA 103.591
Current Coupon Ginnie Mae TBA 103.688
30 Year Fixed Rate Mortgage 4.03

Stocks are flat as the government shutdown goes into a third day. Bonds and MBS are flat.

For all of the sturm and drang about the government shutdown, the markets don’t care. Hopefully people who needed tax transcripts took care of business early.

Bond yields blew through support last Friday, and the Ginnie Mae TBAs are in a bit of a transition. The higher coupon TBAs hadn’t really begun trading with any sort of volume, which made it hard to get note rates above 5 1/8%. Since bonds are pretty much unchanged this morning we should see those note rates open up (hopefully) today.

Note some bond bears see the early part of the year as the time to sell bonds. This is similar to the “sell in May and go away” advice that stock investors sometimes heed. It turns out that since 1998, bond yields have increased ever so slightly in the first 5 months of the year, and have fallen pretty dramatically in the final 7 months. Is there any sort of economic explanation? No. Which means it is just a coincidence.

The upcoming week won’t have much in the way of market-moving data except for Friday, which will have durable goods and GDP. Fed-speak is also minimal ahead of the FOMC meeting next week. The markets are predicting nothing is going to happen at the Jan meeting. We will get some non-market moving housing data with new home sales, existing home sales, and the FHFA House Price Index. We are in the heart of earnings season, and that will dictate stock price movement.

The World Economic Forum begins this week in Davos, which means we will get to see a lot of economists get interviewed in the snow on CNBC and Bloomberg TV. Don’t expect to hear anything market-moving. The global economy is doing just fine at the moment, although I am sure bigwigs at the IMF, World Bank, and various Central Banks will find something to fret about. They should probably worry more about their economic forecasts. The Bank of England was dead-set against Brexit, and thought that leaving the EU would crash the economy. Their forecasts missed the mark by a country mile. As a general rule, investors should leave their political preferences at the door when it comes to making investment decisions.  Combining political ideology with economic / market forecasting is inevitably a recipe for disaster.

Economic activity continued to exhibit strength in December, according to the Chicago Fed National Activity Index. Production-related indicators (sales, orders, inventory) improved in December, while employment indicators were more or less flat compared to November.

The post-crisis financial regulatory environment has created a shortage of appraisers. While this has largely affected mortgage lending, banks are now using Broker Price Opinions (BPOs) for transactions that involve rental properties. These used to be called “drive-by” appraisals, as the analyst would drive past the property and look at it without entering. Nowadays, these appraisals are outsourced to India, where analysts basically come up with a valuation using Google Earth and comps. Even Fannie Mae used BPOs for a transaction last year. The ratings agencies will haircut the BPO valuation by 10% or so when doing a collateral evaluation.

One of the telltale signs at the peak of a market bubble, according to Charles Kindleberger in his book Manias, Panics, and Crashes is the emergence of swindles. The largest private bank in China has turned out to be a fraud. China has a massive real estate bubble on its hands, and it will burst at some point (this year, next decade, who knows?) However, once it bursts, the economic playbook says that China will export deflation the way Japan did in the 90s, which means lower interest rates and lower inflation overall.

Speaking of bubbles, the liberal Brookings Institute thinks that 40% of student loans from the 2004 cohort could default. This isn’t chump change, either: a total of $1.4 trillion in student loan debt is outstanding. This is another reason why the Fed is so interested in creating inflation (despite what they say about it). Inflation is a debtor’s best friend, as wages rise with inflation, but fixed rate debt stays the same, which reduces the drag on spending and economic growth over time. Until that happens, the first time homebuyer will probably continue to rent, at least at the margin.

Home prices increased 7% in 2017, according to Redfin. As usual, inventory remains the biggest problem in the real estate market.

Morning Report: Shutdown day 1/19/18

Vital Statistics:

Last Change
S&P Futures 2799.3 3.0
Eurostoxx Index 400.2 1.4
Oil (WTI) 63.0 -0.9
US dollar index 84.4 0.0
10 Year Govt Bond Yield 2.62%
Current Coupon Fannie Mae TBA 102.375
Current Coupon Ginnie Mae TBA 103.25
30 Year Fixed Rate Mortgage 4.03

Stocks are higher this morning as we head into the deadline to keep the government open. Bonds and MBS are flattish.

Consumer sentiment slipped in early January, according to the University of Michigan Consumer Sentiment survey. The reading fell to 94.4 from 97 in December.

The House passed a 1 month continuing resolution yesterday and all eyes turn to the Senate, where Democrats are demanding action on immigration in exchange for a vote to keep the lights on. If they can’t come to a deal, the government will shut down at midnight. This will be a little different than it was during the Obama years: Obama wanted the public to feel the pain of the government shutting down, so he made it as visible as possible. Trump is going to do the exact opposite. National Parks will still be open, although the rangers will be off duty. Tax transcripts were held up the last time the government shut down, so hopefully everyone planned accordingly.

So far, the markets are treating the drama in DC as a sideshow. The US dollar, bond yields, and stock prices don’t care. The 10 year is trading right at technical support right now, so if it breaks through that level, technical analysts are thinking the next level is 3%.

Are credit scores preventing people from getting mortgages? Some are arguing that the old FICO scores are outdated and the GSEs should open up credit scores for competition. There is always the fear that competing credit scores will create a race to the bottom, where the most lax score wins, but that is probably overblown. Most originators won’t touch the lowest permissible scores to begin with, so changing the number will probably only result in them changing their overlays to maintain the same credit profile as before.

They say all real estate is local, and from what we have seen prices are rising rapidly. Are there pockets of weakness still? In fact there are, in the super-rich bedroom community of Greenwich, CT. Last quarter, prices fell at high end by almost 14%, the most since 2008 when Lehman Brothers collapsed. Sellers are tired of waiting years to get the price they want, and are finally getting realistic about the new market conditions. One estate, which was originally listed at $65 million ended up going for $21 million. The bottom line for Greenwich is that the financial industry, which really supported the area, has changed and probably isn’t coming back to pre-bubble levels. This also explains Connecticut’s budget issues as well – the rich communities in Fairfield County largely supported the state.

Labor shortages are starting to push up wages, especially for skilled workers. Yesterday’s initial jobless claims number was the lowest in 45 years. The markets and the Fed are forecasting 3 rate hikes this year. The risk is probably that this estimate is too low. The markets have been bumping up their March forecast. which currently stands at a 73% chance of a 25 basis point rate hike, up from 61% a month ago.

The CFPB made its budget request for the first quarter, and the number is…. $0.00. The agency has $177 million in the bank (so to speak) and has a budget of $145 million, so they aren’t asking for any more money.

The Senate is working on a housing reform plan that would wind down Fannie and Fred and replace them with up a large number of private guarantors with a catastrophic government backstop. The Senate differs from FHFA here – FHFA wants a small number of guarantors to operate under a regulated utility model to prevent a race to the bottom, while the Senate envisions no limit. One other big change – the elimination of affordable housing goals, which will be replaced with incentives. This will almost certainly anger liberals, who were able to kill housing reform in 2014 over that exact issue.

Want to be master of the universe? Try the Monetary Policy Game.

Morning Report: Housing starts disappoint 1/18/18

Vital Statistics:

Last Change
S&P Futures 2802.5 -1.3
Eurostoxx Index 398.1 0.1
Oil (WTI) 64.0 0.1
US dollar index 84.5 -0.2
10 Year Govt Bond Yield 2.62%
Current Coupon Fannie Mae TBA 102.375
Current Coupon Ginnie Mae TBA 103.25
30 Year Fixed Rate Mortgage 4.03

Stocks are lower this morning on no real news. Bonds and MBS are down.

The House looks ready to pass a one-month stopgap measure to keep the lights on. Senate Democrats are considering blocking it in order to push immigration reform, but nothing is set in stone. Bottom line, the odds of a government shutdown tomorrow are falling.

Initial Jobless Claims came in at 220,000 last week. This is a 45 year low. When you take into account population growth and the fact that we had a military draft back then that number is astounding.

The Beige Book was released yesterday, and contained no major surprises. Growth is “modest to moderate” in most districts and the labor market is tight, to the point of constraining growth. They mentioned that we are seeing wage inflation more broadly in some districts, while inflation is generally under control. Separately, the Philly Fed report showed that growth eased somewhat, however it is still very strong.

Housing starts came in at 1.19 million units (annualized), which was a big disappointment. Hurricane effects probably played a part, as many construction workers are being diverted to repair work. We did see a substantial (14%) drop in starts in the South. Building Permits came in at 1.3 million. All told, 1.2 million housing units were started in 2017, which was more or less flat with 2016. This is about 80% of the pre-bubble average of 1.5 million units a year.

Mel Watt discussed housing reform in a letter to the Senate Banking Committee. He urged lawmakers to establish a guarantor framework where shareholder-owned entities guarantee mortgages with a government backstop and a utility model. The utility model means that pricing will be set by the government in order to set an allowable rate of return for the company and nothing more, similar to how gas and electric companies are run. If one of the guarantors runs into trouble, they will be allowed to fail, however the mortgages they guarantee will be backstopped by the government, thus protecting MBS investors. The document also recommended that these guarantors offset their credit risk in the private market when economically feasible and that they hold enough capital to withstand another 2007.

Morning Report: Possible deal on funding the government 1/17/18

Vital Statistics:

Last Change
S&P Futures 2791.8 9.5
Eurostoxx Index 398.3 0.0
Oil (WTI) 63.6 -0.2
US dollar index 84.6 0.0
10 Year Govt Bond Yield 2.55%
Current Coupon Fannie Mae TBA 102.375
Current Coupon Ginnie Mae TBA 103.25
30 Year Fixed Rate Mortgage 4.03

Stocks are higher this morning on no real news. Bonds and MBS are up small.

Slow news day.

Builder sentiment fell somewhat last month, but is still strong, according to the NAHB.

Mortgage Applications increased 4% last week as purchases rose 3% and refis rose 4%. This is a bit of a surprise given that bond yields moved up aggressively on stronger economic data and speculation that China would reduce its Treasury purchases. The 30 year fixed rate mortgage rose 10 basis points to 4.33%.

The deadline to fund the government is fast approaching, and it looks like we will only get another temporary (one-month) deal. The deal won’t include anything on immigration, however it will fund the Children’s Health Insurance Program for 6 years, and delays some Obamacare taxes. Bond Traders are not so sanguine on a deal, and are selling Treasuries maturing in early March.

Rising input costs are the biggest challenges to homebuilding. 84% of all builders surveyed said that rising labor costs and rising material costs are going to be a problem this year. High land prices are also an issue. Affordable housing is one of the nation’s biggest problems right now, and it is extremely difficult to build at price points that are affordable for the entry-level homebuyer.

Industrial Production rose 0.9% in December and manufacturing production rose 0.1%. Capacity Utilization jumped to 77.9% from 77.3%. Utilization is still relatively low, and indicates that we still have plenty of unused capacity. High utilization rates (85%-ish+) are usually associated with increasing inflation.

Bitcoin is now trading below $10,000. Easy come, easy go.

Morning Report: Possible government shutdown? 1/16/18

Vital Statistics:

Last Change
S&P Futures 2801.3 12.5
Eurostoxx Index 399.0 1.2
Oil (WTI) 63.9 -0.4
US dollar index 84.6 0.2
10 Year Govt Bond Yield 2.54%
Current Coupon Fannie Mae TBA 101.75
Current Coupon Ginnie Mae TBA 102.875
30 Year Fixed Rate Mortgage 4.03

Stocks are higher this morning as on overseas strength. Bonds and MBS are up small.

Not a lot of market-moving data this week, however we do get housing starts and the FHFA House Price Index. Bank earnings will dominate the releases this week.

The Empire State Manufacturing Survey came in a little weaker than expected, but was still pretty strong. Employment-related indicators (number of workers and average workweek) decelerated a touch, however the inflation indicators (both prices paid and prices received) increased. The bond market seems to be taking the inflation data in stride.

The big thing this week will be a continuing resolution to keep the government open. The government will shut down if a budget deal isn’t reached by Friday. Democrats are holding out over immigration. Republicans are weighing another short-term funding measure that will last until mid-February.

So far, it looks like the meta-issue for 2018 will be inflation. Numerous companies have announced wage increases in response to the tax bill, and some states have raised the minimum wage. Commodity prices remain firm (especially food and energy). In order to really get inflation, we need wage inflation and so far we haven’t really seen a lot in the BLS numbers. That said, with all the company announcements over raises this could be the year.

Dallas Fed President Robert Kaplan believes we are going to “overshoot full employment” and he thinks we will need to see 3 rate hikes this year. His personal GDP forecast is 2.75% growth. “The history of overshooting full employment in this country has not been a happy one,” he added. “Normally, what happens is you get an overheating, the Fed has to play catch up, and what happens then is you tend to often have a recession.” Historically (post-Great Depression) that has been the case: the economy grows, inflation starts, and the Fed causes a recession to beat back inflation. That model probably works 90% of the time, but post-bubble economies are different, and have longer (and shallower) recoveries. The excesses of the bubble years may have been worked off, however the psychology of the bust instills a risk-aversion on the part of the business community that isn’t necessarily conducive to inflation. Japan has been trying to create inflation since the early 90s and they still haven’t been able to do it. The US isn’t necessarily Japan, however the Japanese experience shows that the usual economic playbook goes out the window after asset bubbles.

The black swan for US inflation? The bursting of the Chinese real estate bubble. This will be a drag on overall global growth and commodity demand.

Morning Report: Congress cracks down on serial VA refinancing 1/12/17

Vital Statistics:

Last Change
S&P Futures 2769.0 -0.5
Eurostoxx Index 397.5 0.2
Oil (WTI) 63.2 -0.6
US dollar index 85.3 -0.2
10 Year Govt Bond Yield 2.58%
Current Coupon Fannie Mae TBA 101.75
Current Coupon Ginnie Mae TBA 102.875
30 Year Fixed Rate Mortgage 4.01

Stocks are flat this morning on no real news. Bonds and MBS are down small.

Inflation on the consumer level continues to be under control, according to the Consumer Price Index. The headline number was up 0.1% MOM and 2.1% YOY. The core rate, which excludes food and energy) was up 0.3% MOM and 1.8% YOY. Housing and medical costs drove the increase in the rate.

Retail Sales were up 0.4% in December, which was a touch below expectations. The control group was up 0.3%, which was in line with expectations. The MOM numbers may seem low, however November was exceptionally strong.

Robert Kaplan said the Fed has upped their 2018 economic forecast to 2.5% – 2.75%. The current estimate is at 2.5%. After having been too high in their GDP estimates for 9 years, the Fed finds itself in the position of consistently being too low.

The two year bond yield topped 2% for the first time since the financial crisis. The 2 year is much more sensitive to the Fed Funds rate than the 10 year is, and is part of the reason why we are talking about a yield curve flattening and what it means. A common narrative these days is that the yield curve is flattening (that is, the difference between long-term rates and short-term rates is falling) and that signals a recession. That could be the case if the Fed tightens more aggressively than they are now, however they are going at such a slow pace that it probably won’t knock the economy into a recession. Plus there is so much pent-up demand from the last 10 years that a lot of the necessary pieces for a recession simply aren’t in place.

Where do we stand with the market’s prediction of rates? The Fed Funds futures are now pricing in a 73% chance of a 25 basis point hike in March. This is up from 59% a month ago.

Wells Fargo reported higher earnings, however part of that was due to a one-time benefit due to the tax bill. On the mortgage side, originations came in at $53 billion for the fourth quarter, down 10% QOQ (largely explained by seasonality) and down 26% from a year ago. Margins were up a basis point from the third quarter and were down 43 basis points from a year ago.

The Administration and the Senate continue to work on hammering out a deal on funding the government. The current continuing resolution expires in a week, and Democrats are holding out for an immigration deal in order to sign off on a new CR. It is still too early to predict a shutdown, but remember that a shutdown will affect the IRS and getting tax transcripts. Plan accordingly.

Washington is looking to do something about serial VA refinances.  Many veterans were refinancing their mortgages (and adding to their principal by folding in the funding fee) for a de minimus drop in monthly payment. The Protecting Veterans from Predatory Lending Act of 2018 will make the following changes to VA lending.

  • A lender may only submit a refinance loan for VA insurance if it certifies that all fees associated with the refinance would be recouped through lower monthly payments within three years;
  • A lender may only receive VA insurance for a refinance loan if the refinance loan has a fixed rate 50 basis points lower than the earlier fixed-rate loan (or 200 basis points lower if the new refinanced loan is an adjustable rate mortgage).
  • A lender may only receive VA insurance or get a Ginnie Mae guarantee for a refinance loan if the refinance comes more than six months after the initial loan.

At the margin, this legislation is bullish for Ginnie Mae TBAs and Ginnie Mae servicing, which should translate into better FHA and VA rates going forward.

Morning Report: Walmart raises wages 1/11/18

Stocks are higher this morning on no real news. Bonds and MBS are up.

Inflation came in weaker than expected at the wholesale level, with the producer price index falling 0.1% MOM and increasing 2.6% YOY. The core index (which strips out food, energy, and trade services) rose 0.1% and is up 2.3% YOY.

Bonds were trying to break through support yesterday, however a decent 10-year auction pushed rates lower. The 10 year yield dropped 2 basis points on the result and is holding those levels this morning after the weaker than expected PPI. The Chinese government said that yesterday’s Bloomberg story of a potential slowdown or suspension of Treasury purchases could be fake news.

Initial Jobless Claims rose to 261k in a holiday-shortened week. I would bet most of this is being driven by post-holiday retail layoffs.

Wal-Mart is raising its starting wage to $11 an hour and handing out bonuses to employees. They are just the latest in a string of companies that announced raises and bonuses recently. We’ll see if this moves the needle in the official wage inflation numbers out of BLS. It is interesting that most of the wage inflation seems to be occurring at the bottom end of the scale.

Mortgage Credit Availability decreased in December, according to the MBA. Government programs (FHA/VA) especially at lower FICO and higher LTVs were the biggest decliners. Note that GNMA servicing values did get hit in 2017 as prepay speeds were generally higher than the benchmark TBAs were forecasting. That said, we saw a tightening of credit in all products, including jumbo. Despite the monthly drop, credit availability is still up substantially from a year ago.

The Kansas City Fed is out with their housing outlook for 2018, and it predicts continued price increases as pent-up demand remains unsatisfied. Household formation remains below the benchmark forecast done in 2000 based on demographics. Part of this is a continuation of the decades-long trend of Americans marrying and having kids later than previous generations. Student loan debt is also a factor. That said, the shortfall is astounding – about 3.5 million households. That is almost 3 years’ worth of housing starts at current levels! Housing starts would need to double to satisfy that demand. If we get 2 million plus housing starts, we are looking at the strongest growth since the 90s. Lack of workers, available land, and land use regulations remain the bottlenecks.

Last year, the Fed paid $80 billion in profits to Treasury. Long-term rates fell slightly during the year and that number was lower than 2016. For those keeping score at home, that works out to be a 1.8% ROA, which is pretty punchy for a bank. The big question is what happens if rates move up faster than the Fed anticipates?

The Trump Administration is reviewing the Community Reinvestment Act, to make compliance easier and more transparent.

Morning Report: Bonds testing support 1/10/18

Vital Statistics:

Last Change
S&P Futures 2741.5 -10.8
Eurostoxx Index 398.0 -216.0
Oil (WTI) 63.6 .06.6
US dollar index 85.6 -0.4
10 Year Govt Bond Yield 2.58%
Current Coupon Fannie Mae TBA 101.75
Current Coupon Ginnie Mae TBA 102.875
30 Year Fixed Rate Mortgage 4.01

Stocks and bonds are lower this morning on news that China may slow or halt its purchases of Treasuries.

Bonds are currently trading at 2.58% after Chinese officials recommended slowing or halting purchases of US Treasuries. Driving this decision are the relative attractiveness of US Treasuries and the possibility of a trade war. Between the Fed tapering their purchases of Treasuries, and potential disinvestment of the Chinese, Treasuries are heavy. Ultimately, this is about the trade deficit, which is the difference in value between what we import from China and what we export to China. The deficit is simply filled in by Treasury purchases. While a trade war is probably just saber-rattling, a drop in trade will probably mean a drop in the trade deficit, which means less demand for Treasuries. Ultimately, the US would prefer the Chinese to buy less Treasuries since that would mean they are buying more goods and services.

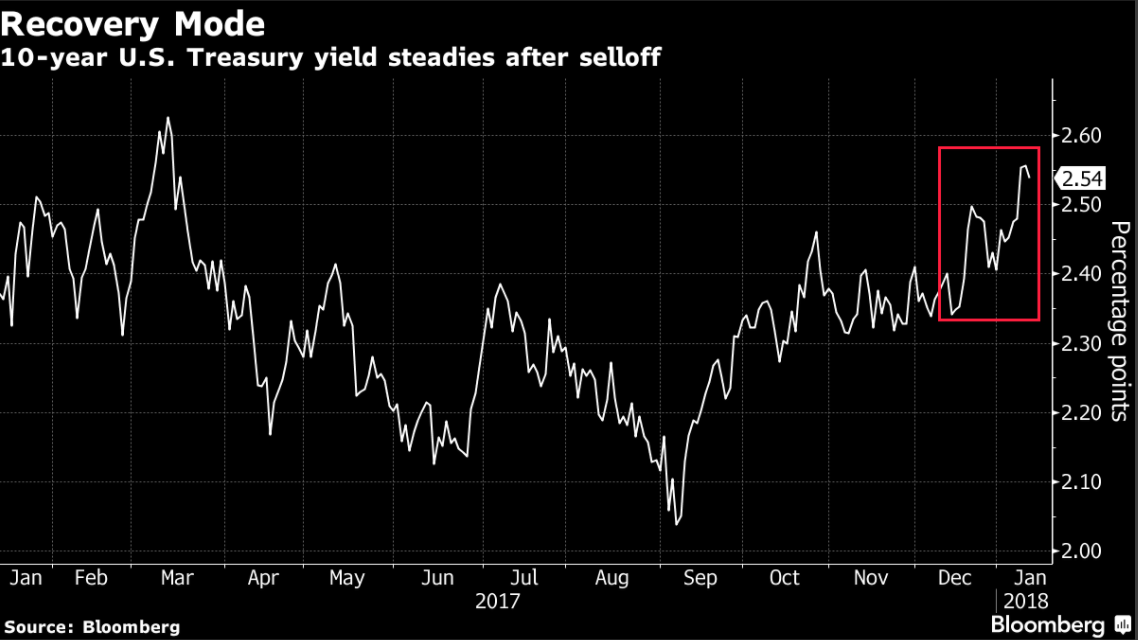
Note that the recent peak in the 10 year was 2.62% in March this year. We are close to breaking through support, which would probably trigger at least some technically-driven selling. We have a 10 year bond auction this afternoon at 1:00 pm EST. If we get a lousy bid / cover ratio that could be the catalyst to break through that level.

We have a lot of Fed-speak today, with Charles Evans, Robert Kaplan and James Bullard speaking.

Mortgage Applications rose 8.3% in a holiday-shortened week, as purchases rose 5% and refis rose 11%. The average contract rate for the 30 year conforming rate rose a basis point to 4.23%.

Import prices rose 0.1% MOM and 0.3% YOY, while export prices fell 0.1% MOM and rose 2.6% YOY.

Lennar reported fourth quarter earnings of $1.29 a share which missed analyst expectations. An undisclosed “one-time strategic transaction” was delayed until the first quarter, which apparently drove the miss. Revenues increased 12%, while deliveries were up 5% in units. Backlog was up 17% in units and 23% in dollars. Gross margins fell by 90 basis points to 22.4%. Lennar is also in the process of buying CalAtlantic, and that deal should close in February.

The National Association of Homebuilders projects that 653,000 new homes will be sold in 2018, an increase of 5.4% from 2017. This won’t be enough to meet demand. Lack of labor and land are the limiting factors, as well as government regulations. It seems that “urban villages” are the flavor du jour, with apartments and walkable developments that mix commercial and residential.

Morning Report: Volatility and mortgage rates 1/9/18

Vital Statistics:

Last Change
S&P Futures 2751.3 4.5
Eurostoxx Index 400.3 1.9
Oil (WTI) 62.0 0.2
US dollar index 86.0 0.1
10 Year Govt Bond Yield 2.50%
Current Coupon Fannie Mae TBA 102.313
Current Coupon Ginnie Mae TBA 103.063
30 Year Fixed Rate Mortgage 3.92

Stocks are higher this morning on good economic data out of Europe. Bonds and MBS are down.

Small Business Optimism slipped slightly in December, capping the strongest year in the index since the early 80s. Hiring was sluggish in December, with a lack of qualified workers being the biggest problem in construction and manufacturing. Compensation is trending up as well, as a net 23% of small businesses intend to raise compensation this year.

Job openings were little changed in November, according to the JOLTs survey. This was a slight drop from October, and a touch below expectations. Openings increased for retail, and fell for government, transportation, and utilities. The quits rate was unchanged at 2.2%. Until we start seeing the quits rate move up, we probably won’t be seeing broad-based wage inflation.

Volatility in the bond market has hit a 52 year low, according to a Bank of America / Merrill Lynch report. This is not surprising: volatility in the stock market is also at record lows. Volatility is generally a sign of stress in the system, and it tends to fall during periods of stronger growth.

The drop in bond market volatility has major implications for the mortgage market as well, and helps explain a bit of why mortgage rates are behaving the way they are. While the 10 year has been steadily moving higher over the past few months, mortgage rates have been relatively stable. While mortgage rates do tend to lag Treasuries, something else has been going on, and that something has been low volatility.

30 year fixed rate mortgages have an embedded option in them, which is the right of the borrower to prepay their mortgage without penalty at any time. That right to prepay is worth something, and that value explains the yield differential between government backed mortgage debt and Treasuries. The value of the prepayment option is determined largely by the volatility of the bond market – when volatility rises, the right to prepay is worth more, and when volatility falls, it is worth less. So, when the market is stable, investors bid up mortgage backed securities as the value of that option falls, which translates into tighter MBS spreads and lower mortgage rates. In fact, the difference between a 30 year fixed rate mortgage and an adjustable rate mortgage is driven by the value of that prepayment option and risk-shifting between borrower and lender. When volatility is low, the borrower is paying less for that option and 30 year fixed rate mortgages will be more attractive than ARMS. When volatility is high, ARMS will be much cheaper. During periods of low volatility, it makes sense to scoop up that prepay option on the cheap and take out a 30 year fixed rate mortgage. When volatility is high, you will end up getting a much lower initial rate with the ARM. Co-incidentally, the economic backdrop (stronger growth, accelerating inflation, and a Fed raising short term rates) also favors the 30 year fixed over ARMS.

Morning Report: Construction Boom in 2018? 1/8/18

Vital Statistics:

Last Change
S&P Futures 2738.0 -4.5
Eurostoxx Index 398.3 1.0
Oil (WTI) 61.6 0.2
US dollar index 85.9 0.0
10 Year Govt Bond Yield 2.47%
Current Coupon Fannie Mae TBA 102.375
Current Coupon Ginnie Mae TBA 103.25
30 Year Fixed Rate Mortgage 3.91

Stocks are lower this morning on no real news. Bonds and MBS are down small.

Should be a relatively quiet week, data-wise. The only potential market moving report will be inflation data on Friday. We will have a lot of Fed-Speak this week however.

The National Association of Realtors thinks we could be in for a construction boom in 2018. Much of the action will be in non-residential, mainly office building, lodging and logistics. Residential is a mixed bag – we have had a boom in apartment construction, but single family is still weak. The biggest problem for construction is labor, and many construction workers are aging out of the workforce. In 2017, a net 190,000 construction workers entered the job market, which is lower than the three year average of 284,000. This means construction firms are going to need to raise wages. One thing is for sure: if we do in fact see a construction boom in 2018, the Fed’s 2018 estimate of 2.5% growth is going to be too low. It also means the Fed will probably raise rates a little faster than expected.

The Fed Funds futures are currently pricing in a 61% chance of a 25 basis point hike in March. Despite the weak payroll number on Friday, the futures upped their probability of a hike.

One market-based measure of inflation – the TIPS spread – broke 2% for the first time in 9 months. TIPS (Or Treasury Inflation Protected Securities) increase the principal amount of the note by the annual consumer price inflation number, so they act as a hedge (at least in theory) against inflation. The 2% break-even yield is important as that is the Fed’s inflation target.

Republicans and Democrats are still far apart on a spending deal to keep the government open. Democrats want something done on DACA, while Trump wants funds allocated to a southern border wall. We are still far enough out that much of what we are seeing may just be posturing, but there is a possibility we could be looking at a government shutdown. Loan officers who need 4506-T tax transcripts should keep this in mind. The deadline is January 19.

Delinquencies rose in November, according to Black Knight Financial Service’s November Mortgage Monitor. You generally see an increase in November due to seasonality, but this year also includes the effects from the hurricanes in Texas and Florida. The report also checked in on negative equity. We still have homes more than 15% below their peaks in the areas hit hardest by the housing bubble (inland CA, Las Vegas, Florida, parts of the Northeast). The map below shows the current state of affairs:

home prices versus peak