Morning Report 5/24/12

Vital Statistics:

  Last Change Percent
S&P Futures  1317.8 2.1 0.16%
Eurostoxx Index 2154.3 20.3 0.95%
Oil (WTI) 90.56 0.7 0.73%
LIBOR 0.467 0.000 0.00%
US Dollar Index (DXY) 82.14 0.046 0.06%
10 Year Govt Bond Yield 1.75% 0.02%  
RPX Composite Real Estate Index 176.7 0.5  

Markets are giving up earlier gains on the back of some disappointing economic reports. Euro sovereigns are higher with the exception of Greece which now yields 30% and Portugal. Bonds are down a point and MBS are down a few ticks as well.

The Durable Goods headline number came in at +.2%, more or less in line with expectations, but DG ex transportation fell .6%. Cap Goods orders and shipments both fell. This metric tracks business investment and is an ominous sign for the economy.  This might explain why HP is laying off 27,000 workers.  

Initial Jobless claims came in at 370k, in line with expectations.

Freddie Mac released their Economic and Housing Outlook yesterday. It mainly re-hashes data we have already seen. They are of the view that housing is at or near bottom and that rental vacancies are at 9-year lows.

The housing market had another positive data point with the Toll Brother’s earnings announcement. Toll is in the McMansion business, so this report focuses more on the high end. Q2 revenues rose 14% YOY, but signed contracts increased 51%.  Backlog was up 49%. Granted, we are coming off of a low base, but you are starting to see some life in homebuilding. Doug Yearley, CEO said “It appears that the housing market has moved into a new and stronger phase of recovery as we have experienced broad-based improvement across most of our regions over the past six months. The spring selling season has been the most robust and sustained since the downturn began.”  Granted, he is talking his book, but still…

Morning Report 5/23/12

Vital Statistics

  Last Change Percent
S&P Futures  1305.2 -9.6 -0.73%
Eurostoxx Index 2148.5 -44.3 -2.02%
Oil (WTI) 91.15 -0.7 -0.76%
LIBOR 0.467 0.000 0.00%
US Dollar Index (DXY) 81.71 0.218 0.27%
10 Year Govt Bond Yield 1.74% -0.03%  
RPX Composite Real Estate Index 176.2 0.6  

Markets are lower this morning on GREXIT (Greek exit) fears and a lousy earnings report from Dell. Euro sovereign yields are generally lower, with the exception of Greece which is 22 basis points higher and approaching 30%. Remember, this is the post-reorg debt that is trading here. Their debt was trading around 35% before Greece did their restructuring about 10 weeks ago. The stress in Europe is pushing down bond yields here and MBS are up as well.

While the migration to tablets is hurting Dell, they also noted corporations are delaying spending.  Is it because IT spending is slowing in general, or is it that corporations have learned not to beta-test Microsoft operating systems (in this case Windows 8)? 

The Congressional Budget Office weighs in on Taxmageddon. Punch line: The budget deficit will drop by $560 billion, and real GDP growth will be .5%, with a contraction of 1.3% in 1H and an expansion of 2.3% in 2H. Remember the government operates on a Sep fiscal, so they are predicting recession in the Sep 12 – Mar 13 time period. If we cancel the tax increases and spending cuts, CBO estimates that real GDP growth would be about 4.4% in real (not nominal) terms in CY13. That is an aggressive (with a capital “A”) forecast. 

DealBook has an interesting article on the possible unintended consequences of breaking up the big banks.

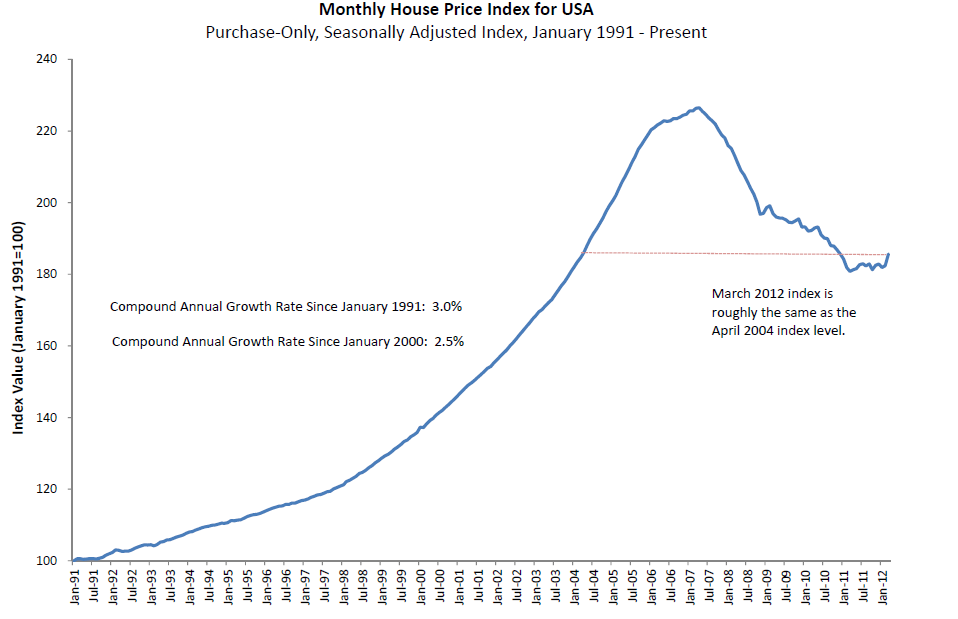
In other news, the NAR has declared the housing recovery to be underway. The MBA reported that mortgage applications increased 3.8% last week. New home sales in April were 343k, an increase of 3.3% MOM. The FHFA House Price index showed an increase of .55% QOQ and .5% YOY.  This is the first increase since early 2007.  Remember the FHFA index only looks at conforming loans, which is more of the “core” housing market.  It has proven to be a much less volatile index than Case-Schiller or RPX. 

Chart:  FHFA House Price Index:


Morning Report 5/22/12

Vital Statistics:

  Last Change Percent
S&P Futures  1319.1 3.4 0.26%
Eurostoxx Index 2181.4 31.3 1.45%
Oil (WTI) 92.34 -0.2 -0.25%
LIBOR 0.467 0.000 0.00%
US Dollar Index (DXY) 81.2 0.119 0.15%
10 Year Govt Bond Yield 1.78% 0.04%  
RPX Composite Real Estate Index 175.7 0.1  

Markets are generally firmer this morning on hopes of further stimulus out of China and Europe. Euro sovereign yields are lower. US bond futures are down a point and MBS are down slightly.  MBS underperformed bonds in the rally, so they should outperform as bonds retrace.

Richmond Fed came in below expectations. This survey looks at the service sector for Richmond, Baltimore and Charlotte. Revenues actually contracted in May. They note that service providers expect stronger customer demand over the next six months, while retailers do not. 

Existing Home Sales came in at 4.62MM annualized.  5.5 million is about “average.”  The number is up 10% YOY. The lack of distressed sales and the seasonal move towards bigger houses increased the median price 10% from 161,100 to 177,400. Overall, it notes that the headwinds in the real estate sector are abating.

Yesterday we had a number of sizeable mergers, with Eaton buying Cooper Industries for 12.8 billion, DaVita buying Healthcare Partners for 4.5B and Wanda Group buying AMC. Generally speaking, mergers are a good sign for the markets and the economy in general.

Andrew Ross Sorkin has a good column on why Glass Steagall wouldn’t have prevented the crisis. The Glass-Steagall issue has become a facile explanation of what went wrong. Elizabeth Warren even acknowledges this – one of the reasons she has been pushing reinstating GS – even if it wouldn’t have prevented the financial crisis – is that it is an easy issue for the public to understand and “you can build public attention behind.”  And there you have it. Never mind that nobody else in the world (the UK, Europe, Japan, Canada) separates commercial and investment banking, or even draws a distinction between the two. 

What was the rationale behind Glass-Steagall in the first place?  Poorly underwritten deals (for example, Facebook).  Facebook was the quintessential poorly underwritten deal.  An underwritten deal means that the investment banks (primarily Morgan Stanley) actually write a check to the company and buy 421MM shares at 38. It then places those shares with institutional investors.  If the deal is handled well, Morgan Stanley sells all the stock, collects its fee and moves on. This deal did not go well, obviously. Institutional investors sold into the market and FB was in danger of breaking price. Morgan Stanley stood in the market and bought everything that the market was willing to sell at the offer price. (If an IPO breaks price on the first day, that is a MAJOR embarrassment to the investment bank). So Morgan Stanley is now lugging millions of Facebook shares that it bought in the market at 38. The stock is trading at 32.65. Huge loss. Pre-Glass Steagall, what would they do?  Sell the stock to their captive commercial bank at 38. (Hey, we bumped up your allocation to 5 million shares)  Institutional investors will pull their money out quickly if they sense an investment bank is in trouble.  Depositors at a sleepy commercial bank?  Not so much.  Note:  This was done more with bond issues than stock issues, but the rationale remains the same. In the Great Depression, commercial banks were failing and it turned out their assets were not home mortgages or commercial loans – they were all the lousy deals their sister investment bank couldn’t unload. That is why we had Glass-Steagall – to prevent commercial banks from being repositories for losing positions. 

Fast forward to the financial crisis – commercial banks weren’t failing because they bought CDO-squared issues from their investment banking divisions. Or because Citi was stuffing its retail bank with LBO paper it couldn’t unload. The reason we had a financial crisis is because we had a residential real estate bubble.  Every bank in the US is exposed to residential real estate in some way, shape, or form. And it didn’t matter whether you were exposed to residential real estate through a mortgage backed security or through holding whole loans on your balance sheet.  The small community banks who wouldn’t know a CDO from a codfish blew up just the same as the big integrated banks 

Probably the single best thing regulators could do to prevent a re-occurrence would be to deal with the cascading counterparty risk from OTC derivatives. They should demand that OTC derivatives become standardized and exchange-traded with a central clearing party, position limits, and open interest disclosure. That would have prevented AIG from taking the positions it did and exposing all of its counterparties when it failed.

Morning Report 5/21/12

Vital Statistics:


Last

Change

Percent

S&P Futures 

1296.5

5.7

0.44%

Eurostoxx Index

2146.8

2.1

0.10%

Oil (WTI)

91.62

0.1

0.15%

LIBOR

0.467

0.000

0.00%

US Dollar Index (DXY)

81.26

-0.036

-0.04%

10 Year Govt Bond Yield

1.73%

0.01%


RPX Composite Real Estate Index

175.6

0.0


Markets are generally firmer this morning on comments from Chinese Premier Wen Jiabao supporting further measures to boost the economy. Euro sovereign sovereign spreads are a touch wider. Bonds and MBS are down.

The Chicago Fed National Activity Index rose .11 in April after falling .44 in March. This basically means that the economy is growing at its historical trend. Anything between -.7 and +.7 is considered on trend. Production was a positive factor, while consumption was negative. Employment was neutral.

Is the Fed more optimistic about future growth than Wall Street?  It appears to be the case. The average Wall Street growth forecast for 2012 is 2.3%, while the Fed is forecasting 2.4% – 2.9% growth. One explanation is that the Fed underestimates how much the credit-multiplier breaks down in the aftermath of asset bubbles. Meanwhile, the TIPS market is trimming its inflation forecast and giving Ben Bernake the room to maneuver.

Facebook has broken the IPO price in the pre-open and is trading at 36.51.  5.6 million shares have traded. Bob Griefeld, CEO of NASDAQ, blamed software glitches for the problems with trading FB on Friday where customer sell orders were delayed on the open.

Morning Report 5/18/12

Vital Statistics:


Last

Change

Percent

S&P Futures 

1307.5

6.2

0.48%

Eurostoxx Index

2155.6

8.7

0.40%

Oil (WTI)

92.68

0.1

0.13%

LIBOR

0.467

0.000

0.00%

US Dollar Index (DXY)

81.38

-0.004

0.00%

10 Year Govt Bond Yield

1.72%

0.02%


RPX Composite Real Estate Index

175.6

0.1


Markets are firmer this morning after enduring a bloody week which sent the S&P down 3.6% and the 10 year government bond yield down to 1.69%. Today is also the expiration of May options, so there is always the potential for funny closing prints. There is no economic data being released this morning.  Bonds and MBS are down slightly.

It’s Facebook Day! Facebook priced at the top end of the revised range last night and should begin trading around 11:00. There are a stocks that capture the attention of the populace and Facebook is one of them. Growth fund managers who have been starving for a good growth story besides Chipotle Mexican Grill and Lululemon just got a new one. With an IPO price at 28x revenue, the stock will have to almost collapse to get value and GARP guys interested. I’m sure if you are a good technical trader, you should be able to have a field day with this one. Treat it as a slip of paper with an alphanumeric code, not an investment, cause it isn’t.

Bloomberg has a column on why principal reductions won’t solve the housing crisis. The big problem is that something like 80% of all underwater homeowners with Fan and Fred mortgages are current on their mortgages. Any principal reduction program will encourage people to stop paying their mortgage. Second, of those seriously delinquent, most of them won’t be able to afford the lower payment anyway.

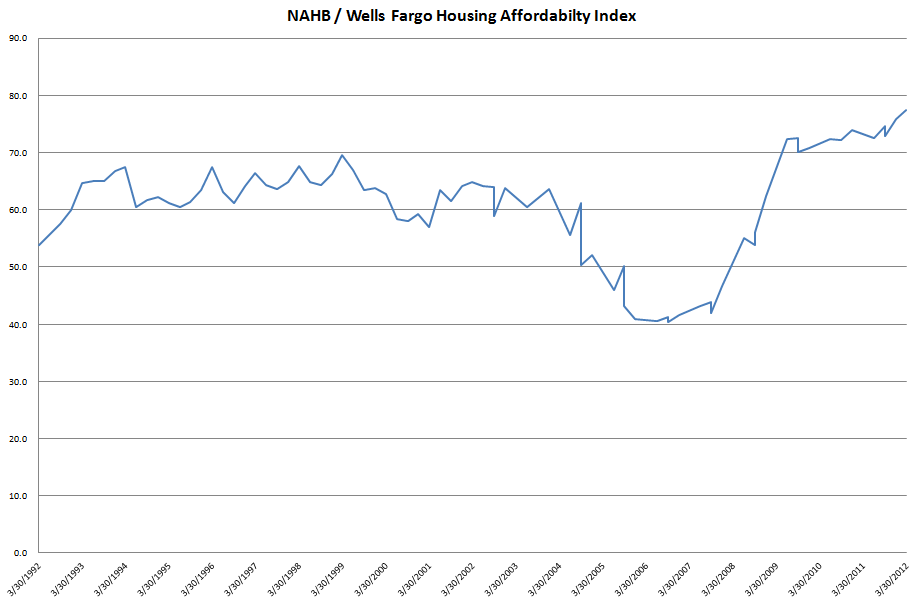
The National Association of Home Builders and Wells Fargo have constructed a housing affordability index, which is a measure of the percent of homes affordable by someone at the median income. The latest index is 77.5, which means 77.5 percent of all new and existing homes sold in Q1 were affordable for families earning the national median income. In a lot of ways, this chart is the inverse of my median house price to median income chart.

Chart: NAHB / Wells Fargo Housing Affordability Index:


Morning Report 5/17/12

Vital Statistics:


Last

Change

Percent

S&P Futures 

1319.6

-2.8

-0.21%

Eurostoxx Index

2140.4

-35.0

-1.61%

Oil (WTI)

93.04

0.2

0.25%

LIBOR

0.467

0.000

0.00%

US Dollar Index (DXY)

81.59

0.218

0.27%

10 Year Govt Bond Yield

1.76%

0.00%


RPX Composite Real Estate Index

175.6

0.1


Markets are lower this morning on a report in the Spanish press that Moody’s will downgrade the Spanish banks today and the continuing stand-off between the ECB and the Greek banks. The Spanish IBEX stock exchange is down 24% for the year and is at 9 year lows. Despite the headlines, Euro sovereign yields are flat / lower.

Initial Jobless claims came it at 370k, in line with expectations and we have good earnings from Wal-Mart and Sears. Later today, we will get Philly Fed. Bonds and MBS are up slightly.

Facebook prices tonight and should start trading tomorrow. Barry Ritholtz weighs in. David Einhorn took aim at AMZN at the Ira Sohn conference. His comments could have come from a Alan Abelson column in 1999. I expect to hear a lot of the same “you don’t get it” arguments on FB that we heard on AMZN back then.

The minutes of the April FOMC meeting were released yesterday afternoon. They note the possibility of “taxmageddon” – the expiration of the Bush tax cuts – as a sizeable risk to the economy. While they note the size of the shadow inventory and tight lending standards, they believe real estate prices have stabilized. Overall, there seem to be no major changes in this statement – the Fed remains open to QEIII should economic conditions warrant. 

Ellie Mae released their latest Origination Insight Report. Ellie Mae provides loan processing software and handles about 20% of US mortgage loan origination. Typical profile of a denied loan?  702 FICO / 87 LTV / DTI 28/43.  Talk about a tight mortgage market. 

The problem with having a London Whale is that you have thousands of Ahabs shooting harpoons at you once you disclose you are in trouble with an oversized position. Dealbook is estimating that JP Morgan’s trading losses have increased from $2 billion to $3 billion in the last 4 days as every wise-guy hedge fund manager that missed the initial trade puts it on.

Morning Report 5/16/12

Vital Statistics:


  Last Change Percent
S&P Futures  1334.7 6.5 0.49%
Eurostoxx Index 2186.7 8.0 0.37%
Oil (WTI) 92.98 -1.0 -1.06%
LIBOR 0.467 0.001 0.21%
US Dollar Index (DXY) 81.31 0.086 0.11%
10 Year Govt Bond Yield 1.80% 0.03%  
RPX Composite Real Estate Index 175.5 0.4  

S&P futures are firming this morning after hitting lows of 1321 overnight. Good earnings reports from Target and Deere seem to be overshadowing the bank run going on in Greece. Greek, Irish and Portuguese yields are higher this morning. US Treasuries are down half a point while MBS are flat. Everyone is waiting for the minutes of the last FOMC meeting which will be released this afternoon. 

Industrial Production increased 1.1% in April, a reasonably strong reading. Capacity Utilization ticked up to 79.2%, but the Fed revised down everything for the past year.

The recent drop in rates is triggering refi activity, as evidenced by a 9.2% jump in mortgage applications last week.

April Housing Starts came in at a 717k annualized rate, better than expectations, but still horribly depressed. To put that number in perspective, the in the 74-75 recession, starts bottomed at 904k.  In the 81-82 recession, they bottomed at 837k. In the 91-92 recession, they bottomed at 798k.  These bottoms were V-shaped and typically lasted 6 months or so before returning to normalcy of around 1500.  When was the last time we saw a 800k print?  September of 2008 – almost 4 years ago. Housing historically leads the economy out of a recession, and its absence has been a big part of why this recovery has been so anemic.

Is the summer of 2012 going to be a replay of the summer of 2011?  Certainly the pieces are being put in place – Europe’s sovereign debt crisis is again in the forefront, the economy is decelerating after a good Q4 / Q1, and the old saw “Sell in May and go away” was good advice again. We even have the prospect of major tax increases Jan 1 as the Bush tax cuts expire. The only thing we are missing is a debt ceiling fight. Oh, wait…

The Florida Supreme Court is hearing an foreclosure case that asks an interesting question – can the banks who filed foreclosures based on robo-signed documents voluntarily dismiss these cases and re-file them with better documents?

The good market reception to the Facebook IPO means that sellers are increasing the amount for sale. Existing holders like Goldman, Tiger, and Accel are blowing out of 241MM shares, much more than they originally planned.  Surprisingly, and perhaps no coincidentally,  GM has dropped paid advertising with Facebook because they “weren’t effective enough”. Apparently “likes” doesn’t necessarily translate into sales or dealer inquiries.

Morning Report 5/15/12

Vital Statistics


Last

Change

Percent

S&P Futures 

1336.0

1.9

0.14%

Eurostoxx Index

2179.7

-22.2

-1.01%

Oil (WTI)

94.71

-0.1

-0.07%

LIBOR

0.466

0.000

0.00%

US Dollar Index (DXY)

80.89

0.280

0.35%

10 Year Govt Bond Yield

1.78%

0.02%


RPX Composite Real Estate Index

175.5

0.4


Markets are up this morning on a lack of news out of Europe and some mixed economic data. The Consumer Price Index showed inflation remains benign, while retail sales data showed spending up slightly and below expectations. Bonds and MBS are down slightly. Greek bond yields are up 160 basis points. Portugal and Ireland are up as well 

The New York Fed released its Empire State Manufacturing Survey this morning, which came in better then expected on higher shipments. Six month optimism fell.

The National Association of Home Builders released its builder confidence survey this morning, which showed improving sentiment.

The Washington Post is starting to focus on the tax hikes that will take place in the beginning of 2013. They note the uncertainty that it is causing. So far, there seems to be no discussions in Washington about what to do about it. IMO this has been driving some of the recent deceleration in the economy.

Lots of institutional investors are clicking “Like” – Facebook raised the range of its IPO price from 28-35 to 34-38. At the top end of the range, FB would be valued at 26x sales – or about twice the valuation of the Google IPO.

Ally doesn’t plan on re-organizing the mortgage business and getting back in to the housing market. They are going to stick with car loans. Money Quote from Ally CEO Michael Carpenter: “You can live in your car if you don’t pay your mortgage.  I don’t mean to be cute, but the fact is people make their car payment before they pay their mortgage.”

Chart:  NAHB Index:

Morning Report 5/14/12

Vital Statistics:

Last Change Percent
S&P Futures 1340.2 -9.8 -0.73%
Eurostoxx Index 2199.2 -55.4 -2.46%
Oil (WTI) 94.47 -1.7 -1.73%
LIBOR 0.466 -0.001 -0.21%
US Dollar Index (DXY) 80.51 0.248 0.31%
10 Year Govt Bond Yield 1.78% -0.05%
RPX Composite Real Estate Index 175.3 0.0

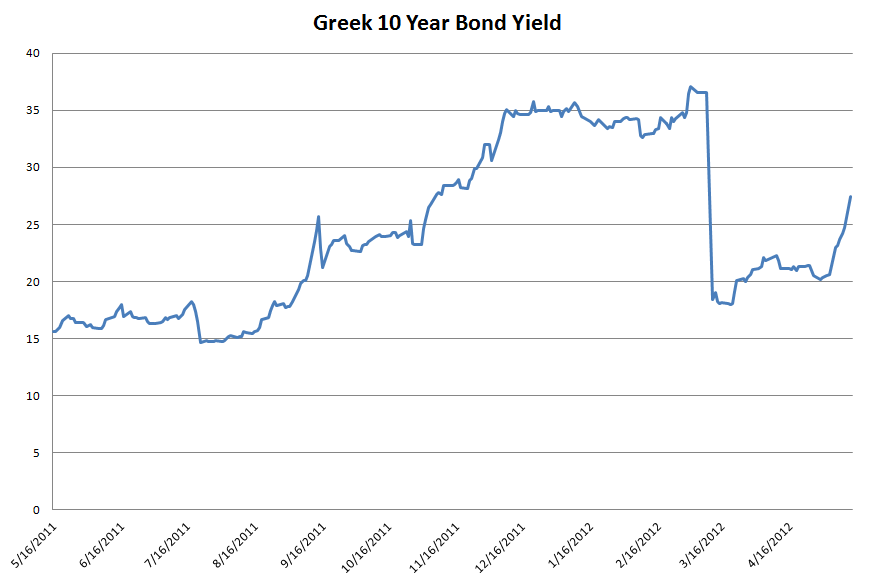
A sloppy start to the week as sovereign spreads widen in Europe. Greek sovereign debt is now trading at a 27.4% yield, which is the same level as last Nov. Don’t forget, this is the post-reorg debt – for those keeping score at home, Greek sovereigns were at 15% last year at this time, rose to over 40%, did a restructuring two months ago which pushed yields down to 17%, and now they are 27%. Spanish yields are rising, and it is time to start paying attention to the credit default swaps on the big European banks – Dexia is considered one of the worst cases, and is trading at the 17.75% level.

All of the stress in Europe is pushing down Treasury yields which sit about 10 basis points above September’s lows. MBS are higher as well, with the Fannie and Ginnie 3.5s up 6 ticks. This is putting pressure on oil and the Euro. The S&P futures are suggesting that the 200 day moving average is going to get broken on the open.

It is official – Ally’s Residential Capital has filed for bankruptcy protection. This move separates the auto loan and banking business, and should pave the way for the government to divest its 74% stake. Ally is providing the $150MM DIP and is kicking in $750MM.

It looks like 3 executives from JP Morgan will walk the plank over the $2 billion “hedging” loss in their Chief Investment Office unit. Jamie Dimon is not resigning, at least not yet. It is surprising that JP Morgan disclosed the loss before it fully exited the position – if disclosure rules forced his hand, that is a big unintended consequence. This episode will undoubtedly elicit calls for more regulation, and strengthens the view in Washington that there is no alpha in banking, just beta.

Chart: Greek 10 year bond yield:

Morning Report 5.11.12

Vital Statistics:


  Last Change Percent
S&P Futures  1349.3 -8.3 -0.61%
Eurostoxx Index 2231.1 -16.3 -0.72%
Oil (WTI) 96.03 -1.0 -1.08%
LIBOR 0.467 0.000 0.00%
US Dollar Index (DXY) 80.19 0.078 0.10%
10 Year Govt Bond Yield 1.85% -0.02%  
RPX Composite Real Estate Index 175.3 -0.1  

Markets are lower this morning after J.P. Morgan announced a $2 billion trading loss in its Chief Investment Office unit. April PPI showed inflation is behaving at the wholesale level. Bonds and MBS are higher.

The JP Morgan story is interesting. The position was supposed to be a hedge the bank’s credit exposure. However, if you read the Blooomberg story, it suggests the bank had sold protection on the Markit Series 9 CDX North American investment grade index. Which means it wasn’t hedging anything at all – selling protection and extending credit (which is what the bank does) are similar risks. The story goes on to speculate that it may have been some sort of spread bet, where the bank was short long-dated protection and long short-dated protection. Regardless, this position in no way hedges the bank’s overall business, at least as far as I can tell. Good luck getting out, guys. J.P. Morgan is going to get their eyes ripped out on the exit.

This incident will not cause a systemic risk in any way – if anything it will simply give ammo to the proponents of the Volcker Rule. A $2 billion loss for a bank that made $19 billion the year before and has $176 billion in equity is not fatal in any way. It also shows (again) the fundamental weakness in Value at Risk (VaR), which basically tells you the best case scenario when the fit hits the shan. JP Morgan stock is down 9.2% this morning. 

The CFPB has proposed rules for mortgage origination costs, which bans origination charges that vary by the size of the loan. Rob Christman summed it up perfectly:  “I’m sure that consumer groups are happy about it – just wait until they can’t find anyone who’s going to do a $100,000 loan.” The CFPB has also re-affirmed the anti-steering rules by the Fed.

The Facebook IPO is supposedly garnering lukewarm interest, at least at the price being discussed. It must be bad – I heard Mark Zuckerberg was seen this morning in a suit and tie, eschewing his traditional hoodie. The underwriters still have time to whip up excitement for the deal which should list on May 17 under they symbol FB.