

 Brent Nyitray
 Fairlington Blade
 Let the mutherfuker burn!
 jnc4p
 Kevin S. Willis
 Michigoose
 lmsinca
 markinaustin
 Arcanaut
 novahockey
 quarterback
 ScottC
 yellojkt
Will be away for the rest of the week, so no MRs
Be back next week.
Filed under: Morning Report | 16 Comments »
Will be away for the rest of the week, so no MRs
Be back next week.
Filed under: Morning Report | 16 Comments »
Vital Statistics:
| Last | Change | Percent | |
| S&P Futures | 1310.5 | -16.3 | -1.23% |
| Eurostoxx Index | 2135.2 | -51.6 | -2.36% |
| Oil (WTI) | 78.44 | -1.3 | -1.65% |
| LIBOR | 0.461 | -0.001 | -0.22% |
| US Dollar Index (DXY) | 82.51 | 0.250 | 0.30% |
| 10 Year Govt Bond Yield | 1.62% | -0.06% | |
| RPX Composite Real Estate Index | 181.4 | 0.2 |
A soggy tape to match a soggy morning here on Wall Street. There is no real news driving futures down, just a sense of malaise coming out of watching the European slow-motion train wreck. Euro sovereigns are slightly wider, while the US 10-year is up about a point. MBS are higher as well.
New Home Sales came in at 369k, well ahead of expectations of 347k. That said, we are still running at levels below the bottoms of recessions going back to the 1960s and well below the average 700k pace from 1963 to the bubble burst.
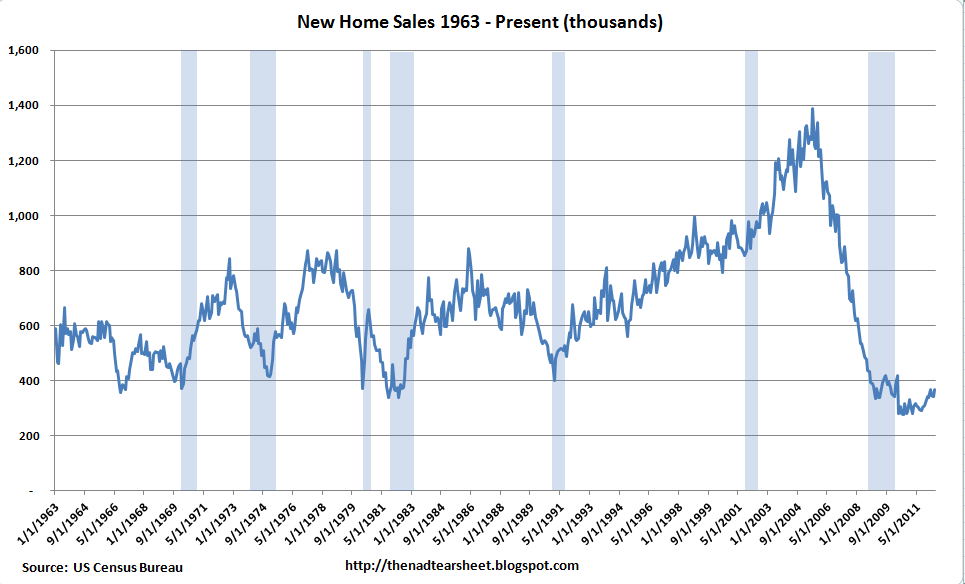
We have a lot of economic data this week, with April Case-Schiller and Consumer Confidence coming out tomorrow, Durable Goods and pending home sales Wed, Initial jobless claims and final Q1 GDP numbers on Thurs, and Personal Income / Spending numbers on Fri. We also have a European summit (something like #18) and will potentially hear the fate of Obamacare as well.
We are in earnings pre-announcement season, where companies who are going to miss their quarters disclose it to the market. Earnings season will officially begin in two weeks with Alcoa’s numbers.
Treasury yields will hit 1% by year end, says CNBC. Certainly that is a possibility if nothing is done about Taxmageddon or if Europe implodes. Simon Johnson is worried about how US banks will handle a European implosion, and even introduces a new risk we can wring our hands over: Dissolution Risk.
The Chicago Fed National Activity Index declined to -.45 in May from +.08 in April, which indicates slowing economic growth. Positive numbers indicate the economy is growing above trend, while negative numbers indicate the economy is growing below trend. The 3 month moving average, decreased to -.34 from -.13 in May. If the 3 month moving average falls below -.7, it typically means a recession has already begun.

$9.3 billion. That is the amount of money people lose per year responding to those ubiquitous Nigerian email scams. To put that number in perspective, that is roughly what GM made last year and accounts for 11% of Nigeria’s GDP.
Filed under: Morning Report | 16 Comments »
Vital Statistics:
| Last | Change | Percent | |
| S&P Futures | 1351.2 | 0.5 | 0.04% |
| Eurostoxx Index | 2220.9 | 13.5 | 0.61% |
| Oil (WTI) | 80.75 | -0.7 | -0.86% |
| LIBOR | 0.468 | 0.000 | 0.00% |
| US Dollar Index (DXY) | 81.6 | 0.012 | 0.01% |
| 10 Year Govt Bond Yield | 1.65% | -0.01% | |
| RPX Composite Real Estate Index | 180.7 | 0.2 |
Markets are flattish after a mixed Spanish bond auction and disappointing jobless claims numbers. Spain auctioned off 2.2 billion euros of 5 year debt, with a bid / cover ratio of 3:1, however it paid 6.07%. Sovereign yields across Europe are lower, as are Treasuries with the 10 year down a basis point. MBS are up slightly.
Yesterday, the Fed maintained low interest rates and committed to extend Operation Twist through the end of the year. Notably, the Fed took down its projections for GDP growth and bumped up its estimates for unemployment. Here is a “marked up” version of the statement, showing the changes from the April release. Note that the Fed took down its numbers in spite of a massive rally in the 10-year and mortgages courtesy of Europe.
Initial Jobless Claims came int at 387k, down from a revised 389k the prior week and more or less in line with expectations. Philly Fed was a disappointment as the Business Outlook Survey indicated weaker business conditions in its area. Rounding out the day’s economic data, May existing home sales came in at a 4.55 million annual rate, a drop of 1.5% MOM.
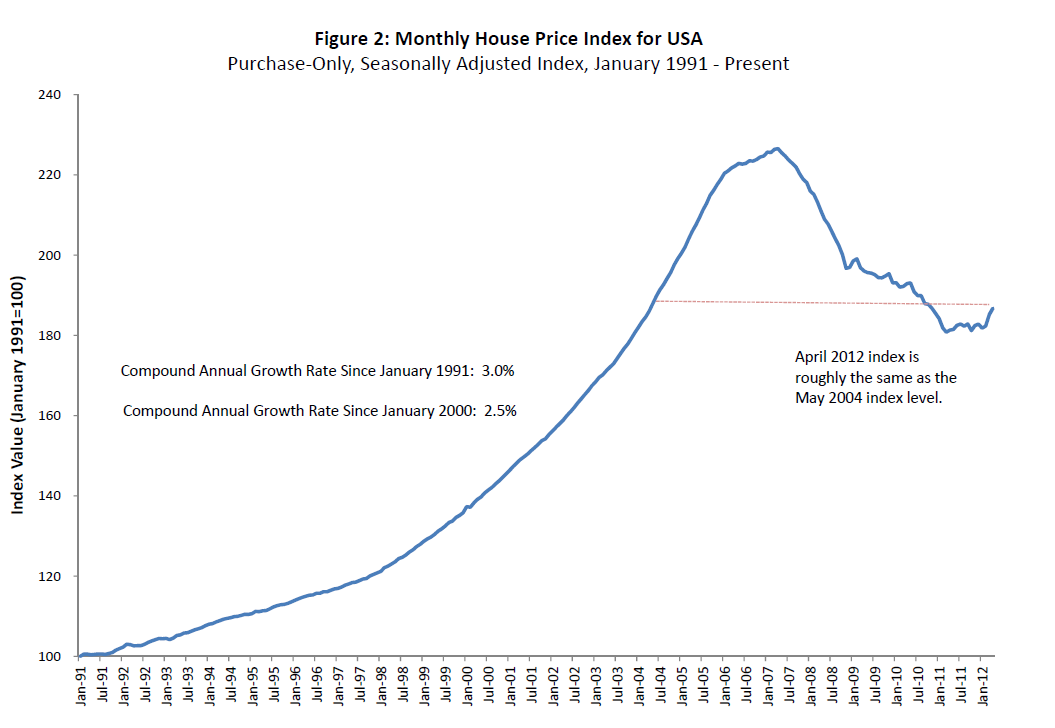
The FHFA House Price index was up .8% in April, while March was revised downward from + 1.8% to +1.6%. The FHFA House Price Index only considers Fannie and Freddie loans, so it acts as somewhat of a “center tendency” of the market, ignoring the high price and low price extremes. It certainly appears like the trend has shifted. See chart below:
Software Provider Ellie Mae released its May Origination Insight Report which provides data on mortgages originated though its Encompass system. The typical closed loan had a FICO of 744, a LTV of 81, and a DTI score of 24/35. A typical denied application had a FICO of 702, a LTV of 88, and a DTI of 28/43. The mix of refis vs purchase dropped to 54/46 from 56/44 in April and 61/39 in March, which is surprising given the drop in mortgage rates over the past 3 months. Closing times continue to increase, with the time to close up to 46 days from 42 in March. Overall, it shows a tight mortgage market with great rates for those who qualify.
On opposite ends of the economic spectrum, Octomom is getting foreclosed upon, while Larry Ellison is buying a Hawaiian Island.
Filed under: Morning Report | 111 Comments »
Vital Statistics:
| Last | Change | Percent | |
| S&P Futures | 1352.0 | 1.4 | 0.10% |
| Eurostoxx Index | 2198.5 | 0.5 | 0.02% |
| Oil (WTI) | 84.09 | 0.1 | 0.07% |
| LIBOR | 0.468 | 0.000 | -0.05% |
| US Dollar Index (DXY) | 81.24 | -0.142 | -0.17% |
| 10 Year Govt Bond Yield | 1.64% | 0.02% | |
| RPX Composite Real Estate Index | 180.5 | 0.2 |
Markets are slightly firmer as Antonis Samaras looks to be sworn in as premier of the new coalition government in Greece. This is taking pressure off of Italian and Spanish borrowing rates as well. As we approach the end of the quarter, we begin preannouncement season, where companies that are going to miss their quarterly estimates fess up. Today’s victim: Proctor and Gamble which is lowering its revenue and profit outlook on European weakness. The earnings season officially kicks off in a couple of weeks with Alcoa announcing on July 9.
Other than Greece, markets will focus on the FOMC announcement later today, particularly with respect to Operation Twist, which is scheduled to end soon. There has been speculation that the Fed would continue Operation Twist, perhaps by buying mortgage backed securities directly instead of the 10-year. Don’t forget we have gotten 73 basis points worth of stimulation in the last 3 months courtesy of Europe, while mortgage rates have not participated fully. That said, since the 10-year bottomed at 1.45% in early June, the underperformance has been correcting. See chart below:

The Fed is conducting Operation Twist because it wants mortgage rates down, not because it thinks the 10-year bond is too expensive. So the Fed will undoubtedly be focusing on the spread between mortgage rates and Treasuries as well as the overall level of interest rates.
In its June Economic Outlook, Freddie Mac notes the strength in the rental market as vacancy rates fall. This is driving construction activity and Freddie estimates that multi-fam construction will add 200,000 units this year, the most since 2008. A drop in the homeownership rate is driving this demand as well as the high downpayments required for new homebuyers. Between the historically low housing starts of the last ten years (never mind population growth), the low household formation (as new grads move back in with Mom and Dad), and historic affordability we are creating pent up demand for housing that will be released into the market once the economy picks up some steam.
Filed under: Morning Report | 81 Comments »
Vital Statistics:
| Last | Change | Percent | ||
| SPU2 Comdty | S&P Futures | 1332.5 | -5.0 | -0.37% |
| SX5E Index | Eurostoxx Index | 2166.7 | -14.5 | -0.66% |
| CL1 Comdty | Oil (WTI) | 82.89 | -1.1 | -1.36% |
| US0003M Index | LIBOR | 0.468 | 0.000 | 0.00% |
| DXY Index | US Dollar Index (DXY) | 81.79 | 0.164 | 0.20% |
| USGG10YR Index | 10 Year Govt Bond Yield | 1.57% | -0.01% | |
| RPX.CP28 Index | RPX Composite Real Estate Index | 180 | 0.3 |
Markets are slightly higher as we await the FOMC meeting on Wed. Overseas, Spain sold 3.04 billion euros worth of bills, higher than its 3 billion target. Euro sovereign yields are lower across the board, while US Treasury yields are flattish. MBS are flat. As we head into the end of the quarter, we will start to hear from companies who are going to miss earnings estimates.
Housing starts came in at a seasonally adjusted annual rate of 708k. This was below April, but was 29% over May 2011’s rate. Building Permits, which is a leading indicator for starts came in at 780k. Overall, it shows the housing market is on the mend, although new construction activity is focusing more on multi-family as opposed to single units. Housing’s contribution to GDP growth is back to slightly positive, and it is still well, well below historical averages.
Interestingly, the average housing start number for the past 10 years has been a 1.3 million annual rate. The average annual rate from 1959 – mid 2002 was around 1.5 million / year. Pre-crisis, housing formation numbers had been running at around 1.2 million / year. This certainly helps explain the nascent demand in multi-fam construction as those people have to live somewhere, but it also suggests that a lot of the overbuilding from the bubble has been worked off.
Chart: Housing starts 1959-Present

Filed under: Morning Report | 20 Comments »
Vital Statistics:
| Last | Change | Percent | |
| S&P Futures | 1332.5 | -5.0 | -0.37% |
| Eurostoxx Index | 2166.7 | -14.5 | -0.66% |
| Oil (WTI) | 82.89 | -1.1 | -1.36% |
| LIBOR | 0.468 | 0.000 | 0.00% |
| US Dollar Index (DXY) | 81.79 | 0.164 | 0.20% |
| 10 Year Govt Bond Yield | 1.57% | -0.01% | |
| RPX Composite Real Estate Index | 180 | 0.3 |
Markets are weaker this morning on a rise in Spanish bond yields, which are 34 basis points higher to 7.22%. Over the weekend, the pro-bailout parties won in Greece, and their bond yields are a percentage point lower. US bonds are up half a point, and MBS are up slightly as well.
Lots of economic data this week regarding housing, with NAHB today, Housing Starts tomorrow, the FOMC on Wed, and existing home sales on Friday. The NAHB index came in at 29, the highest level since May of 2007, as low rates and low prices are creating demand for home builders. Regionally, the West and the Midwest gained, while the Northeast and the South declined.
Home equity in Q1 rose to $6.7 trillion, the highest level since 2008 as borrowers refi their mortgages and often bring cash to the table to pay down principal. In addition, many borrowers are shortening the terms of their loans. This shows part of the problem with the economy right now, as consumers save (by paying down debt). This will be good for the economy long-term, although it is a headwind now.
In another positive data point for the housing market, we have a bidding war for Rescap, GMAC’s bankrupt housing unit between Fortress and Warren Buffet. For Buffet, there a synergies between Berkadia’s servicing operations, and its Clayton manufactured housing unit.
Filed under: Morning Report | 29 Comments »
Vital Statistics:
| Last | Change | Percent | |
| S&P Futures | 1327.5 | 1.3 | 0.10% |
| Eurostoxx Index | 2179.6 | 31.4 | 1.46% |
| Oil (WTI) | 84.02 | 0.1 | 0.13% |
| LIBOR | 0.468 | 0.000 | 0.00% |
| US Dollar Index (DXY) | 81.91 | -0.078 | -0.10% |
| 10 Year Govt Bond Yield | 1.59% | -0.05% | |
| RPX Composite Real Estate Index | 179.8 | 0.3 |
Markets are slightly better on speculation of further stimulus measures out of the world’s central banks. We are seeing a tightening across the board with Euro sovereigns, particularly Greece. The US 10-year is yield is lower as well, with MBS up a few ticks. Today is Triple Witching, with the expiration of options and futures.
The Empire State Manufacturing Survey came in well below expectations, and dropped precipitously from May’s number based on a steep drop in shipments. Overall, the report suggests that business activity is still expanding (slightly) but optimism is waning. Separately, capacity utilization fell from 79.2% to 79% and industrial production fell .1%.
Harvard’s Joint Center for Housing Studies released their State of the Nation’s Housing Market Survey yesterday. Punch line: The housing market appears to have turned the corner, however further economic weakness could stall it again. They note that housing construction is finally a positive contributor to GDP. They also include a chart showing that the relative attractiveness of owning vs renting is as high as it has been since the early 70’s:

As if we didn’t have enough to worry about on the horizon, an ex-Soros advisor warns us about Japan, where he envisions a Japanese government bond default by 2017. The IMF is forecasting the Japanese debt to GDP ratio will increase to 245% by 2014. “The yen and the JGB market are in a bubble,” Fujimaki said. “With the gigantic debt Japan has accumulated, a thin needle, or even a gentle breeze may pop this. Events in Europe can possibly trigger this to blow up.” While some people bemoan that we are potentially following the European track, Japan is the final stop on the track they propose.
Filed under: Morning Report | 35 Comments »
Vital Statistics:
| Last | Change | Percent | |
| S&P Futures | 1306.1 | -2.7 | -0.21% |
| Eurostoxx Index | 2134.4 | -9.1 | -0.42% |
| Oil (WTI) | 82.42 | -0.2 | -0.24% |
| LIBOR | 0.468 | 0.000 | 0.00% |
| US Dollar Index (DXY) | 82.17 | 0.107 | 0.13% |
| 10 Year Govt Bond Yield | 1.59% | 0.00% | |
| RPX Composite Real Estate Index | 179.5 | 0.4 |
Markets are weaker after Moody’s downgraded Spain to one notch over junk and initial jobless claims came in higher than expected. The chart suggests that the trend in initial jobless claims may be changing. The CPI remained muted. Bonds and MBS are slightly lower.
FHFA released its annual report to Congress on the state of the GSEs. The average 2011 mortgage in their portfolio is very high quality – Average LTV < 70%, Average FICO in the mid 70s. The worst stuff (the no-doc and IO loans are finally gone). FHFA characterizes the GSEs as “stabilized” but not “sound.” Fannie and Fred guarantee roughly $100 billion per month and account for 75% of every mortgage originated in 2011. They owe Treasury $187.5 billion.
The NAHB has listed 80 metro areas in their Improving Market Index for June. To be included in the index, the are must have shown improvements in housing permits, employment, and house prices for at least six consecutive months. This is a drop from May where 100 areas were in the index. Map.
The consensus seems to be that Jamie Dimon did well yesterday, by showing contrition where necessary, yet pushing back when he had to as well. The business press seems to believe the Senators went too easy on Dimon.
In keeping with the “where is the inventory” thread I have been discussing the past few days, here is another: Private Equity has raised more than $6 billion to buy and rent foreclosed homes, yet have only deployed about $2 billion of it. Analysts are concerned that political pressure out of Washington is delaying the bulk sales. Maybe someone in Washington wants to goose the housing indices a little bit. He may end up being too clever by half – when the ducks are quacking, you gotta feed them or they go away…
Chart: Initial Jobless Claims:

Filed under: Morning Report | 11 Comments »
Vital Statistics:
|
Last |
Change |
Percent |
|
|
S&P Futures |
1303.7 |
3.4 |
0.26% |
|
Eurostoxx Index |
2145.2 |
7.5 |
0.35% |
|
Oil (WTI) |
82.29 |
-0.4 |
-0.50% |
|
LIBOR |
0.468 |
0.000 |
0.00% |
|
US Dollar Index (DXY) |
82.53 |
0.013 |
0.02% |
|
10 Year Govt Bond Yield |
1.61% |
0.02% |
|
|
RPX Composite Real Estate Index |
178.9 |
0.2 |
|
Markets are a touch higher this morning after yesterday’s sell-off. Federal Reserve Bank of Chicago President Charles Evans (who Jim Bianco called an uber-dove) said he supports more stimulus. The 10-year yield is back up to 1.61% and MBS are down about 1/4 of a point.
The National Federation of Independent Business Optimism Index ticked down in May. It came in at 94.4, vs 94.5 in the previous month, which is a historically low level. 51% of owners hired or tried to hire in the last three months and nearly 3/4 of those reported few or no qualified applicants for positions. The report has a pretty scathing indictment of Washington, with 22% of the respondents indicating taxes as the single most important problem. 20% reported poor sales, and 19% reported government red tape.
Excerpt from the report: “The Index did not go down by much, that’s the good news. The May reading is still at recession levels from an historical perspective, consistent with very anemic Gross Domestic Product (GDP) and employment growth. The calculus of spending decisions requires an estimate of future sales, tax rates, interest rates and credit availability, labor costs, health care costs, regulatory compliance costs, all of which are very uncertain, meaning that owners cannot make reliable estimates of what will happen to these factors. Most of this uncertainty is coming out of Washington, D.C. Owners can’t attach probabilities to outcomes or even decide which outcomes to consider.
The amount of political manipulation and evasion to guide the spending of billions of taxpayer dollars is disturbing to owners. Sixty (60) percent of those surveyed said now is a bad time to expand their businesses; one-in four of those owners cited political uncertainty as the main reason, second only to concerns about a weak economy. Investing in jobs or plant and equipment will remain at “maintenance” level until this is resolved.”
I would be surprised if this doesn’t become campaign fodder.
A study from the Federal Reserve regarding changes in US family finances has been getting a lot of discussion – the median net worth of families has dropped nearly 40% from 2007 to 2010, putting them back where they were in 1992. Most of this is housing-driven, though stocks, student loans, and a drop in incomes are playing a part too. A generation’s worth of wealth creation has been destroyed in 3 years. Of course much of that wealth was illusory, but it does speak to why confidence has been so lousy – the reverse wealth effect. Hopefully housing is in fact bottoming, which will reverse this effect.
The WSJ addresses in interesting question: if the shadow inventory is so high, why is the inventory of homes actually for sale at normal levels? It turns out (unsurprisingly) that negative equity is the reason, but also the influx of professional investors scooping up inventory in the hardest-hit areas. It also explains why prices are rising the most at the bottom end of the market – they have the most negative equity, so supply is the most constrained.
Chart: NFIB Small Business Optimism Index:

Filed under: Morning Report | 50 Comments »
Vital Statistics:
| Last | Change | Percent | |
| S&P Futures | 1328.3 | 6.3 | 0.48% |
| Eurostoxx Index | 2169.7 | 25.8 | 1.20% |
| Oil (WTI) | 85.09 | 1.0 | 1.18% |
| LIBOR | 0.468 | 0.000 | 0.00% |
| US Dollar Index (DXY) | 82.28 | -0.229 | -0.28% |
| 10 Year Govt Bond Yield | 1.63% | 0.00% | |
| RPX Composite Real Estate Index | 178.7 | 0.0 |
Markets are up this morning on a potential bail out for the Spanish banks, although the initial euphoria is wearing off. When I checked in last night, the S&P futures were up 16 points. Now they are up 6. During the US financial crisis, the one sure-fire trade was to fade any rally brought on by some sort of government rescue. The S&P futures would spike up on news that the government was intervening somewhere, and then would sell off as people realize the intervention is no panacea. US bonds clearly aren’t buying it, with the 10 year unch’d. MBS are flat as well.
While equity markets have rallied on the Spanish bailout, Spanish bond yields have not. After trading up to 6%, Spanish government yields are now over 6.4%. As Bill Gross has noted, the Spanish bond market is rigged, as the Spanish banks are encouraged to buy up debt auctions to make the demand for Spanish debt look better than it really is.
Are we there yet? That is the title of CoreLogic’s June MarketPulse report on housing. While noting that previous seasonal strength in 2010 and 2011 ended up fading into year-end, CoreLogic postulates that the green shoots we are seeing indicate the market has turned for good. The caveat: housing won’t really turn until the job market is fixed.
Filed under: Morning Report | 14 Comments »

