Morning Report: Retail Sales improve 11/15/16

Vital Statistics:

Last Change
S&P Futures 2165.0 5.0
Eurostoxx Index 338.3 0.1
Oil (WTI) 44.6 1.3
US dollar index 90.5 0.0
10 Year Govt Bond Yield 2.22%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 3.89

Stocks are up modestly this morning on no real news. The bond bears are taking a break today, everywhere except Japan, where the JGB 10 year yield is now positive.

You can see just how dramatic the sell-off in the 10 year has become. Note the big drop in yields as the election was called for Donald Trump, and then the huge reversal. That is the mother of all head fakes. Carl Icahn was buying about a billion dollars worth of S&P 500 futures contracts during that head fake.
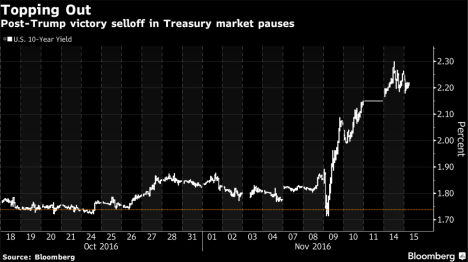
10-year

Retail Sales came in stronger than expected in October, rising 0.8%. Ex-autos and gas, they rose 0.6%. The October readings are in that sort of trough period between back to school and the holidays. BTS sales were on the weak side, FWIW so I am not sure what this necessarily means for holiday sales. Stocks seem to like it, with the S&P SPDR retailer ETF (XRT) up a couple of percent pre-open.

More stirrings of inflation? Import Prices rose 0.5% in October, higher than expected. The headline number is even more surprising given that the dollar rose during the month, however the increase was pretty much concentrated in the petroleum sector. Export prices fell.

The Empire State Manufacturing Survey increased modestly in November, climbing out of negative territory for the first time in 4 months. New York State remains in a bit of a funk compared to the rest of the US. The employment indices fell.

More good news for housing: The Despot reported better than expected earnings this morning as people spend more on home improvement.

Is the firing spree finally over in the financial sector? It could be. Since 2005, approximately 800,000 jobs have been shed in the sector. About the only demand came in compliance.

People have been saying for a while that auto loans are the new subprime. It looks like the next subprime is online consumer loans, which were supposed to disrupt the banking industry, but are taking way more credit losses than anticipated. Technology is all fine and good, but if you can’t analyze credit risk properly, you aren’t going to make it.

Head of the SEC Mary Jo White submitted her resignation, which clears the way for a more pro-free market head of the regulatory body.

The jump in rates has been bad news for many in the mortgage business, as it weighs down the refi shops. VA IRRRLs have been a gravy train for many shops and that party looks to be winding down between higher rates and new rules on securitization. Certainly this isn’t great news for the first time homebuyer, however if the employment market continues to improve, that should offset the increase in rates. It will almost certainly mean that further home price appreciation will be harder to come by, as the affordability gift of low rates goes away. Does that necessarily mean the refi market is dead? Cash-out refis where borrowers can refinance their credit card debt will still make a ton of sense, even if mortgage rates top 4%. We may see an increase in ARM demand as a way to lower payments, but with the Fed in a tightening cycle, that is a risky way to go.

Morning Report: Potential Dodd-Frank reform 11/14/16

Vital Statistics:

Last Change
S&P Futures 2164.5 3.0
Eurostoxx Index 338.2 0.7
Oil (WTI) 42.7 -0.7
US dollar index 90.2 0.5
10 Year Govt Bond Yield 2.20%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 3.89

Stocks are up modestly this morning on no real news. Bonds and MBS are up again.

No economic data this morning, but we will have some Fed-speak in the afternoon.

About $1.2 trillion in wealth was wiped out in the bond market last week as yields soared in response to the Trump victory. The yield on Treasuries increased by 37 basis points last week. Bonds are reacting to (a) the potential inflation from a big infrastructure spending program, and (b) the potential for reduced trade and increased protectionism. Yields are now at highs we haven’t seen since January.

Richmond Fed President Jeff Lacker said that if Trump enacts a large fiscal stimulus plan, it might cause the Fed to move faster than the markets anticipate. Lacker will be a voting member in 2018.

One of the first jobs the new administration will tackle is to reform Dodd-Frank. The biggest piece of that will be to reform the CFPB, by making it subject to the Congressional appropriation process and to replace a single director with a bipartisan board. Banking stocks have been rallying since the election. Other rules would center around capital requirements and stress tests, which would mainly affect the smaller banks that don’t have massive derivatives portfolios or international operations, in an attempt to ease the regulatory burden on them. Democrats might attempt to filibuster any reform if it goes too far, but there probably is enough common ground in the Senate to make some sort of reform possible.

Could Donald Trump end up facing the nemesis of Bill Clinton’s first administration – the bond vigilante? Certainly if you take his promises at face value: a big uptick in spending with a massive tax cut, then you might see the creature that has been in hibernation since the early 90s resurface.

Morning Report: Will the late teens resemble the early 80s? 11/10/16

Vital Statistics:

Last Change
S&P Futures 2167.5 7.0
Eurostoxx Index 340.7 0.9
Oil (WTI) 44.9 -0.3
US dollar index 89.3 0.4
10 Year Govt Bond Yield 2.09%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 3.75

Stocks are higher this morning as the markets come to grips with a Trump presidency. Bonds and MBS are down.

Strangely, the 2 year bond is trading at 90 basis points, while the consensus is that we should be getting 2 more rate hikes by late 2018. This is even more surprising given the action in the 10 year. A poll of economists and strategists indicates that the Fed will still raise rates in December. Given the market action since Trump won, the Fed has every excuse to do so.

Trump will not ask for Janet Yellen’s resignation. That said, she probably won’t get re-nominated when her term expires in 2018. Donald Trump has been critical of Fed policy, insisting that rates should be higher than where they are now.

After an appeals court ruling, President Trump could fire CFPB Director Richard Cordray.

Mortgage Applications fell 1.2% last week as purchases rose 1% and refis fell 3%. The average interest rate for a 30 year fixed conforming mortgage rose 2 basis points to 3.77%.

Initial Jobless Claims fell to 254k last week as employers continue to hang onto their workers.

The conventional wisdom that a Trump victory would be stock bearish, bond bullish, and dollar bearish turned out to be dead wrong, at least initially. Stocks were destroyed in the wee hours of Wednesday morning, and then had a massive turnaround during the day. Legendary investor Carl Icahn probably singlehandedly cleaned up the sellers overnight, pouring $1 billion into S&P 500 futures. He was probably up about 6% on that trade by noon.

The overall feel to the tape is “risk on” and investors are definitely selling bonds to buy stocks. Financials, Pharma, and construction stocks led the charge. Surprisingly the homebuilder ETF (XHB) underperformed. Ultimately a Trump presidency should be bullish for housing, so I am surprised at the stock action.

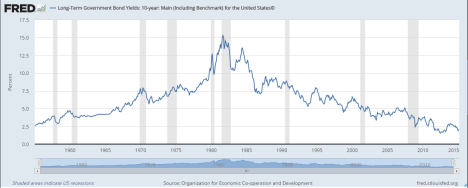
The more I think about it, the more I believe the Trump presidency will most closely resemble the early Reagan Administration economically. Reagan took over after a long period of economic underperformance and shocks to the economy. Early in his administration, the Fed was tightening while fiscal policy loosened. I think that dynamic is going to play out here, as the government cuts taxes, deregulates, and spends on infrastructure while the Fed methodically raises interest rates off the zero bound. Ultimately the Fed has an easier job here, as they don’t have the raging inflation problem and any recession will probably be more mild since we are already at full employment. I don’t see a deep recession like 81-82 in the cards, however we are certainly in uncharted territory with monetary policy worldwide. The biggest difference is that that the early 80s ended a secular bear market in bonds that began in the 50s. This time around, we are ending a secular bull market in bonds that started in the early 80s. Note that we are also probably at the beginning of a secular bull market in stocks, just like the early 80s.

10 year long term.PNG

Morning Report: The unthinkable just happened 11/9/16

Vital Statistics:

Last Change
S&P Futures 2134.5 -4.0
Eurostoxx Index 333.0 -2.0
Oil (WTI) 44.8 -0.2
US dollar index 88.3 0.3
10 Year Govt Bond Yield 1.96%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 3.61

Stocks are bonds are down after Republicans ran the table last night. Volatility will be the rule of the day.

Republicans ran the table. House, Senate, and Presidency. Obviously the conventional wisdom was dead wrong.

Bonds are down surprisingly, given how they were behaving in the early Asian sessions. As a Trump victory was looking more and more likely, bond yields were falling (having hit a low of 1.72% at one point). Just after midnight, the rally reversed, and bonds sold off to where yields hit 1.96%. Interestingly, the 2 year has rallied to 71 basis points or so and has now sold off to 83 bps. So people got whipsawed big time overnight, which means we should expect some volatility in rates going forward. Volatility tends to beget volatility. Be careful with your locks.

Stocks were initially slammed on the result as well, with the S&P 500 futures down over 120 points. That has since turned around and we are looking at modest losses. Just another day at the office for the markets.

Obviously, no one saw this coming, and a lot of people are wondering what a Trump presidency means to markets. First of all, I think fears that Ted Nugent would be running Homeland Security and Jesse the Body Ventura would be running Treasury are overblown. A lot of the serious candidates who would be good choices were not in the mix for consideration because they didn’t take Trump’s candidacy seriously. That will now change, however I think we will probably see a few outsiders: guys like ex-GE CEO Jack Welch, KKR head Henry Kravis, or Carl Icahn. VP Mike Pence will have a much bigger role than a traditional VP.

Trump’s model would be Ronald Reagan, which was probably the best comparison. Reagan was scoffed at by the elites: he was an actor, went to *snicker* Eureka College, was from the land of fruits and nuts, however he beat the brainiac Jimmy Carter who the establishment liked a lot. Reagan however surrounded himself with the best of the best and brightest of the conservative movement and became a successful president. Reagan was not a detail guy either. For Trump, it all comes down to his personnel who will handle the heavy lifting while Trump points in the general direction where he wants things to go. He doesn’t have the knowledge base to get all that involved in the nitty-gritty of policy-making. All of that said, the people who worry that he is Benito Mussolini II (actually I think the better comparison is Silvio Berlusconi) forget that people change, but the US system of government doesn’t. It was designed specifically to make it impossible for a dictator to make it work. He is going to be way more restricted in what he can actually do than the left fears.

I would suspect this morning a lot of market pros are googling Donald Trump’s economic policy. He has generally been all over the place. I think he will be more financial sector friendly than Obama was. He has trashed Dodd-Frank a number of times, and I suspect that D-F will get tweaked legislatively, with the goal of providing market participants more certainty into what the rules of the road are. Provided he does this right, it could help bring back the private label securitization market, which has been largely dormant with the exception of highly overcollateralized jumbo securities. Given the thin ice that the CFPB is on Constitutionally (and now a conservative replacement for Scalia on the Supreme Court), the agency might be pulled back onto the reservation.

Trump has been all over the board with respect to tax policy. He once advocated for a wealth tax, which even FDR couldn’t stomach. Now, he wants to eliminate the estate tax, cut corporate taxes and flatten the income tax code. Corporate tax reform is ripe as both parties agree we need to do something. Carried Interest could probably go by the wayside as a bargaining chip with the left.

Donald Trump has also been critical of the Fed, and he probably will nominate a more hawkish Chair than Janet Yellen, however her term expires in late 2018 so this isn’t a front-burner issue. The action in the 2 year suggests the markets are handicapping a lower chance of a hike at the December meeting. IMO, the Fed will do what it usually does: take a cue from the behavior of the markets.

Here is what Trump might do for housing finance reform. Punch line: Housing finance reform simply isn’t going to be a front-burner issue. It wasn’t really discussed by either party during the campaign, and the current system might not be ideal, but at least it isn’t a problem.

With respect to foreign policy, remember that Barack Obama ran as the ant-GWB. He would end the wars in the Middle East, close Guantanamo Bay, and build on our alliances in Europe. After all was said and done, he pretty much continued to do what GWB was doing. Trump will have the same constraints, especially in trade.

Morning Report: Home purchase sentiment slips 11/8/16

Vital Statistics:

Last Change
S&P Futures 2123.5 -6.0
Eurostoxx Index 333.4 -0.4
Oil (WTI) 44.7 -0.2
US dollar index 88.1 0.1
10 Year Govt Bond Yield 1.82%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 3.61

Markets are flattish as Americans head to the polls. Bonds and MBS are flat.

The NFIB Small Business Optimism index improved in October, however it remains below historical norms. Labor markets remain tight: 55% of all respondents tried to hire in the past month, and 48% reported few or no qualified candidates. A net 25% of all respondents reported increasing employee compensation. A net 19% plan to increase wages over the next six months, which is among the strongest post-recession numbers. Earnings trends are negative, however which means companies are unable to pass along cost increases to customers, at least not yet. Overall, a net 7% of all respondents expect the economy to worsen over the next 6 months.

Job openings were little changed in September, according to the BLS’s JOLTS jobs report. JOb openings were at 5.5 million, while separations were 4.9 million. The quits rate was unchanged, while layoffs decreased. The quits rate is the best indicator for wage growth going forward.

There were 36,000 completed foreclosures in September, according to CoreLogic. The current foreclosure inventory is about 340,000 homes, which is down 31% from a year ago and represents about 0.9% of all homes with a mortgage. The seriously delinquent rate fell to 2.6% which is the lowest since late 2007. Foreclosures remain concentrated in the judicial states.

Fannie Mae’s Home Purchase Sentiment Index slipped in October to 81.7 from 82.8 the month before. Sentiment about the direction of home prices over the next 12 months slipped to a net 31% of bullish respondents from 34% in September. The most surprising statistic out of this survey was the decline in the number of people who say their net income is significantly higher: A net 4% said it was significantly higher versus 12% a month ago. Not sure what is happening there, and it doesn’t comport with some of the other labor indicators we have been seeing, but there it is. Overall, respondents think the economy is on the wrong track by a wide margin: 56% to 36%.

Dodd-Frank and the Volcker rule have reduced the market-making functions of banks. Historically, when a large customer like a mutual fund would want to sell a large order of Treasuries, they would call up someone like J.P. Morgan, who would buy the bonds and then try and sell them to their customers. The specialist on the floor of the NYSE did something similar. If a big buyer (or seller) came in for Apple stock and created an imbalance, the specialist would send out an imbalance notification to the newswires in hopes of attracting investors to take the other side. This had the effect of taking volatility out of the market. That function doesn’t really exist anymore, and the net result will be more volatility. It won’t matter until the next crash, and many investors who call their brokers asking to sell will find a no-bid market. Know where this could get particularly ugly? Munis.

Morning Report: Mortgage credit eased in October 11/7/16

Vital Statistics:

Last Change
S&P Futures 25109.8 30.0
Eurostoxx Index 333.4 4.0
Oil (WTI) 44.5 0.5
US dollar index 88.0 0.4
10 Year Govt Bond Yield 1.82%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 3.61

Stocks are higher this morning after the FBI absolved Hillary Clinton of her email woes. Bonds and MBS are down.

Tomorrow we will go to the polls to vote in our fearless leader. Here is a cheat sheet for how markets should react based on the consensus of strategists. Punch line: Trump is negative for stocks, and positive for bonds. Hillary is the opposite. The effect will be only short-term as well. That said, IMO the black swan event is a D sweep.

Meanwhile, the fast money is hiding in gold.

Consumer spending increased in October, according to Gallup. A poll of consumers indicated that they spent on average $93 a day in October from $91 in September.

Credit eased somewhat in October, according to the MBA’s Mortgage Credit Availability Index. The jumbo end of the market drove the increase. Since the depths of the real estate bust, mortgage credit has increased tremendously, however compared to the bubble days it is extremely tight.

The labor market improved in October, according to the Labor Market Conditions Index. It rose to 0.7 from -0.2 in September. The LMCI is a composite index of various leading and lagging labor market indices, so it shouldn’t have much of an effect on markets.

55+ housing had a strong 3rd quarter, according to the NAHB.

Realtors have a huge influence of a borrower’s lender decision, according to a new survey out of Freddie Mac. The biggest factors are ease of doing business, reputation and the strength of their relationship with the realtor. From the article: “Eighty-four percent of real estate professionals have a select group of lenders to which they generally refer their clients. Of these, 73 percent have 1-3 lenders in their network and 24 percent work with 4-6 lenders. More than three-quarters (76 percent) say their clients always or often use their recommended lender referrals. This figure climbs to 87 percent among those who sell more than 20 properties per year.”

Morning Report: Decent jobs report 11/4/16

Vital Statistics:

Last Change
S&P Futures 2085.7 2.0
Eurostoxx Index 328.9 -2.6
Oil (WTI) 44.1 -0.6
US dollar index 87.7 0.0
10 Year Govt Bond Yield 1.79%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 3.61

Stocks are higher after a decent jobs report. Bonds and MBS are up as well.

Jobs report data dump:

  • Payrolls increased by 161,000
  • Unemployment rate 4.9%
  • Labor Force Participation rate 62.8%
  • Average hourly earnings 0.4%

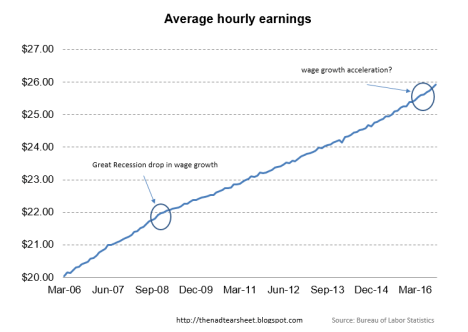
The payroll data was disappointing, as was the decrease in the labor force participation rate. The plus side was wage growth, where wages rose at a 2.8% annual rate, the biggest increase since 2009. The employment to population ratio slipped to 59.7%. Basically, it looks like the number of unemployed fell, however they didn’t get jobs – they exited the labor force. Below is a chart of average hourly earnings. You can see the slope of the line decrease in 2008 as the Great Recession began and wage growth slipped from its bubble year growth rate of 3.3% to 2%, where it largely stayed during the recovery. It appears like the slope of the line is beginning to increase, which solves a lot of problems in our economy. Too early to tell if it is a trend, though. Bottom line: This gives the Fed all the ammo they need to raise the Fed Funds rate next month. FWIW, the Fed Funds futures are now assigning a 80% chance of a 25 basis point hike next month.

hourly-earnings

Ordinarily, this report would be bond bearish, however global sovereigns are rallying and pulling the 10 year along for the ride.

Ex Dallas Fed Head Richard Fisher blames the rise of Donald Trump partially on Fed policy. The Fed’s policy of driving interest rates to the floor and flooding the system with money to support asset prices is great news for people who own real estate and stocks, however for those that save it has been terrible:

“Global monetary policy has “skewered the middle-income groups, the ‘middle class,’ adding to the angst that has sprung from their sense of an overbearing, intrusive central government….Small wonder that we have ended up at a political crossroad, with a choice for the presidency between a candidate who advocates having government distribute still more to ease the pain and another arguing to provide relief by changing gears entirely, though we know not how, when or where…My more acerbic friends on both sides of the aisle consider it a Hobson’s choice,” he said, referring to a situation where it seems there’s free choice but in reality there’s no good alternative. On the one hand, Republicans believe the other party’s candidate is channeling Eva Peron, planning policies that will ultimately lead us down the Argentine path to economic ruin while basking in personal profit and glory. On the other, Democrats liken the Republican candidate to Caligula.”

On the subject of QE, he is spot-on. QE and unconventional monetary policy has certainly increased inequality, and made life tough if you are a renter. Rental inflation is increasing at a 4% annual clip, and as we saw above, wages are well below that. QE has been great for the landlord, but not the tenant. I find it amazing that the Fed gets a free pass in the media and from the political class on the subject of inequality.

For all the sturm and drang regarding how markets will react to a Trump presidency, bond traders appear to be relatively sanguine. Just like stocks have the VIX index which measures fear indirectly by tracking the price of options, bonds have an index too. And it is close to yearly lows.

Morning Report: The Fed stands pat 11/3/16

Vital Statistics:

Last Change
S&P Futures 2096.8 5.0
Eurostoxx Index 333.8 0.7
Oil (WTI) 45.5 0.1
US dollar index 87.8 0.0
10 Year Govt Bond Yield 1.82%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.64

Stocks are mixed this morning after the Fed maintained interest rates. Bonds and MBS are down.

The Fed maintained interest rates at current levels yesterday. The meat of the statement: The labor market continues to strengthen, household spending is improving while business spending remains a weak spot. Inflation is ticking up but remains below the target rate. Esther George and Loretta Mester dissented, wanting to hike at this meeting. Bonds rallied maybe a basis point on the statement.

This morning the Bank of England said that it doesn’t plan on cutting interest rates this year, which is causing a global sell-off in sovereign debt.

Announced job cuts fell 31% to 30,740 according to outplacement firm Challenger Gray and Christmas. This report looks at press announcements of job cuts, which may or may not ever materialize. Regardless, it does make the case that companies are holding onto their workers. In fact, this was the lowest October since 1999. Job cuts were most in the computer industry (largely related to HP), while cuts in the energy patch are slowing down considerably from earlier this year.

Initial Jobless Claims ticked up to 265k last week, which is still an extraordinarily low number. Separately, the Bloomberg Consumer Comfort Index ticked up.

The ISM Non-Manufacturing Index dropped to 54.8 from 57.1 in September. This means the service economy is growing, however growth is decelerating. Transportation and Construction is leading the charge, while mining and educational services are lagging.

Productivity broke out of its long slump with a 3.1% increase in the third quarter. Output increased 3.4% and unit labor costs increased 0.3%. Increasing productivity is good news as it means wages can increase without generating inflationary pressures. Productivity has been disappointing ever since the economy bottomed, however.

Both Republicans and Democrats look back wistfully on the 50s and the 60s. These years were an economic glory time, where unemployment was extraordinarily low, jobs were plentiful and high paying, and a single income was sufficient to support a family. The Third Quarter of the 20th Century basically began with the end of the Korean War and concluded with the oil shocks of the early 70s. Both parties want to bring back those times. Is that realistic? Probably not. The postwar decades were an extraordinary period where the US had no international competition, and not only had to satisfy its own demand, it had to satisfy the demand of Europe and Asia. The US earned what economists call “economic rents” and they were split between organized labor and government. By the late 70s, Europe was back on its feet and both old and new competitors were emerging from Asia. These economic rents were competed away (as they inevitably are). While this was good news for consumers and stockholders, it was bad news for union workers in general. Anyone who wants to bring back the salad days of the 50s and 60s needs to come up with a plan to get Angela Merkel to invade Poland. Donald Trump’s vision of pre-free trade America won’t get you there. Neither will the left’s vision of an “smart” paternalistic regulatory state and 90%+ marginal tax rates.

Morning Report: Construction Spending Falls 11/2/16

Vital Statistics:

Last Change
S&P Futures 2102.0 -2.0
Eurostoxx Index 333.6 -2.0
Oil (WTI) 46.0 -0.6
US dollar index 88.6 0.0
10 Year Govt Bond Yield 1.82%
Current Coupon Fannie Mae TBA 103.3
Current Coupon Ginnie Mae TBA 104.2
30 Year Fixed Rate Mortgage 3.62

Stocks are mixed ahead of the FOMC decision today. Bonds and MBS are up.

At 2:00 pm we will get the FOMC rate decision. Given the sensitivity around the election, I would imagine the Fed wants to be as far in the background as possible. I would be looking for a statement that is pretty much identical to the Sep statement.

Mortgage Applications fell 1.2% last week as purchases fell 0.4% and refis fell 2%. The 30 year fixed rate mortgage increased 4 basis points.

The ADP jobs report is forecasting a lousy jobs report on Friday. Payrolls increased 147k versus the 170k expectation. The Street is looking for 178k jobs to be reported on Friday.

The Atlanta Fed has lowered its forecast for Q4 GDP to 2.3%. They were previously looking for 2.7%. They are looking for softer consumer spending and business investment.

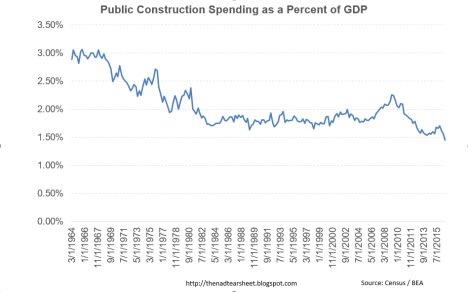
Construction spending fell 0.4% MOM and 0.2% YOY in September. Total construction spending was $1.15 trillion. Private construction fell 0.2% while public construction fell 0.9%. Residential construction was the bright spot however, as it increased 0.4%. Construction spending as a percent of GDP is still rather depressed compared to historical numbers. Yet another example of how housing continues to punch below its weight.

construction-spending

One thing that has been a partisan bone of contention has been public construction. The Obama administration has been pounding the table that we need to spend money on public construction in order to “rebuild our crumbling infrastructure” and put people to work in order to stimulate the economy. Let’s set aside the argument over whether there is a multiplier effect for government stimulus plans (there isn’t). Have we been spending on public construction (infrastructure)? Ultimately, it looks like there is merit to the argument that we have let things slide. Aside from the early Obama administration stimulus bump, it is sliding to new lows as a percentage of GDP. Note that both Hillary and Trump are in favor of a big push for public works spending. Note however that private construction is over 3x the amount of public construction. So if you want the economy to really grow, the juice is in private construction, not public construction. Unfortunately, the lack of private construction is simply not on the radar in Washington. Politicians and regulators should be asking themselves whether they are an impediment to private construction spending. The answer to that question will undoubtedly fall along partisan lines.

public-construction-of-gdp

Banks are no longer the biggest mortgage lenders in the US. Nonbanks like PennyMac and Quicken are making the loans that banks no longer want to make. We have seen the banks back away from FHA loans after being slugged too many times by the regulators. “It’s becoming the perfect storm—when you punish banks, [they] don’t lend out money,” said Paul Miller, an analyst at FBR Capital Markets. “Banks are becoming utilities that are unable or unwilling to play with risk.” Of course that is exactly the vision of the Elizabeth Warrens of the world: to turn banks into public utilities that earn a nominal rate of return and are effectively controlled by the government. The biggest worry is that if times get tough, nonbanks have less access to capital than banks which could severely restrict credit.

Morning Report: Credit explains tight inventory 11/1/16

Vital Statistics:

Last Change
S&P Futures 2124.8 5.0
Eurostoxx Index 338.3 -0.7
Oil (WTI) 47.1 0.2
US dollar index 88.3 -0.2
10 Year Govt Bond Yield 1.87%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 3.62

Stocks are higher as the FOMC begins its November meeting. Bonds and MBS are down.

The PMI Manufacturing Index improved in October to 53.4 from 51.1. We are starting to see increases in input prices be passed through to customers.

The ISM Manufacturing Index ticked up to 51.9 from 51.6.

Bonds had their worst October in 2 years as European bonds slid on bets that there will be no further stimulus out of the ECB. US bond yields are going to be naturally pulled in the direction of overseas bonds absent any info coming out of the US. If the global economy is truly out of the woods, then the path of least resistance for bonds is down, which means gradually increasing interest rates going forward. However, if the Chinese economy blows up as asset prices fall, then all bets are off.

The FOMC meeting begins today and we will get the announcement tomorrow. The markets are assuming that we will have no change in monetary policy at this meeting. The Fed Funds futures are assigning a 71% probability of a 25 basis point hike in the Fed Funds rate at the FOMC meeting in December. That said, we could see some volatility around the statement tomorrow afternoon if they deviate from the script (which probably isn’t going to happen 1 week before the election).

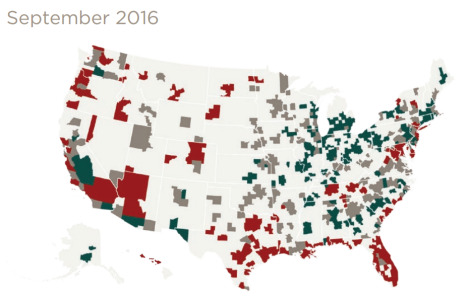
Home prices rose 1.1% MOM and 6.3% YOY according to CoreLogic. Home equity wealth has doubled over the past 5 years to $13 trillion. This works out to be about $11,000 per homeowner, however the geographic split is pretty wide. In September, CoreLogic reported that 112 markets are overvalued, with 19 of them in Texas. The heat map is shown below, where red = overvalued and green = undervalued.

corelogic-msas

Part of what is driving home prices into overvalued territory is supply, and as we know, builders are adding to inventory only grudgingly. What is going on? Ultimately credit is a big driver, but not at the residential mortgage level, it is at the bank level. There has been a huge bifurcation in credit over the past several years, where big builders like D.R. Horton or Lennar can access the bond market at very favorable rates, while the smaller builders are having trouble getting loans from their local bank. In addition, most of the lending has gone to multi-fam, not single fam. Second, lack of skilled labor and land are playing a part. The skilled labor part will fix itself on its own as high wages attract more people to the business. Land is a more difficult issue, however the price differential between the exurbs eventually will win out.

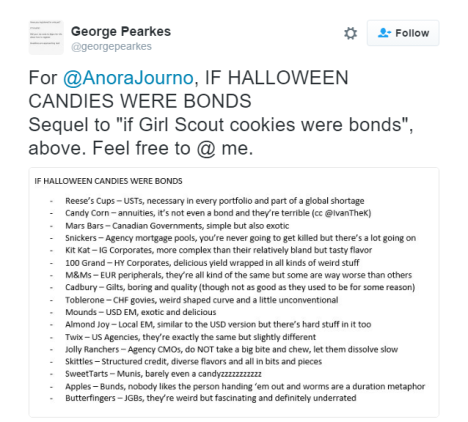
If Halloween candy were bonds:

haloween candy.PNG