Morning Report: Change in mortgage insurance was short-lived 1/23/17

Vital Statistics:

Last Change
S&P Futures 2261.8 -4.0
Eurostoxx Index 361.2 -1.4
Oil (WTI) 52.3 1.0
US dollar index 91.1 -0.5
10 Year Govt Bond Yield 2.44%
Current Coupon Fannie Mae TBA 102.1
Current Coupon Ginnie Mae TBA 103.6
30 Year Fixed Rate Mortgage 4.19

Stocks are lower this morning on no real news. Bonds and MBS are up.

We are entering the quiet period for the Fed ahead of next week’s FOMC meeting, so bonds should be less volatile as there is no Fed-speak. We also don’t have much for market-moving data this week until Friday when we get the first look at Q4 GDP and durable goods.  We will get some housing data with existing home sales, new home sales, and the FHFA House Price Index.

HUD has suspended the planned decrease in annual MIP for the moment. It was scheduled to go into effect this week, however the new Administration wants to take a look at the health of the FHFA insurance fund before making any changes. The timing of the MIP cut was suspect to begin with – if it was such a great idea, why wait until the last minute to make a change? Note that this change will positively affect FHA and VA pricing for the higher note rates.

Separately, Donald Trump put a moratorium on all new regulations for the moment. This is something every President does as agencies often try and slip some onerous stuff in at the last moment especially when the incoming Administration has large philosophical differences with the outgoing one.

Hedge funds are pressing their short speculative bets in the Treasury market. At the same time, institutional investors are aggressively buying Treasuries after the increase in yields. This is a classic “fast money versus real money” trade and usually the real money wins by dint of sheer firepower. Much will depend on what the new Trump administration does with respect to fiscal stimulus. The first priority seems to be repealing and replacing Obamacare, not infrastructure or tax reform. Every president has a limited amount of political capital, and this one seems to be spending it on healthcare, which means a tougher road forward for infrastructure spending and tax reform. The less stimulus out of Washington, the more the Fed can take their time raising rates, and the more that rates will stay low. This also sets the stage for short squeezes in the bond market, or brief periods where rates fall dramatically. Borrowers who are on the cusp with a refi could sneak in a good rate.

One thing to keep in mind with respect to interest rates is the US dollar. For the past two decades, a strong dollar has been the mantra of both Republican and Democratic administrations. Trump has made comments that the US dollar is too strong, especially with respect to the yuan. The markets seem to be taking this as “Trump being Trump” but it bears watching. A lower dollar is good for manufacturers in the US, but generally bad for consumers. It also is bad for bonds (inflationary), which means pushing up interest rates at the margin.

The Fed may begin to shrink its balance sheet this year, as the Fed Funds rate tops 1%, Philadelphia Fed President Patrick Harker said on Friday. The Fed increased its balance sheet to $4.5 trillion from about $800 billion in assets via quantitative easing, and has been re-investing maturing proceeds back into the market. At the margin, this means somewhat higher mortgage rates unless other entities like mortgage REITs and sovereign wealth funds pick up the slack.

The appraiser shortage is clogging up the system. There were 2000 fewer appraisers in 2016 versus 2015, and the average age is 53. Many are looking to retire, and the pipeline of new appraisers is shrinking. Regulatory challenges have largely caused the problem, and the industry is looking for ways to attract new blood into the industry, via waiving the degree requirement and shortening the number of apprentice hours required. The ones that remain however have so much work that they don’t have the time to train anyone.

Interesting article from John Maudlin about the state of things in DC. The takeaways: The consensus is that Dodd-Frank, Obamacare, and the tax code will be restructured, but that is about the end of the consensus. How it will be done is anyone’s guess. As time goes on, it looks like the changes in Obamacare will be marginal, not dramatic. Second, Trump’s management style is much more in the private sector style, which will mean more turnover than is typical. This will inevitably be described as “disarray” by the press, which isn’t used to seeing this sort of style.

Black Knight Financial Services has their first look at December mortgage data. The inventory of loans in some phase of foreclosure dropped by 200,000 in 2016, the best improvement of any year on record. Loan delinquencies were 4.42%, down .91% MOM and 7.5% YOY. Prepay speeds fell 5.5%.

Finally, I will be on the panel for HousingWire’s Housing Outlook 2017: Trump’s Mortgage Nation on Jan 26 at 2:00 pm EST. I will be discussing rates and the economy, and we will also delve into the regulatory environment and mortgage insurance. Registration is free and it promises to be an informative event.

Morning Report: Steve Mnuchin testifies and sinks the GSEs 1/20/17

Vital Statistics:

Last Change
S&P Futures 2267.0 5.0
Eurostoxx Index 362.7 -0.7
Oil (WTI) 52.2 0.8
US dollar index 91.9 0.1
10 Year Govt Bond Yield 2.48%
Current Coupon Fannie Mae TBA 101.2
Current Coupon Ginnie Mae TBA 103.1
30 Year Fixed Rate Mortgage 4.19

Stocks are up as we prepare for the inauguration. Bonds and MBS are down.

Should be a quiet day for bonds as there are no economic data.

Janet Yellen spoke yesterday at Stamford and stressed the Fed was not behind the curve, and we still have some slack in the labor market. However, she said it was prudent to undo some of the accomodation so that we don’t have to move too quickly later. She also said the economic outlook was clouded due to uncertainty out of Washington. While Trump can sand down the edges of the regulatory state, he has a problem legislatively with Democrats in complete opposition, and a tenuous relationship with Republicans.

A partial explanation for the weakness in the high end of the real estate market can be explained by new Chinese capital controls. The Chinese government has instituted capital control to prevent an outflow of yuan. Foreign real estate was a big beneficiary of that capital, so expect to see more weakness in the high-priced markets like San Francisco, NYC, Seattle, and Denver.

Trump Treasury Secretary nominee Steve Mnuchin testified in front of Congress yesterday, and largely escaped unscathed. He called for a reform of Fannie Mae and Freddie Mac, however he said he did not support “recap and release.” He also said that any sort of “border tax” would be targeted at companies that offshore manufacturing and then sell back into the US. The hearing got testy at times, with Sen Pat Roberts (R-KS) suggesting that Sen Ron Wyden (D-OR) take a valium. Democrats zeroed in on his role with IndyMac and purported foreclosure abuses.

Fannie Mae and Freddie Mac tumbled during the testimony, however they also lost a lawsuit that could have have explained the fall as well. Both were down 5% after being up for the day. Both stocks have more than doubled since the election on optimism that Donald Trump would support some sort of change in how the government treats these stocks. Currently, the government owns 79.9% and all profits from the company go directly to Treasury.

In terms of other takeaways from Mnuchin’s testimony, he supports bringing the CFPB into the appropriations process, would like to tweak the Volcker rule (which prohibits proprietary trading) to eliminate the negative effects it is having on market liquidity, to ease the regulatory burden on small banks, and to bring back a “21st century” Glass-Steagall law, whatever that means.

Glass Steagall was implemented during the Great Depression because investment banks were putting busted underwritings (i.e. underwritten bonds they couldn’t sell to the public) on the balance sheets of their captive commercial banks and insurance companies at par in order to hide the losses. Glass Steagall ended this practice by requiring all of these transactions to be arm’s length. Fast forward to 2007, the crisis wasn’t caused by JP Morgan the investment bank stuffing bad paper on Chase the commercial bank’s balance sheet. For what its worth, the US is the only country on the planet that separates investment banking and commercial banking, or even draws a distinction between the two. Everywhere else, it is just called “banking.” Indeed, the reason Glass-Steagall was repealed in the first place was that reason: Wall Street investment banks like Morgan Stanley and Goldman couldn’t compete with foreign banks because they had to fund their balance sheets at LIBOR while the foreign banks could borrow at much lower deposit rates. As the derivatives business expanded in the 1990s, “Wall Street” was becoming Credit Suisse, Deutsche Bank, Nomura, and Barclay’s.

The Mortgage Bankers Association was out with a statement yesterday, speculating that the change in FHA MIP could be reversed by Ben Carson’s HUD. “”Based on recent testimony and political pushback, we believe there is a strong chance the most recent MIP reduction… may be one of the rollback actions taken soon after President Trump takes office.” Carson has said he would study how the change would affect the insurance fund, but hasn’t indicated whether he supports the change or not.

Note that we did see a rally in the Ginnie II higher coupon MBS yesterday despite a rough day for bonds otherwise. You can see in the chart below how Ginnie 4.5s (black line) outperformed Fannie 4.5s (blue line). Expect to see higher volatility in the higher note rates for FHA and VA loans as this plays out.

Negative equity is becoming less of a problem as home prices continue to rise. During 2016, 1 million homes regained positive equity, leaving only 2.2 million homes with negative equity. While we are still well above the bubble years in terms of negative equity, we have fallen markedly from the peak of 15.1 million homes in 2010. As houses regain positive equity, it will create refinance opportunities which will help offset the effect of higher rates. It will also increase mobility, which is one of the reasons why we have a low unemployment rate, but have so many workers still on the sidelines. They can’t move to where the jobs are because they are trapped in a home with negative equity they can’t sell.

Morning Report: Housing starts rise 1/19/17

Vital Statistics:

Last Change
S&P Futures 2265.3 -1.3
Eurostoxx Index 362.4 -0.7
Oil (WTI) 51.6 0.5
US dollar index 91.9 0.0
10 Year Govt Bond Yield 2.45%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 4.13

Stocks are lower this morning after the ECB decision to stand pat. Bonds and MBS are lower after Janet Yellen’s bullish comments on the economy and some decent data this morning.

Janet Yellen spoke yesterday, saying the economy was close to the Fed’s target, which warrants gradual rate hikes. Here are her prepared remarks. “That said, as of last month, I and most of my colleagues–the other members of the Fed Board in Washington and the presidents of the 12 regional Federal Reserve Banks–were expecting to increase our federal funds rate target a few times a year until, by the end of 2019, it is close to our estimate of its longer-run neutral rate of 3 percent.” That should have been a relative uncontroversial statement, given that roughly corresponds with the December dot plot. However, bonds sold off anyway.

Housing starts rose to 1.23 million in December from 1.1 million in November. Building Permits were flat at 1.21 million. Starts beat expectations while permits missed. Multifam drove the increase in starts, while single fam fell slightly.

Initial Jobless Claims fell to 234k last week nearly matching a low set in November. You would have to go back to the early 1970s (during the Vietnam war draft) to see claims this low. That is even more impressive when you factor in population growth. Employers are hanging onto their employees.

The Philadelphia Fed survey jumped last month as conditions improved for manufacturing. New orders and employment drove the increase.

Treasury Secretary nominee Steve Mnuchin travels to Capitol Hill today for his confirmation hearing. The questions will largely center on his role in the IndyMac turnaround, as well as his recommendations for the GSEs. He will also be asked about his comments regarding possible tax reform and whether the rich will receive an “absolute tax cut.”

The nonbank share of FHA lending is worrying some in Washington. As banks have retreated from FHA lending, nonbank lenders like Quicken and Freedom have taken up the slack. GNMA is conducting a push to lure banks back into the business.

The Fed’s Beige Book survey was a non-event. Most districts described their employment markets as “tight” and expansion as “modest.”

One bond investor thinks the bond bull market is still going to last a while longer. Why? The velocity of money has hit a floor since the Great Recession and hasn’t picked up. The velocity of money measures how many times a dollar has been “turned over” in different transactions. It peaked at 2.2x in 1997 and is currently sitting around 1.4x. This has been driven by the Great American Deleveraging which began with the bursting of the real estate bubble – income growth has been nonexistent, and the marginal dollar has been saved, not spent. The lower velocity is keeping a lid on inflation.

Bridgewater CEO Ray Dalio sees a mild bear market in bonds as economic growth picks up. He views the nascent populism being exhibited worldwide as a threat to multinational corporations and emerging economies. How politicians direct and engage that populism is going to be critical. Note that the Fed is addressing some of this by launching a new think tank: The Opportunity and Inclusive Growth Institute, which will be run by Minneapolis Fed head Neel Kashkari. Of course there isn’t much the Fed can do to address income inequality, however quantitative easing has largely benefited those that own assets, who are primarily rich.

Here is a good article on determining how much house you can afford.

Morning Report: Inflation back at the Fed’s target rate 1/18/16

Vital Statistics:

Last Change
S&P Futures 2267.0 5.0
Eurostoxx Index 362.1 -0.3
Oil (WTI) 61.7 -0.8
US dollar index 94.5 0.5
10 Year Govt Bond Yield 2.38%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 4.08

Stocks are higher this morning as bank earnings roll in. Bonds and MBS are down ahead of the European Central Bank’s first meeting, which is tomorrow.

Mortgage applications rose 0.8% last week as purchases fell 5% and refis increased 7%. The change in MIP spurred refinance applications and the FHA’s share of applications jumped.

Homebuilder sentiment slipped in December, however it is still elevated. A tight housing market is buoying the sector, while labor shortages and regulations continue to be headwinds.

The consumer price index increased 0.3% last month and is up 2.1% YOY. Ex-food and energy it was up 0.2% MOM and is up 2.2% YOY. While the CPI is not the preferred inflation index for the Fed (the Personal Consumption Expenditure Index is) it does show that inflation is back at the Fed’s target range. Gasoline and shelter drove the increase.

Note that rental inflation is beginning to moderate, especially at the top end. The overall rental index increased 3.4% this year, which was a deceleration from the 4% growth we saw the year before. That said, the lower price points are still exhibiting strong growth. There is still a wide geographic variation – from still torrid growth in the Northwest to negative in the South. Yet another data point to sell the first time homebuyer – on a 30 year fixed rate mortgage, your P&I payment isn’t going to increase.

It looks like home price appreciation is moderating in Southern California, after a long run.

Industrial Production increased 0.8% last month while manufacturing production increased 0.2%. Capacity Utilization ticked up to 75.5%.

We have a lot of Fed-speak today, and the World Economic Forum continues in Davos. There probably shouldn’t be any market moving news, but be aware. Janet Yellen speaks at 3:00 pm EST. Lael Brainard said today that if Trump’s fiscal policy ends up goosing the economy too much in the short term and doesn’t do enough to help foster long-term growth, the Fed will probably react by raising interest rates sooner, and more.

Trump Commerce Secretary pick Wilbur Ross heads to Capitol Hill for his confirmation hearing.

World leaders at the Davos Forum are scratching their heads wondering what happened with the Brexit vote and Donald Trump. The consensus is unsurprisingly that income inequality is the problem and the answer is more wealth redistribution. The problem is that there is no appetite for tax increases when people’s incomes are already squeezed. Meanwhile, here are the biggest risks for 2017, according to a survey of economists meeting there.

Has technology changed the seasonality aspect to the real estate industry? At least in New York City, it may have. Note the Spring Selling Season more or less unofficially starts right around Super Bowl Sunday.

JP Morgan is accused of racial bias in lending, however in this case it is at the wholesale level and their crime is allowing brokers to change their compensation, which allegedly ended up in minority borrowers paying higher rates and fees. Separately, Deutsche Bank settled for $7.2 billion for various and sundry mortgage violations.

Here is a good list of common-sense items to tell your borrower about getting a mortgage. No, don’t quit your job or buy a new car. Also, think twice about contesting the appraisal.

Morning Report: Populism the subject at Davos 1/17/16

Vital Statistics:

Last Change
S&P Futures 2265.0 -7.0
Eurostoxx Index 363.1 0.1
Oil (WTI) 53.2 0.8
US dollar index 91.1 -1.0
10 Year Govt Bond Yield 2.31%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 4.08

Stocks are lower this morning on Theresa May comments about Brexit. Bonds and MBS are up.

The World Economic Forum in Davos is going on this week. There may be a slight chance of market-moving data, but it is unlikely. The big subject is undoubtedly the wave of populism and anti-corporate / anti-government / anti-globalization going on throughout the world.

Corporate America seems to have read the tea leaves as well. GM just put out a headline saying they will invest $1 billion in US manufacturing operations and create 7,000 jobs. Walmart is getting into the action too. Even foreign companies are getting into the act. Of course some companies may be publicizing old plans to get the benefit of some good PR, the fact remains that big job cutting announcements are going to be out of style for a while. Don’t forget, the job market IS getting tighter, and (hopefully) the mindset of Corporate America is shifting from cost control to revenue growth.

Manufacturing in New York State slipped slightly last month according to the Empire State Manufacturing Survey. Growth is modest, however employment is still depressed.

James Bullard believes that the Fed can begin to think about shrinking its balance sheet as rates since rates are higher now than where they were. This would probably happen by not re-investing maturing assets. At the margin, this will translate into higher mortgage rates since TBAs will lose a natural buyer.

Strategist Komal-Sri Kumar is skeptical of the Fed’s forecast for interest rate hikes. His point is that the Fed cannot really raise rates in a vacuum, when all of the other central banks are going in the opposite direction. His call is for one hike this year. I am skeptical of a big fiscal stimulus out of Washington this year because Democrats will be united in opposition, and Republicans aren’t going to stick their necks out politically for a President they never wanted and don’t trust. The minutes from the Fed said explicitly that the forecast is based on expected fiscal stimulus. Note that many Fed officials are beginning to sour on the idea of additional fiscal stimulus.

In addition, if Trump manages to impose some additional tariffs (which IMO is a political non-starter) that will weaken the economy, and probably put the Fed on hold. Separately, Donald Trump just turned decades of US policy towards the dollar on its head, saying that the US currency is too strong. At the end of the day, presidents don’t really have all that much control over the economy.

Despite all the uncertainty about the government and the Fed, economic optimism remains just off a nine-year high.

The baby boomers drove housing construction through the 1970s and 1980s, yet their offspring (an even bigger generation) are not buying homes the way their parents did. What gives? Millennials earn 20% less (inflation adjusted) than their parents did at the same age. Not only that, but the consumer price inflation index deemphasizes /ignores things like college education which has going up multiples of the CPI. When you look at wealth, the numbers are even worse. That said, in 1989, mortgage rates were 10% and the principal and interest payment for a loan on the median house was 27% of median income versus around 21% today.

Morning Report: Ben Carson travels to Capitol Hill 1/13/17

Vital Statistics:

Last Change
S&P Futures 2266.0 2.5
Eurostoxx Index 364.4 1.9
Oil (WTI) 52.7 -0.3
US dollar index 92.0 -0.1
10 Year Govt Bond Yield 2.37%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 4.1

Markets are higher this morning as bank earnings come in. Bonds and MBS are down.

Inflation at the wholesale level remains under the Fed’s target rate, according to the Producer Price Index. The PPI was up 0.4% MOM and 1.2% YOY. Ex-food and energy, it was up 0.3% MOM and 1.4% YOY.

Retail sales increased 0.6% in December, however if you strip out autos and gasoline, they were flat. The control group rose by 0.2%, which missed expectations. For all the post-election increase in confidence, it didn’t translate into spending.

Business Inventories rose sharply (increasing 0.7%) in November, while sales increased 0.1%. The inventory to sales ratio came in at 1.38x, which is an improvement, but is still elevated. That said, inventory build is not the driver of the business cycle that it was 20 or 30 years ago.

Consumer sentiment slipped slightly to 98.1 from 98.6. This is the preliminary January reading.

We are getting bank earnings this morning. Wells missed estimates as mortgage revenue fell 15%. Issues with hedges drove down servicing revenue 73%. JP Morgan beat estimates, while Bank of America missed.

Ben Carson testified in front of the Senate yesterday. Here are his prepared remarks. He spent the a lot of time discussing the state of government housing and the role of housing to help the poor move up the economic ladder. He addressed regulations in several instances. First, he took aim at local zoning regulations that inhibit multifamily housing. Second, he mentioned that regulations have added 24% to the cost of a new house, and finally he discussed them with respect to credit.

Here are his comments with respect to origination: “Loans are now bifurcated: the well-off have their pick of loans and lenders while many others without solid credit or stable incomes are locked out – one of the reasons the economic recovery was slower than many would have liked. Homeownership rates have fallen on a year-over-year basis in every quarter for the last 10 years, and a surge in renting has dropped the homeownership rate to a 50-year low. Banks are loath to participate in low-down payment programs through FHA for fear of getting sued if the borrowers default. (emphasis mine) So we need to make sure HUD and FHA are fulfilling their missions to help people build up an asset, like a home, which will help them climb up the rungs of the economic ladder.”

On the subject of private capital, he supported more private capital in the mortgage market to displace government capital (which is a completely non-controversial sentiment). He also thinks that a government backstop is not necessary to keep a 30 year fixed rate mortgage, however he supports government involvement to keep it. Note that while the typical American considers a 30 year fixed rate mortgage to be their birthright, they are largely a US phenomenon. Everyone else has some sort of adjustable rate. Of course you could still have a 30 year fixed rate mortgage without the government backstop, however the rate will reflect the added risk.

Finally, he was asked about the recent decrease in FHA annual MIP and only said he would look at it. So, it looks like we aren’t going to see a wholesale change from the Obama administration, although GNMA may become a little more forgiving, at least at the margin. For the mortgage origination business, HUD isn’t the big driver – it is Treasury via the GSEs and the CFPB with enforcement.

NAR has a good wrap-up of the testimony. Here are the objections from the left.

Overall, Trump’s nominees have come across as relatively mainstream, so much so that Dick Durban (D-IL) commented on it. Trump’s response was that he wanted them to be themselves and to say what they thought, not what he thinks. Interestingly, the biggest difference between Trump’s cabinet and Obama’s is his lack of lawyers. Obama’s cabinet was dominated by them.

Builders are encouraged that a new administration will ease the shortage of buildable land caused by increased environmental regulations. They may be overoptimistic about what can be done, however. Many of these laws are local, which the Federal Government can’t do much about. Changing regulations takes a long time, with comment periods, and environmental groups have lawsuits at the ready if they sense the administration is no longer enforcing existing laws.

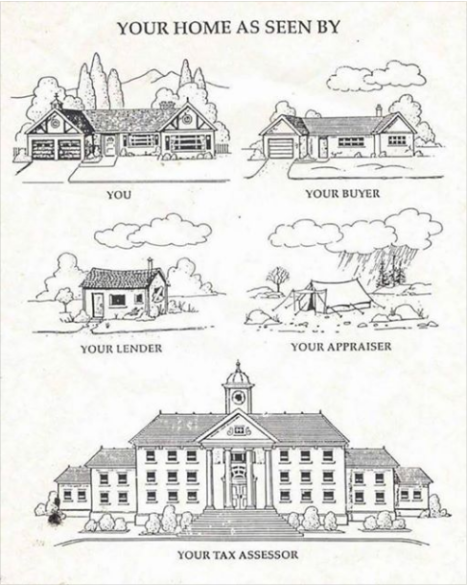
Finally, perspective is everything:

your-home

Morning Report: Market Reassessing post Trump risk-on trade 1/12/17

Vital Statistics:

Last Change
S&P Futures 2264.8 -6.0
Eurostoxx Index 364.0 -0.9
Oil (WTI) 53.3 1.1
US dollar index 91.8 -0.6
10 Year Govt Bond Yield 2.33%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 4.1

Markets are lower after Trump’s press conference yesterday. Bonds and MBS are up

We saw stocks sell off (and bond rally) after Donald Trump’s press conference yesterday. He did not address any sort of fiscal stimulus, which the markets were hoping to see. IMO the market may be realizing the huge stock market rally (and bond sell-off) post election was overdone. Trump also fired a shot across the bow of the pharmaceutical industry (which sent the S&P 500 downward), and got into it with a CNN reporter. He also will not divest his business operations. The pivot to a more presidential demeanor doesn’t look like it is going to happen. He is also introducing the dreaded “U” word – uncertainty – into the conversation with his tweets directed at specific companies. The markets are in a risk-off mood.

The first act of Congress was to set the stage to repeal Obamacare on a simple majority basis. The Senate passed it yesterday 51-48 and the measure goes to the House today. IMO, if the first legislative act is to repeal Obamacare on a party-line basis without any sort of replacement plan, any sort of bipartisan cooperation of tax reform and infrastructure spending is going to be almost impossible. Given the Fed’s forecast of 3 Fed Funds hikes this year was based on the assumption that we will have more fiscal stimulus, we could see a March hike taken off the table rather quickly, and I wouldn’t be surprised to see a further decline in overall interest rates. As Morgan Stanley said: Buy the election, sell the inauguration.”

St. Louis Fed Head James Bullard said that any of Trump’s proposed fiscal stimulus would be a 2018 and 2019 story, not a 2018 story. Infrastructure spending has a long lead time – the idea of “shovel ready” jobs is more or less a myth. Tax cuts would affect things sooner, but even then will be a 2018 story. The best chance for immediate results will be in regulatory reform.

We have a lot of Fed-speak today, with 3 speakers, so expect some volatility in rates during the day.

Import prices rose 0.4% last month, however if you strip out energy, they fell 0.2% and the YOY rate was flat. The strong dollar is helping keep inflation in check.

Initial Jobless Claims rose to 247,000 last week. We are still at exceptionally low numbers: employers are hanging on to their employees.

Ben Carson travels to Capitol Hill today to answer questions about his plans for HUD. Expect Republicans to focus on GSE reform and Democrats to focus on fair lending and affordable housing. There will undoubtedly be questions on his lack of experience in housing.

KB Home reported fourth quarter numbers yesterday. Revenues increased 21%, while average selling prices increased only 2%. We have been seeing a decline in ASP inflation from most of the builders. Backlog was the highest in 10 years. Deliveries were up 19%, while gross margins decreased to 16.5%. The stock is down about 4% on the open.

The fall in gross margins is a reflection of (a) increasing inflation and (b) an inability to pass on higher costs through price increases. Inflation is most prominent in increasing raw land costs, higher regulation, and also a tight market for skilled labor.

Foreclosures are at a 10 year low, and we are seeing better performance in many states. 379k people lost their homes to the bank last year. At the height of the crisis over a million people did. Home price appreciation helps as it takes the strategic defaulters off the table. The worst state for foreclosures? New Jersey.

The night of the election, Carl Icahn left the party early to buy S&P 500 futures down 100 points. He ended up taking a $1 billion position overnight and profited handsomely in the subsequent rally. Know who was short the whole time? Soros. Trading and politics are a dangerous mix. Politics is almost pure emotion.

Morning Report: Appraisals lag prices 1/11/17

Vital Statistics:

Last Change
S&P Futures 2262.0 -1.8
Eurostoxx Index 364.8 0.7
Oil (WTI) 51.1 0.3
US dollar index 93.0 0.3
10 Year Govt Bond Yield 2.37%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 4.11

Markets are flat ahead of Donald Trump’s news conference. Bonds and MBS are flat.

Mortgage Applications rose 5.8% last week as purchases rose 6% and refis rose 4%.

Secretary of State nominee Rex Tillerson will face Congress today. Jeff Sessions had his time in the box yesterday.

Home sales are falling through at a faster pace than last year, according to Trulia, and it is the starter home price points that are seeing it the most. 4.3% of all sales failed in the fourth quarter, compared to 1.4% two years ago. This may have to do with the increase in the number of first time homebuyers and the drop in professional investors which makes this probably a credit story. We are also seeing people who had foreclosures and bankruptcies during the bubble years re-approach the housing market as those events fall off their credit reports.

Part of this phenomenon could in fact be the divergence between the opinions of buyers / sellers and appraisers. According to Quicken loans, appraised values came in about 1.3% lower than owner expectations in November. Interestingly, appraised values fell in November, while house prices (at least according to the home price indices) have been rising. That said, appraisal values did increase almost 4% YOY, however that is much lower than the 6% or so home price appreciation we have been seeing in the other indices. That said, since appraisals use historical comparisons, some lag is to be expected.

Bob Shiller says the animal spirits are stirring in the housing market. Of course tight credit for both buyers and builders as well as increasing interest rates will offset that somewhat, but confidence plays a huge role in economic growth. That said, demographic headwinds are going to be an issue.

In keeping with the demographic headwinds issue, the Bipartisan Policy Center Senior Health and Housing Task Force has some advice for Ben Carson and helping the Baby Boom generation age in their homes.

Morning Report: Small Business Optimism jumps 1/10/17

Vital Statistics:

Last
S&P Futures 2264.5
Eurostoxx Index 363.6
Oil (WTI) 52.1
US dollar index 92.7
10 Year Govt Bond Yield 2.39%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 4.11

Stocks are flat this morning on no real news.  Bonds and MBS are flat as well.

Job openings increased to 5.5 million, according to the JOLTS report. This is at levels not seen since 2000. The quits rate has been steady at 2.1%, and that is the ultimate measure of labor market strength and a leading indicator for wage growth and inflation. As long as that number is steady, the Fed can be reasonably comfortable that inflation is going to stay low.

Small business optimism rocketed in December, according to the NFIB. The index rose 7.4 points to 105.8, the highest level since December 2004. The lion’s share of the gain was due to improving expectations, so it probably will be given back if big changes in the regulatory and tax environment don’t materialize. Job creation plans did hit a 9 year high, and capital expenditure plans jumped as well. That said, actual hiring in December was virtually unchanged from a month ago. That said, competition remains tight for skilled workers and a net 26% of respondents reported increasing compensation.

Despite the improvement for small business, some in Corporate America (the automakers) are not sure what to think. Trump’s jawboning over outsourcing has caused automakers general uncertainty, as the industry recovers from the worst slump since the Great Depression. The ultimate trade may in fact turn out that Trump will let Obama’s new fuel efficiency standards die in return for more production in the US.

Rising rates are hurting buyer sentiment, according to Fannie Mae. Their Home Purchase Sentiment Index fell for the fifth month in a row. The survey predicts that home prices will increase 2.1% next year, however the survey has been consistently lower than the professional forecasts, let alone actual price appreciation. Respondents also believe it is easier to get a mortgage than it was two years ago. Their view of the economy has improved dramatically, with roughly the same percentage of people thinking the economy is on the right track versus the wrong track. Note this optimism was reflected in the Gallup data as well.

There were 26,000 completed foreclosures in November, according to CoreLogic. The seriously delinquent rate was 2.5%, which is the lowest since August 2007. Foreclosure inventory remains concentrated in the judicial states of New York, New Jersey, and Florida. The seriously delinquent rate remains highest in NY and NJ as well, with rates of 5% and 5.6% on average.

Yesterday’s change in FHA MIP caused some strange activity in the TBA market which affected pricing. Bonds were up yesterday and pricing was generally better for most products, except for higher-coupon FHA and VA loans. That pricing actually worsened. Why? Because the change in annual MIP caused investors to bump up their prepayment assumptions for higher coupon Ginnie securities (generally those with 4% coupons and up). This makes those higher coupon mortgage backed securities worth less than last week, all things being equal. So if you priced out a FHA loan on Friday expecting to see better pricing, only to get an unpleasant surprise, the MIP change was the reason. On the bright side, refinancing just got more attractive.

Quicken CEO Dan Gilbert accused the Department of Justice of conducting a shakedown operation.

Goldman’s Dan Hatzius is handicapping a 35% of a March hike this year, while the Fed Funds futures are handicapping a 25% chance. Goldman is much more hawkish than the Fed in general, and they foresee a more linear hiking of rates while the Fed (and the futures markets) are forecasting a more gentle increase.

Morning Report: FHA mortgage insurance premiums drop 1/9/17

Vital Statistics:

Last Change
S&P Futures 2268.5 -3.0
Eurostoxx Index 263.4 -2.0
Oil (WTI) 52.9 -1.1
US dollar index 92.8 0.0
10 Year Govt Bond Yield 2.37%
Current Coupon Fannie Mae TBA 103
Current Coupon Ginnie Mae TBA 104
30 Year Fixed Rate Mortgage 4.11

Stocks are lower this morning on overseas worries. Bonds and MBS are up.

The week after the jobs report is typically data-light, however we will have a lot of Fed-speak this week, especially today, Thursday, and Friday.

The labor market conditions index slipped in December to -.3 from 1.2 in November. Note this is a meta-index of many leading and lagging indicators, so it is possible to have a so-so number just after a decent jobs report.

HUD announced they are cutting the annual insurance premium for most FHA loans by 25 basis points, which should save the typical homeowner about $500 annually. This will affect mortgages with a disbursement date after Jan 27. The reduction is due to the improving health of the housing market and the FHA’s insurance fund. Since the crisis, FHA has increased premiums by 150% to restore capital reserves. This reduction reverses that move and brings annual premiums back down to close to pre-crisis levels.

The current HUD Chairman, Julian Castro is worried that Ben Carson will roll back some of the HUD initiatives over the past several years. The one most likely to be on the chopping block is a controversial policy in which HUD sues local governments in order to force them to change their zoning laws in order to accommodate more multi-family housing. Westchester County in New York has been fighting this for the entire Obama administration.

Notwithstanding the jump in wage inflation last month, overall wage inflation has been hard to come by, not only in the US, but globally. The relationship between unemployment and wages seems to have broken down. What is going on? First, the most likely explanation is that the new jobs being created pay less than the jobs that were lost. This is the most plausible explanation, as many of the construction jobs that were lost in the bubble never came back, and most of the employment growth is coming in lower-paying health care jobs. Second, workers lost so much bargaining power in the recession that they don’t feel comfortable asking for more. A third explanation could be that the cost to employers has risen, but these costs are largely regulatory and don’t flow through to wages. Regardless of the reason, wage growth is an imperfect representation of labor market strength.

Now that it is becoming harder to find buildable lots, many homebuilders are returning to half-finished subdivisions that were abandoned as the housing bubble burst in 2007 and 2008. The supply of developed vacant lots (go-dirt) has fallen by 20% since 2011. The buyers seem to be the big national homebuilders like Lennar. The credit markets for homebuilders remains a case of “haves and have-nots.” The big builders are able to issue corporate debt at super-low interest rates while the small guys are getting turned down by the local bank.