Morning Report: Wholesale inflation comes in hotter than expected

Vital Statistics:

 LastChange
S&P futures4,122-33.50
Oil (WTI)78.38-0.18
10 year government bond yield 3.82%
30 year fixed rate mortgage 6.49%

Stocks are lower this morning after inflation at the wholesale level came in stronger than expected. Bonds and MBS are down.

Inflation at the wholesale level grew at the fastest rate since June of 2022, according to the Producer Price Index. This was after two months of declines in November and December. The index rose 6.0% on an annual basis. Energy costs were the big driver. This was higher than Street expectations.

Stripping out food, energy and trade services, the index rose 0.6% month-over-month and 4.5% year-over-year. This monthly increase was the fastest in nearly a year.

So, between the jobs report, the CPI report, retail sales and the PPI, we have evidence that growth accelerated in January. The Atlanta Fed’s GDP Now estimate has ticked up as well. The March Fed Funds futures see a 85% chance for a 25 basis point hike and a 15% chance for a 50 basis point hike. The projection materials and dot plot will be interesting.

Is there any gloom? Sure, housing. Housing starts fell to a seasonally-adjusted annual pace of 1.3 million in January. This is a 21% annual decline and the lowest level since June of 2020.

Chris Whalen has a great editorial about how FHFA is changing the rules for servicers as a result of COVID. Essentially loans in forbearance during COVID won’t be offered the same sort of reps and warrants relief as typically granted during a natural disaster. This creates an open-ended liability stream for mortgage bankers. Essentially the government asked servicers to offer forbearance and can now slug them for it.

He also mentions that a lot of banks are sitting on big unrealized losses on their portfolios of mortgages originated in 2020 and 2021. This includes Fannie Mae and Freddie Mac, which might explain the change in policy. He stated that banks have a $350 billion deficit for available for sale securities and loans. Many of these securities and loans are now trading at 15-20 point discounts in the market and might have to be sold. Hedge funds which are flush with cash might be able to pick up a good trade if that happens.

I am accepting ads for this blog if you would like to make an announcement, highlight something your company is offering or want more visibility. I also offer white-label services which give you the ability to use this content for your own daily emails. Please feel free to reach out to nyitray@hotmail.com if you would like to discuss this further.

Credit Suisse is spinning off its investment bank First Boston, which hasn’t existed for 25 years. Makes me wonder if other spin-offs might be in the cards. Synchrony spinning off Kidder Peabody, Bank of America spinning off Merrill Lynch, Deutsche Bank spinning off Bankers Trust, Citi spinning off Salomon Brothers and Smith Barney?

Investors bought 48,445 homes in the fourth quarter of 2022, which is the second biggest quarterly decline. “A lot of investors are on hold because they still see home prices declining,” said Elena Fleck, a Redfin real estate agent in Palm Beach, FL. “The investors who are in the market are selective and aggressive. Many of them are only offering around 60% of the asking price since it’s so difficult to make a profit when flipping homes right now.”

Note that there is a lot of political sturm and drang over investors purchasing single family homes as rentals. In the context of existing home sales (5 million units per year) 50k in a quarter seems like small beer.

“It’s possible that investors will start to wade back into the market this year given that mortgage rates have ticked down from their 2022 high—especially if home prices show signs of bottoming. But it’s unlikely that investors will return with the same vigor they had in 2021. That’s good news for individual buyers, who are still grappling with high housing costs but no longer losing bidding war after bidding war to investors.” Maybe the first time homebuyer might be able to get involved this Spring Selling Season.

Morning Report: Strong retail sales

Vital Statistics:

 LastChange
S&P futures4,130-15.50
Oil (WTI)78.38-0.78
10 year government bond yield 3.75%
30 year fixed rate mortgage 6.44%

Stocks are lower this morning after the strong retail sales number. Bonds and MBS are down.

Retail sales rose 3% month-over-month and 6.4% year-over-year according to the Census Department. This was well above expectations. Excluding vehicles and gas, sales rose 2.6% MOM. Note these numbers are not adjusted for inflation, so retail sales were flat YOY on an inflation-adjusted basis.

Homebuilder confidence improved in February, according to the NAHB. “With the largest monthly increase for builder sentiment since June 2013, the HMI indicates that incremental gains for housing affordability have the ability to price-in buyers to the market,” said NAHB Chairman Alicia Huey, a custom home builder and developer from Birmingham, Ala. “The nation continues to face a sizeable housing shortage that can only be closed by building more affordable, attainable housing. However, the two monthly gains for the HMI at the start of 2023 match the cautious optimism noted by the large number of builders at the recent International Builders’ Show in Las Vegas, who reported a better start to the year than expected last fall.”

“While the HMI remains below the breakeven level of 50, the increase from 31 to 42 from December to February is a positive sign for the market,” said NAHB Chief Economist Robert Dietz. “Even as the Federal Reserve continues to tighten monetary policy conditions, forecasts indicate that the housing market has passed peak mortgage rates for this cycle. And while we expect ongoing volatility for mortgage rates and housing costs, the building market should be able to achieve stability in the coming months, followed by a rebound back to trend home construction levels later in 2023 and the beginning of 2024.”And while builders continue to offer a variety of incentives to attract buyers during this housing downturn, recent data indicate that the housing market is showing signs of stabilizing off a cyclical low“

Mortgage applications fell 7.7% last week as purchases fell 5.5% and refis fell 12.5%. “Mortgage rates increased across the board last week, pushed higher by market expectations that inflation will persist, thus requiring the Federal Reserve to keep monetary policy restrictive for a longer time. After five straight weeks of decreases, the 30-year fixed rate increased by 21 basis points to 6.39 percent,” said Joel Kan, MBA’s Vice President and Deputy Chief Economist. “Mortgage applications decreased for the second time in three weeks because of these higher rates. Refinance borrowers, both rate/term and cash-out, remain on the sidelines as current rates provide little financial incentive to act.”

Added Kan, “Purchase applications dropped to their lowest level since the beginning of this year and were more than 40 percent lower than a year ago. Potential buyers remain quite sensitive to the current level of mortgage rates, which are more than two percentage points above last year’s levels and have significantly reduced buyers’ purchasing power.”

Inflationary expectations fell to 2.9%, according to the Atlanta Fed. This comports with the University of Michigan data. That said, we are still well above the 2% target for the Fed.

Industrial production was flat in January, according to the Federal Reserve. Manufacturing output rose 1%. Capacity Utilization fell to 78.3%.

Morning Report: Inflation comes in hotter than expected

Vital Statistics:

 LastChange
S&P futures4,134-12.50
Oil (WTI)78.09-2.78
10 year government bond yield 3.73%
30 year fixed rate mortgage 6.39%

Stocks are lower after the bad inflation print. Bonds and MBS are down.

We will have 3 Fed speakers today. It will be interesting if the CPI print comes up.

The consumer price index rose 0.5% MOM in January, breaking a streak of lower monthly numbers. Excluding food and energy the CPI rose 0.4%. Inflation rose 6.4% on an annual basis. Shelter was the biggest addition to inflation, and that will fade as we get into summer where home prices peaked last year.

The part the Fed is worried most about is services ex-housing, which is basically wage inflation. The labor market remains tight as a drum and wages are still increasing at a faster pace than the Fed would like to see. The White House just put out something on this subject – average hourly earnings for the non-housing services. You can see the spike in this index over the past year

Luckily it is going in the right direction, but we are still above the highest pre-pandemic level going back 30 years. That fact is going to keep the Fed on the inflation beat. People hoping for a Fed pivot will need to watch this index.

Small Business Optimism increased in January, according to the National Federation of Independent Businesses. Prices are still increasing, although the net number of businesses raising prices did moderate a touch.

“The Index of Small Business Optimism has been in recession territory
all last year and into 2023. If it weren’t for the Job Openings and Hiring
Plans components, the Index would be much lower
. Actual capital
spending and inventory investment are very weak as are plans to
spend. Earnings are dismal. Actual sales trends are negative and
expected real sales are also. When we ask owners if they have any job
openings they reply “yes, I’d hire more if I could,” so hiring plans are
historically high as is the level of job openings. Everything else is pretty
much in the tank
. When we ask owners if they were successful in hiring
and filling open positions, the answer is “no,” more firms reported
reducing employment than increasing it and the average addition of
workers is smaller than the reported reduction. These openings and
hiring plans roll over from month to month.”

If you look at the historical chart, you can see things are pretty much lousy, back towards what we saw during the Great Recession.

Black Knight is close to selling its Empower LOS is order to gain antitrust approval to merge with Intercontinental Exchange. The antitrust regulators were almost certain to prohibit Encompass and Empower from being under the same roof. Encompass and Empower are the #1 and #2 loan origination systems in what is a pretty concentrated industry. No mention of who would be the buyer.

Rate lock volumes rose 23% in January according to the Black Knight Mortgage Monitor. Some of this is seasonality, however lower rates are playing a part as well. “Mortgage rates declined in January, continuing a trend that began in early November 2022,” said Kevin McMahon, president of Optimal Blue, a division of Black Knight. “Conforming rates dropped 36 basis points from where they were at the start of the year, and we saw that rates associated with those FHA/VA/jumbo locks all came down in kind. Triggered by this pullback, rate lock volumes rose for the first time since March 2022, driven by declining interest rates and seasonal tailwinds, snapping a nine-month streak of declines.”

Morning Report: Loan demand falls while standards tighten

Vital Statistics:

 LastChange
S&P futures4,109 9.50
Oil (WTI)78.95-0.78
10 year government bond yield 3.75%
30 year fixed rate mortgage 6.33%

Stocks are higher this morning on no real news. Bonds and MBS are down.

The week ahead will have some important data on housing and inflation, with the Consumer Price Index on Tuesday, and the Producer Price Index on Thursday. We will also get housing starts and builder sentiment. Other important data points are retail sales, small business optimism and leading economic indicators.

Mr. Cooper reported fourth quarter numbers on Friday. Funded volume was $3.2 billion, a decrease of 39% QOQ and 82% compared to the fourth quarter of 2021. Servicing income kept the lights on, and Mr. Cooper is valuing its MSR portfolio more conservatively (at 5.1x) than many of the mortgage REITs which seem to have values from 5.5x – 6.1x.

Loan demand is falling, while lending standards are getting tighter, according to the Fed. This is typical for an economy that is poised to enter a recession. Loan demand for residential real estate was weak, and standards tightened for HELOCs, credit cards, auto loans and other consumer debt.

The Fed also observed the same phenomenon for commercial and industrial loans, as well as commercial real estate.

The Atlanta Fed GDP Now Index sees 2.1% GDP growth in Q1, while the Street sees it coming in mildly negative.

Morning Report: Consumer sentiment rises

Vital Statistics:

 LastChange
S&P futures4,073-18.50
Oil (WTI)79.030.92
10 year government bond yield 3.69%
30 year fixed rate mortgage 6.26%

Stocks are lower this morning on no real news. Bonds and MBS are down.

Consumer sentiment rose in February, according to the University of Michigan Consumer Sentiment Survey. The strong jobs report last week probably contributed, however gasoline prices are a factor too. Unfortunately for those who want the Fed out of the way, inflationary expectations increased, rising to 4.2% from 3.9% in January. Longer-term inflationary expectations were steady at 2.9%. To put the current numbers into perspective, we are about 22% below the historical average since 1978.

Mortgage credit availability contracted slightly in January, according to the MBA. “Mortgage credit availability was essentially unchanged in January and remained close to its lowest level since 2013,” said Joel Kan, MBA’s Vice President and Deputy Chief Economist. “Similar to December 2022, the availability of credit has been driven lower by declining originations and shrinking industry capacity as lenders have streamlined their operations to cope with lower volumes. Additionally, as mortgage rates declined over the past month, the share of adjustable-rate mortgages has fallen – consistent with a slight pullback in ARM offerings in this month’s results. However, there has been a revival in mortgage application activity over the past month and our forecast is for rates to continue to decline and housing activity – including home sales and new home construction – to gradually pick up as we approach the spring homebuying season. These developments could potentially change the credit availability landscape in the months ahead.”

Rental growth grew only 2% in January, according to Redfin. This was the slowest increase in 20 months. “We’re watching closely to see whether rents start falling year over year. That would be a welcome relief for renters  because it hasn’t happened since the onset of the pandemic,” said Redfin Chief Economist Daryl Fairweather. “If rents do start falling on a year-over-year basis, it will mean that renters have more room to negotiate. It may also prompt more landlords to sell their properties because they’re no longer getting a good return on their investment.”

There is a seasonal aspect to rental growth, which you can see in the chart above. Rents tend to bottom in January-February and then accelerate as the Spring Selling Season begins. It happened in 2020 and 2021, but not 2022. Historically, rents have lagged home price growth by 21 months, so we should probably see another pickup into the spring.

Morning Report: Servicing valuations look elevated

Vital Statistics:

 LastChange
S&P futures4,16332.50
Oil (WTI)77.61-0.86
10 year government bond yield 3.59%
30 year fixed rate mortgage 6.30%

Stocks are up this morning on positive earnings. Bonds and MBS are up.

Initial Jobless Claims rose to 196,000 last week. This comports with the jobs report last Friday.

New York City is the most “rent-burdened” MSA out there, with people paying 69% of their income in rent. In order to NOT be considered rent-burdened, you have to make $177k. Other MSAs include Miami, Fort Lauderdale and Los Angeles.

Rithm Capital (aka New Rez) reported earnings yesterday. Mortgage origination volume fell 43% QOQ and 80% YOY to $7.9 billion. The company is guiding for Q123 volume to fall further to $5 – 7 billion. On the plus side, gain on sale margins rose 10 bp QOQ and 16 bp YOY to 1.81%. Funds available for distribution came in at $0.33, so the $0.25 dividend is well-covered at least for now.

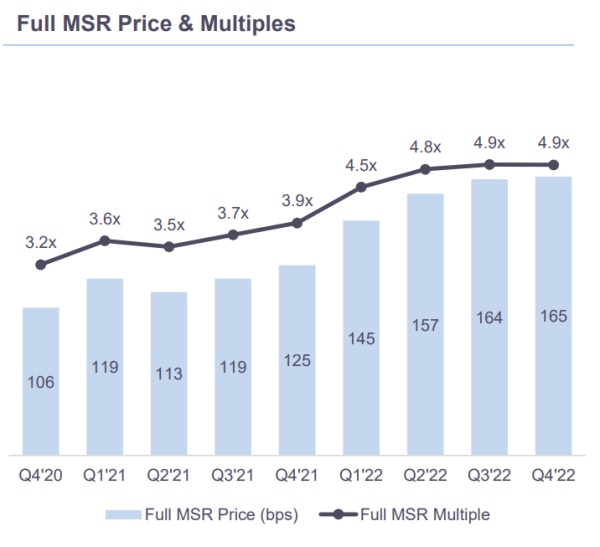
The servicing portfolio has been the engine of growth, but it looks like they are valuing their portfolio pretty much fully at 4.9x servicing revenue.

Rithm is also building other businesses including single family rentals and its reno / construction / bridge loan businesses.

PennyMac Mortgage Investment Trust got beat up in the fourth quarter, as origination income fell. Note where they are valuing their servicing portfolio:

6.1 times is pretty hefty, and with their origination volume at 50% government, I wonder how much is FHA. Government servicing is not trading at 6 times. The MSR market is pretty well-supplied with originators selling their servicing portfolios to raise cash. I have to imagine the actual secondary market is well below that regardless of size.

Morning Report: The Fed has no plans to sell MBS

Vital Statistics:

 LastChange
S&P futures4,159-16.75
Oil (WTI)77.080.66
10 year government bond yield 3.65%
30 year fixed rate mortgage 6.26%

Stocks are lower as investors continue to digest Jerome Powell’s comments yesterday. Hawks and doves both found something to seize upon. Bonds and MBS are up small.

We have 5 Fed speakers today, with Neel Kashkari (heavy hawk) speaking at 12:30.

Jerome Powell spoke yesterday, calling the US labor market “extraordinarily strong.” He did acknowledge that the disinflationary process has begun and we have seen progress on goods, however services remain high. It will take “not just this year but next year to get down to 2%,” the central bank’s inflation target, Powell said. And rates will have to remain at a restrictive level “for a period of time” before that happens, he noted. There has been an expectation that [inflation] will go away quickly and painlessly; I don’t think it’s guaranteed that’s the base case,” Powell said. “It will take some time.”

Jerome Powell talked with David Rubenstein and discussed the Fed’s plans to reduce the size of its balance sheet. Powell characterized it as passive reduction, which means it will let its portfolio mature and run off but not actively sell its holdings. While the Fed said it could consider sales of mortgage backed securities, it isn’t something that is being actively considered.

The Fed purchased its portfolio of mortgage backed securities when rates were extremely low, and liquidity is fickle in the MBS market. Unless a coupon is being actively originated, it won’t trade with any meaningful liquidity. The 3.5% coupons the Fed owns are trading well below par and the Fed would struggle to actually sell any of its holdings.

Mortgage applications rose 7.4% last week as purchases rose 4% and refis rose 18%. “Applications rose last week as the 30-year fixed mortgage rate inched lower to 6.18 percent, its fifth consecutive weekly decline. The 30-year fixed rate is almost a percentage point below its recent high of 7.16 percent in October 2022,” said Joel Kan, MBA’s Vice President and Deputy Chief Economist. “Both purchase and refinance applications increased last week and have shown gains in three of the past four weeks because of lower rates. Overall applications remained 58 percent lower than a year ago and rates are still significantly higher, however, this week’s results are a step in the right direction. Purchase activity that was put on hold last year due to the quick runup in rates is gradually coming back as rates ease and housing demand remains strong, driven by supportive demographics and the ongoing strength in the job market.”

Added Kan, “The average loan size on a purchase application increased to $428,500 – the largest average since May 2022. This increase is a sign that the recent upward trend in purchase activity remains skewed toward larger loan sizes and less first-time homebuyer activity, as entry level housing remains undersupplied, and buyers struggle with affordability in many markets.”

I talked about yield curve inversions and what they mean in a recent Substack article.

Home prices fell 0.4% MOM and rose 6.9% YOY according to the CoreLogic Home Price Index. CoreLogic sees prices falling another 0.2% in January and rising 3% in 2023.

“The continued slowing of home prices at the end of 2022 reflects weaker housing market demand, primarily caused by higher mortgage rates and a more pessimistic economic outlook in general. But while prices continued to fall from November, the rate of decline was lower than that seen in the summer and still adds up to only a 3% cumulative drop in prices since last spring’s peak.

Some exurban regions that became increasingly popular during the COVID-19 pandemic saw prices jump and affordability erode at the time, but these areas are now seeing major corrections. And while price deceleration will likely persist into the spring of 2023, when the market will probably see some year-over-year declines, the recent decrease in mortgage rates has stimulated buyer demand and could result in a more optimistic homebuying season than many expected.”

I am accepting ads for this blog if you would like to make an announcement, highlight something your company is offering or want more visibility. I also offer white-label services which give you the ability to use this content for your own daily emails. Please feel free to reach out to nyitray@hotmail.com if you would like to discuss this further.

Morning Report: Housing Affordability Woes

Vital Statistics:

 LastChange
S&P futures4,1240.75
Oil (WTI)75.161.06
10 year government bond yield 3.66%
30 year fixed rate mortgage 6.23%

Stocks are flattish as we await Jerome Powell’s speech this afternoon. Bonds and MBS are down.

Neel Kashkari went on CNBC this morning to say that the Fed still had to raise rates “aggressively” in order to get inflation under control. The data “tells me that so far we’re not seeing much of an imprint of our tightening to date on the labor market. There’s some evidence that it’s having some effect, but it’s pretty muted so far,” Kashkari said. “I haven’t seen anything yet to lower my rate path, but I’m obviously keeping my eyes open and we’ll see how the data comes in,” he added. Neel Kashkari thinks the Fed Funds rate will have to rise to a range of 5.25% – 5.4% in order to cool off the labor market.

Rate locks saw an uptick in January as mortgage rates fell, according to the Black Knight Mortgage Monitor. “Based on our Optimal Blue rate lock data, we can see definite signs of a January uptick in purchase lending on lower rates and somewhat lower home prices,” said Graboske. “Indeed, locks on purchase mortgages soared 64% from the first through the fourth week in January. On the surface, it may seem the market has been stirred by a full point decline in interest rates and home prices coming off their peaks – but it’s not that simple. Yes, according to the Black Knight Home Price Index, December did see home values post their sixth consecutive monthly decline, and prices at the national level are now 5.3% off their June 2022 peaks. But affordability still has a stranglehold on much of the market, with the monthly mortgage payment on the average-priced home more than 40% higher than it was this time last year. It’s also important to keep January’s surge in purchase activity in perspective. While up, purchase locks were still running roughly 13% below pre-pandemic levels for the last full week of the month.

The affordability metric is (the monthly mortgage payment as a percentage of income) is above levels we saw during the bubble years, and compares to levels last seen in the early 1980s when the Fed took the Fed Funds rate into the teens to whip 1970s inflation.

In order to square the affordability circle either mortgage rates have to fall, home prices have to fall or wages have to increase. The problem is that we need a dramatic move in at least one of these to fix the issue. If mortgage rates fall somewhat and wages rise by 4%, we still have an affordability problem. Ultimately I think the lack of supply carries the day and homes stay unaffordable for the near term until homebuilding rebounds. And if you look at the big decreases in backlog reported by the builders (along with elevated cancellation rates) that doesn’t appear to be in the cards this year.

With home prices stabilizing or even falling, some financial “power buyers” are stuck holding the bag. These companies would bid for a property on behalf of a buyer and then sell the property to the buyer at the same price once they got a mortgage. The power buyer would earn a fee and the buyer would get to submit a non-contingent offer. Some of these buyers are now backing out of these deals because they can’t qualify for a mortgage at current rates. Ribbon, one of these power buyers is stuck with 400 homes and has been forced to cut 85% of its work force.

“There was sort of a power shift, from the power sitting with the seller knowing that their home is going to sell within a day, to the power sitting with the buyer,” said Tim Heyl, founder of the Austin-based power buyer Homeward Inc. Note the location. Goldman recently said that Austin could see a 2006-esque decrease in prices.

Given the track record of Zillow, OpenDoor and these power buyers, perhaps investing in real estate is harder than it looks, and a gee-whiz model to value real estate isn’t enough to crack the code.

Morning Report: The Fed Funds futures signal more hawkishness after the strong jobs report

Vital Statistics:

 LastChange
S&P futures4,120-27.75
Oil (WTI)74.03 0.66
10 year government bond yield 3.61%
30 year fixed rate mortgage 6.07%

Stocks are lower this morning as investors continue to digest the strong jobs report. Bonds and MBS are down.

The week after the jobs report is generally pretty data-light and next week is no exception. We have limited Fed-speak as well, and about the only thing remotely market-moving next week will be consumer sentiment on Friday.

The strong jobs report caused a more hawkish move in the Fed Funds futures. The march meeting is a lock for another 25 basis points, and there is a 73% chance for another 25 in May. Before the jobs report, investors saw a 40% chance of another hike this year. That said, the December futures see rates at the end of the year between 4.75% and 5%, which is 25 basis points higher than here.

The Wall Street Journal has an article about how housing has probably bottomed. We are seeing traffic increase and realtors are getting more calls. A big difference is that mortgage rates are now around 6% versus 7%+ in the fall of 2022. That said, homebuilders are still seeing outsized cancellation rates, and 2023 is expected to be another tough year for the sector.

One of the markets Goldman mentioned as vulnerable to a 2008-style decline was Austin, TX. The median home prices has fallen by 20% since June, but the rise in mortgage rates means that the median income required to buy that home has increased by 27%. Out-of-town buyers drove up prices beyond what the median income could support. We are seeing the same phenomenon in many Western MSAs like Boise, ID.

“The upside is that local first-time homebuyers finally have an opportunity; they’re no longer facing fierce competition from out-of-towners and investors,” Austin Redfin agent Maggie Ruiz said. “The downside is that 6% mortgage rates are still making homes unaffordable for many people. I’m advising buyers to negotiate with sellers on price and terms, consider buying down their mortgage rate and get into the market now if possible. As soon as rates drop, competition will be back.”

“I’m not seeing many local move-up buyers. Most Austin locals who already own their home are staying put because they don’t want to take on a higher mortgage rate,” she continued. “Some are capitalizing on higher home values, selling and relocating out of Texas to somewhere that’s still more affordable.”

Morning Report: Strong jobs report

Vital Statistics:

 LastChange
S&P futures4,147-44.75
Oil (WTI)75.65-0.11
10 year government bond yield 3.49%
30 year fixed rate mortgage 5.98%

Stocks are lower after the strong jobs report. Bonds and MBS are down

The economy added 517,000 jobs in January, which was way above expectations, while the unemployment rate inched down to 3.4%. The labor force participation rate the employment-population ratios were unchanged and remain below pre-pandemic levels. November and December payrolls were adjusted upward by 71,000.

Leisure and hospitality added the most jobs (+128,000) however employment in this sector remains below pre-pandemic levels. Professional and business services and health care were also big contributors to job growth. Average hourly earnings rose 0.3% month-over-month and 4.4% year-over-year.

The growth rate in average hourly earnings is declining, however we are still above pre-pandemic levels.

Needless to say, this report will be too strong for the Fed’s liking. This explains the reaction of stocks and bonds to the report. The Fed wants to cool the labor market and so far it hasn’t gained any traction. The unemployment rate has broken below pre-pandemic levels and is now back at the lowest in over 50 years.

PennyMac Financial Services reported that origination volumes in the fourth quarter were $23 billion, down 12% from Q3 and 41% from a year ago. For the year, PFSI originated $109 billion, which was down 54% compared to 2021. In terms of profitability, servicing carried the load, offsetting the losses in the production segment.

Production margins fell to 55 basis points from 99 in Q3 and 119 basis points a year ago. The decline in margins was driven primarily by origination mix – consumer direct fell dramatically while correspondent remained stable. Delinquency rates ticked up again, but remain below pre-pandemic levels.

The ISM Services Index rebounded in January after contracting in December.“Business Survey Committee respondents indicated that capacity and logistics performance continue to improve. Although responses varied by industry and company, the majority of panelists indicated that business is trending in a positive direction. Employment was unchanged for the month. Some companies still find it difficult to fill open positions, while others are facilitating staff reductions.”

I am accepting ads for this blog if you would like to make an announcement, highlight something your company is offering or want more visibility. I also offer white-label services which give you the ability to use this content for your own daily emails. Please feel free to reach out to nyitray@hotmail.com if you would like to discuss this further.