Morning Report – Washington has a “eureka” moment 7/24/13

Vital Statistics:

  Last Change Percent
S&P Futures  1693.5 5.2 0.31%
Eurostoxx Index 2756.0 33.1 1.22%
Oil (WTI) 106.8 -0.4 -0.36%
LIBOR 0.264 -0.002 -0.60%
US Dollar Index (DXY) 81.99 0.043 0.05%
10 Year Govt Bond Yield 2.57% 0.07%  
Current Coupon Ginnie Mae TBA 104.4 0.0  
Current Coupon Fannie Mae TBA 103.8 -0.3  
RPX Composite Real Estate Index 200.7 -0.2  
BankRate 30 Year Fixed Rate Mortgage 4.3    

Markets are higher this morning after a good earnings report out of Apple. Bonds are again victims of the risk-on trade.

 
Michael Dell and Silver Lake boosted their buyout offer for Dell by ten cents to $13.75. It is their best and final offer. Dude, you’re getting a dime.
 
Mortgage Applications fell 1.2% last week. Purchase apps were down 2.1%, while refis were more or less flat. Refi volume has dropped to 63% of total applications. The conventional index rose about 60 bps, while the govvie index dropped 7%.
 
The U.S. taxpayer bears the credit risk of roughly half the U.S. mortgage market and 90% of all new origination. In a true “eureka” moment, the braintrust in Washington may have finally figured out that the problem is not that they haven’t slugged the banks hard enough. There is a proposal to relax the “skin in the game” rules for private label securitizations in the hopes that something other than 60% LTV / 740 FICO jumbos can be securitized in the future. The original rule was that banks would have to maintain 5% of all MBS they securitize, unless the LTV was lower than 80%. Now, they propose to require a 5% holding only for IO and stated income products. Never mind that IO and stated income are outside of the QM rules and very few market participants are willing to take non-QM risk.
 
The ARM is coming back. 

Morning Report – FHFA House Price Index rises 7.3% YOY 7/23/13

Vital Statistics:

  Last Change Percent
S&P Futures  1692.7 2.4 0.14%
Eurostoxx Index 2739.6 14.2 0.52%
Oil (WTI) 105.8 -1.1 -1.06%
LIBOR 0.266 0.001 0.45%
US Dollar Index (DXY) 82.28 0.058 0.07%
10 Year Govt Bond Yield 2.52% 0.04%  
Current Coupon Ginnie Mae TBA 104.6 -0.2  
Current Coupon Fannie Mae TBA 104.1 -0.2  
RPX Composite Real Estate Index 200.7 -0.2  
BankRate 30 Year Fixed Rate Mortgage 4.3    


Markets are slightly higher on a mixed bag of earnings and emerging Asia strength. Bonds and MBS are victims of the risk on trade.
 
The FHFA House Price Index rose .7% in May, and about 7.3% year-over-year. The FHFA House Price index is based on houses that have a conforming mortgage attached to it, so it eliminates the highly distressed sales and the high end of the market. This makes it more of a “central tendency” index than Case-Schiller. We are still seeing a wide geographical dispersion of increases, with the East Coast lagging while the West Coast is hitting big numbers.


Fannie Mae is predicting that mortgage rate will average 4.7% in Q4, about 40 basis points higher than their June forecast. They are predicting 2013 GDP will come in around 2% and will hit 2.6% in 2015. Home Sales are forecast to increase 8% in 2013. While they have yet to adjust sales forecasts to the new interest rate regime, they are watching it closely.
 
Professional (read cash) investors are stepping away from the real estate market as prices continue to rise. Investor traffic fell in June for the fourth straight month. Perhaps rising prices are to blame, but perhaps private equity and hedge funds are realizing that achieving high single-digit rental yields is harder than it looks and takes more than a couple smart guys out of New York to make it happen.


Morning Report – NVR earnings 7/22/13

Vital Statistics:

  Last Change Percent
S&P Futures  1690.5 1.0 0.06%
Eurostoxx Index 2718.7 2.5 0.09%
Oil (WTI) 108.5 0.4 0.37%
LIBOR 0.265 0.000 0.00%
US Dollar Index (DXY) 82.35 -0.254 -0.31%
10 Year Govt Bond Yield 2.47% -0.01%  
Current Coupon Ginnie Mae TBA 104.6 0.0  
Current Coupon Fannie Mae TBA 104.2 -0.3  
RPX Composite Real Estate Index 200.7 -0.2  
BankRate 30 Year Fixed Rate Mortgage 4.35    


Markets are flat on no real news. Earnings season swings into full gear this week with an assortment of heavyweights. Bonds and MBS are flat.
 
Homebuilder NVR has released earnings. Looks like they were light on the bottom line, but there was a special charge. New orders increased 25%. Revenues increased 31%. NVR is east-coast focused, so it is lagging some of the West-Coast builders. Later this week, we will hear from Pulte, Standard Pacific, and D.R. Horton. It will be interesting to hear how traffic has been affected by the increase in rates.
 
Bill Gross thinks the Fed won’t raise the Fed funds rate until 2016 at the earliest.. Of course he is talking his book, but still… Interest rate cycles are very long.. This chart comes courtesy of Barry Ritholz, with long term interest rates going back to 1790. Note that from 1930 through 1960 we also had a period of exceptionally low interest rates. 


While it is probably a very nichey product, you can buy a house for your elderly parents or college student and not have it treated as a garden-variety investment property. Fannie Mae has a program for people who want to purchase a home for a family member and don’t have the money for a downpayment. Just another arrow in your quiver, LOs.

Morning Report – liquidity is drying up in the TBAs 7/19/13

Vital Statistics:

  Last Change Percent
S&P Futures  1679.7 -0.9 -0.05%
Eurostoxx Index 2716.0 -2.0 -0.07%
Oil (WTI) 109 1.0 0.90%
LIBOR 0.265 -0.002 -0.56%
US Dollar Index (DXY) 82.68 -0.140 -0.17%
10 Year Govt Bond Yield 2.52% -0.01%  
Current Coupon Ginnie Mae TBA 104.2 -0.2  
Current Coupon Fannie Mae TBA 103.9 0.0  
RPX Composite Real Estate Index 200.8 -0.2  
BankRate 30 Year Fixed Rate Mortgage 4.37    


Markets are weaker this morning after a mixed bag of earnings. GE beat, while Mr Softee missed by a country mile. There is no economic data this morning. Bonds and MBS are flat / down small.
 
Liquidity has been drying up in the TBA market, with bid / ask spreads increasing to 7 ticks on the higher coupons. Yesterday, just over $3.2 billion worth of TBA traded, which made it the second lowest volume day of 2013. What does this mean for you? Thin markets can be volatile. We will likely see more re-prices during the day, and aggregators will fade their bids to account for lousier execution on their hedges. 
 
Ever wonder how the government sets G-fees? Well, here ya go..
 
Wonkish piece, but sheds light on the labor force participation rate and why it isn’t coming back to previous levels. This has implications for the Fed, in that it won’t take much in the way of job growth to keep moving unemployment levels to where the Fed will start thinking about tightening. While the Fed pledges to use a holistic approach, we could be getting to 6.5% unemployment the hard way. Which means, don’t expect super robust recovery – the population is aging and that is a drag on growth and spending.


Morning Report – Day 2 of testimony 7/18/13

Vital Statistics:

  Last Change Percent
S&P Futures  1677.3 1.7 0.10%
Eurostoxx Index 2685.2 3.3 0.12%
Oil (WTI) 106.7 0.3 0.23%
LIBOR 0.266 0.000 0.00%
US Dollar Index (DXY) 82.87 0.160 0.19%
10 Year Govt Bond Yield 2.49% 0.00%  
Current Coupon Ginnie Mae TBA 104.6 4.8  
Current Coupon Fannie Mae TBA 104 0.3  
RPX Composite Real Estate Index 201.1 -0.5  
BankRate 30 Year Fixed Rate Mortgage 4.35    

Markets are flattish ahead of Day 2 of Ben Bernanke’s testimony. Initial Jobless Claims dropped back to 334k after spiking to 358k the weak before. Bonds and MBS are flat. In earnings, Intel and Ebay missed, while Morgan Stanley beat.


The Bernank goes in front of the Senate this morning at 10:30. Most of the newsworthy tidbits should have been released yesterday, but be aware – rates could get volatile. 
 
The Senate Banking Committee is expected to vote on Mel Watt to head FHFA. If he gets nominated, expect the government to start forgiving principal on underwater conforming loans and probably HARP 3.0. Watt is an affordable housing guy who will push for loan forgiveness and easier access to credit for low-income borrowers. Maybe the refi boom will have one last gasp.
 
Most of Bernanke’s testimony was old news, but there were some new revelations. The biggest one is that the Fed intends to roll over maturing MBS into new MBS even after QE ends. There was a fear that the Fed would sell their holdings. So that should put downward pressure on mortgage rates. Second, Bernanke said that as long as inflation is below their target rate, the Fed Funds rate is going nowhere. Finally, he mentioned de-leveraging as one of the main reasons why rates shot up so much. There has been a suspicion in the market that the carry trade was the real target. 


Morning Report – A softening on QE tapering? 7/17/13

Vital Statistics:

  Last Change Percent
S&P Futures  1677.5 6.3 0.38%
Eurostoxx Index 2685.7 20.0 0.75%
Oil (WTI) 106 0.0 -0.04%
LIBOR 0.266 0.000 0.00%
US Dollar Index (DXY) 82.5 -0.002 0.00%
10 Year Govt Bond Yield 2.47% -0.06%  
Current Coupon Ginnie Mae TBA 104.4 -1.1  
Current Coupon Fannie Mae TBA 104.2 0.4  
RPX Composite Real Estate Index 201.6 -0.9  
BankRate 30 Year Fixed Rate Mortgage 4.48    


Markets are higher this morning after good earnings out of Bank of America. Mortgage Applications fell 2.6% last week, a surprise given that rates fell. Bonds and MBS are up. The initial reaction to the prepared remarks is positive.
 
Today is Bernanke’s semiannual Humphrey-Hawkins testimony in front of Congress, which begins at 10:00. The first thing to note is that this can be market moving, so don’t be surprised if we get some volatility around rates. The burning questions concern the end of QE, although expect a lot of Congressional questions on banking regulation and Too Big To Fail. The prepared remarks are here.
 
The comment that seems to have everyone buying bonds is the statement that ending quantitative easing is “not on a preset course.” Remember that was what hit the markets so hard the last time Bernanke spoke in front of Congress – he implied that the Fed expects unemployment to fall to 7% by the end of the year, and if the economy performs as expected, they will begin tapering QE this year. This statement seems to be a softening of that stance. This has pushed the 10 year to 2.47%.
 
Housing starts came in at a disappointing 836,000 annual pace. Building Permits fell as well. When you look at the internals, it was multi-fam which drove the decrease. Single family starts dropped by 5k, while 5+ units fell from 322k to 236k. Multi-fam in the South took the biggest hit. May was revised upward. I wouldn’t read too much into this as far as purchase business goes – the weekly MBA purchase application index rose last week, and the homebuilders have been optimistic so far. Also note that homebuilder sentiment hit the highest levels since Jan 2006. 
 
The Senate reached a filibuster deal yesterday, and Richard Cordray was confirmed as head of the Consumer Financial Protection Bureau (CFPB). Republicans had been holding up the vote in an attempt to force changes to the agency – to make it a bipartisan committee vs a single head and to subject it to the normal Congressional appropriations process. Will it affect anything in our area? I am guessing not.

Morning Report – Affordability remains high 7/16/13

Vital Statistics:

  Last Change Percent
S&P Futures  1676.7 -0.8 -0.05%
Eurostoxx Index 2667.9 -18.8 -0.70%
Oil (WTI) 106.9 0.6 0.55%
LIBOR 0.266 -0.001 -0.52%
US Dollar Index (DXY) 82.74 -0.299 -0.36%
10 Year Govt Bond Yield 2.54% 0.00%  
Current Coupon Ginnie Mae TBA 104.2 -1.3  
Current Coupon Fannie Mae TBA 103.6 0.0  
RPX Composite Real Estate Index 202.5 -0.5  
BankRate 30 Year Fixed Rate Mortgage 4.45    
Markets are flattish after the consumer price index came in more or less in line with expectations and Goldman beat earnings estimates. Bonds and MBS are flat as we await the Bearded One tomorrow morning.
 
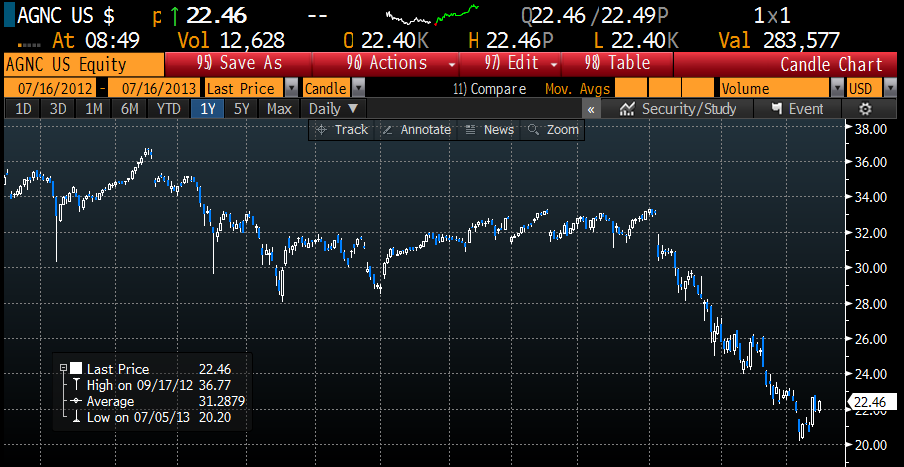
Re Bernanke’s testimony, the Washington Post is saying the Fed will be delaying debate over unwinding QE amid concerns over how the markets will react. One interesting concern, from Richmond Fed Jeffrey Lacker, is that the Fed will experience capital losses on its holdings of mortgage backed securities, and could find itself in a position where it makes no money (or even experiences losses), which will raise public and Congressional scrutiny. Want a proxy for the Fed’s balance sheet?  Take a gander at the chart of Agency Mortgage REIT American Capital (AGNC). They hold a levered portfolio of agency fixed and adjustable rate mortgage backed securities. The stock is down a third since rates started going up in early May.


Mortgage REITs like AGNC or Annaly (NLY)  are unloading mortgage-backed securities as rates increase. This is largely due to margin requirements, although interest rate hedging plays a part. As the value of their holdings drops, which is what is happening as rates increase, the banks that provide them leverage will demand more capital. The REITs can either raise capital in the private markets (which isn’t going to happen) or they can raise capital by selling their inventory. The thing to remember is that the margin clerk doesn’t care if the mortgage backed securities are overvalued or undervalued. The margin clerk will hit whatever bid is available if the company doesn’t sell the merchandise themselves. That is how you get these air pockets like we had on July 5, where the we set record highs on mortgage rates and the 10 year yields. As mortgage REITs de-lever, you can expect rate volatility. Floating in this environment can be a little hairy. 
 
CoreLogic’s latest Market Pulse makes the argument that in spite of the recent rise in house prices and rates, housing affordability is still elevated compared to historical numbers. They dismiss (as do I) the notion that we are back in a bubble or are even close to one. Bubbles are psychological events where everyone gets this idea that an asset price cannot fall. We will not experience another real estate bubble, although our great-grandkids might. Here is Corelogic’s chart on affordability:


Based on the weak retail sales numbers yesterday (headline +4% vs expectations of +.8%, ex-autos flat vs expectations of + .5%), a number of sell-side firms took down their 2Q GDP estimates a hair. We will get the preliminary estimate of 2Q GDP in a couple of weeks.
 
Freddie Mac’s mid-year update gives a forecast for the rest of 2013. Punch line: home price appreciation will slow, but remain positive, the labor market will continue the pace of the first half of the year, home sales up 2% and starts up 12% from the first half, and mortgage rates will continue to rise. Will the rise in mortgage rates stall the housing recovery? They anticipate it won’t, because affordability still remains high.

Morning Report – Earnings Season 7/15/13

Vital Statistics:

  Last Change Percent
S&P Futures  1674.0 3.7 0.22%
Eurostoxx Index 2680.7 5.8 0.22%
Oil (WTI) 105 -1.0 -0.92%
LIBOR 0.268 0.000 0.00%
US Dollar Index (DXY) 83.4 0.416 0.50%
10 Year Govt Bond Yield 2.63% 0.05%  
Current Coupon Ginnie Mae TBA 101.6 0.1  
Current Coupon Fannie Mae TBA 99.95 -0.4  
RPX Composite Real Estate Index 203 -0.2  
BankRate 30 Year Fixed Rate Mortgage 4.48    


Markets are higher on no real news. The NY Empire Manufacturing Survey came in higher than expected, while retail sales were weaker. Citi’s 2Q numbers beat estimates. Bonds and MBS are flattish.
 
Lots of data this week, punctuated by the Bernank’s testimony on Wed in front of the House Financial Services Committee. On Tues, we have the Consumer Price Index; now that QE4EVA is officially done with, inflation numbers are becoming relevant again. We will also get capacity utilization, industrial production, and homebuilder sentiment. Wednesday, we get housing starts and building permits, Thursday is Philly Fed, and Leading Economic Indicators. 
 
Last week’s rally in bonds was probably due to an overshoot on the jobs report after the 4th. We saw the average 30 year mortgage rate hit 4.64% on Friday, July 5 and the 10 year hit 2.74%. It looks like a lot of the Street took a 4 day weekend, so the market was illiquid and you had forced REIT selling in a thin market. While rates can certainly go higher, I would almost put an asterisk on those prices. I would be looking for a trading range in the 10 year of 2.45% – 2.65%. 
 
While earnings season officially started last week, it begins in earnest tomorrow. Heavyweights like Coca Cola, Goldman, American Express, IBM, Intel, Microsoft, Google, and GE will report this week. With the stock market at record highs, it is vulnerable to earnings disappointments. I would expect any sell-off in stocks to be bond bullish, but with the backdrop of ending QE, the effect may be modest.
 

Morning Report – Fed Unemployment Forecast 7/12/13

Vital Statistics:

  Last Change Percent
S&P Futures  1669.4 -0.7 -0.04%
Eurostoxx Index 2686.9 5.6 0.21%
Oil (WTI) 105.5 0.6 0.55%
LIBOR 0.268 -0.001 -0.19%
US Dollar Index (DXY) 83.05 0.306 0.37%
10 Year Govt Bond Yield 2.55% -0.03%  
Current Coupon Ginnie Mae TBA 103.9 0.8  
Current Coupon Fannie Mae TBA 103.4 0.1  
RPX Composite Real Estate Index 203 -0.2  
BankRate 30 Year Fixed Rate Mortgage 4.52    


Markets are flat this morning after yesterday’s big rally and good earnings reports from JP Morgan and Wells Fargo were offset by a miss from UPS. Bonds and MBS are up small.
 
The Producer Price Index (a measure of inflation at the wholesale level) increased .8% in June, but that was primarily driven by high energy prices. The core came in at .2%. Both readings were ahead of expectations. At 10:00, we will get the preliminary University of Michigan Consumer Confidence Survey for July.
 
The thing that jumped out at me from the Fed Minutes was the downward revision in unemployment expectations. The Fed lowered the 2013 unemployment forecast from 7.4% to 7.25%, they took down 2014 from 6.85% to 6.65% and took down 2015 from 6.25% to 6%. Given that GDP was not revised materially upward leads me to believe that they believe the labor force participation rate will remain low, which could be a drag on the economy. The other thing is that the market has had the expectation that a hike in the Fed Funds rate is going to be a 2015 event. Given that the Fed has given a threshold number for raising the Fed Funds rate of 6.5%, we could be looking at a late 2014 / early 2015 tightening. 

Morning Report – jobs report aftermath 7/8/13

Vital Statistics:

  Last Change Percent
S&P Futures  1634.1 6.8 0.42%
Eurostoxx Index 2654.1 58.1 2.24%
Oil (WTI) 102.5 -0.7 -0.72%
LIBOR 0.269 -0.001 -0.48%
US Dollar Index (DXY) 84.31 -0.140 -0.17%
10 Year Govt Bond Yield 2.68% -0.06%  
Current Coupon Ginnie Mae TBA 102.6 0.1  
Current Coupon Fannie Mae TBA 102.5 0.4  
RPX Composite Real Estate Index 203.5 -0.7  
BankRate 30 Year Fixed Rate Mortgage 4.64    


Markets are higher this morning as European stock markets rally.  Bonds and MBS are up
 
Friday’s jobs report turned into a bloodbath for bonds. The 10 year yield jumped 24 bps, as did the average 30 year fixed rate mortgage. Nearly 200,000 jobs were added in June, while May and April were revised upward by 70,000. Goldman and JPM moved up their estimate for the start of FEXIT (Fed exit) to the Sep FOMC meeting from the Dec meeting.
 
Given the unofficial 4 day weekend, trading desks were understaffed on Friday, which means the markets may have overshot. Thin markets tend to be volatile markets.
 
The jobs report did a number on mortgage backed securities as well. The Fannie Mae 4s had their worst day since the whole sell-off began as they lost nearly 2 points. That explains why the average 30 year fixed rate mortgage increased by 24bps on Fri.
 
Chart: Fannie Mae August 4s TBA:


We don’t have much in the way of economic data this week, with the exception of the FOMC minutes on Wed. That is probably the only thing that would be market-moving this week. The Western MBA Secondary Conference is this week in San Francisco, so a lot of traders will be out there for that. 
 
Alcoa kicks off 2Q earnings season after the close. 
 
The MR will be spotty the rest of the week as I will be in SF for the secondary conference