Posted on August 7, 2013 by Brent Nyitray
Vital statistics
| |
Last |
Change |
Percent |
| S&P Futures |
1700.7 |
-1.8 |
-0.11% |
| Eurostoxx Index |
2811.4 |
2.4 |
0.08% |
| Oil (WTI) |
107 |
0.5 |
0.44% |
| LIBOR |
0.266 |
0.001 |
0.38% |
| US Dollar Index (DXY) |
81.74 |
-0.138 |
-0.17% |
| 10 Year Govt Bond Yield |
2.63% |
0.00% |
|
| Current Coupon Ginnie Mae TBA |
104.6 |
0.0 |
|
| Current Coupon Fannie Mae TBA |
103.9 |
0.1 |
|
| RPX Composite Real Estate Index |
200.7 |
-0.2 |
|
| BankRate 30 Year Fixed Rate Mortgage |
4.37 |
|
|
Stocks are lower this morning on no real news. August is usually a slow month, so you often see big moves on no real volume, or without any important reason. Bonds and MBS are up.
Mortgage Applications rose last week for the first time in two months. The purchase index was up small while the refi index fell slightly.
Obama laid out his housing plan in a
speech yesterday. There was nothing major in it, with the exception that he wants to tax mortgage backed securities to fund low-income housing. Supposedly this would replace explicit goals for lending to low income borrowers. So basically, it is euthanize Fan and Fred, beef up FHA, make the government a mortgage reinsuer, and impose an additional tax on mortgage backed securities.
Freddie Mac may do something about eminent domain.
No MR tomorrow of Friday
Filed under: Morning Report | 35 Comments »
Posted on August 6, 2013 by Brent Nyitray
Vital Statistics:
| |
Last |
Change |
Percent |
| S&P Futures |
1700.7 |
-1.8 |
-0.11% |
| Eurostoxx Index |
2811.4 |
2.4 |
0.08% |
| Oil (WTI) |
107 |
0.5 |
0.44% |
| LIBOR |
0.266 |
0.001 |
0.38% |
| US Dollar Index (DXY) |
81.74 |
-0.138 |
-0.17% |
| 10 Year Govt Bond Yield |
2.63% |
0.00% |
|
| Current Coupon Ginnie Mae TBA |
104.6 |
0.0 |
|
| Current Coupon Fannie Mae TBA |
103.9 |
0.0 |
|
| RPX Composite Real Estate Index |
200.7 |
-0.2 |
|
| BankRate 30 Year Fixed Rate Mortgage |
4.37 |
|
|
Markets are flattish on no real news. This week is relatively data-light. Bonds and MBS are flat.
Mortgage delinquencies rose 10% month over month in June,
according to Lender Processing Services, breaking a downtrend that has lasted since late last year. 700,000 people who made their May payment missed their June payment. Is this a blip or the start of a new trend? Interesting fact regarding geography – Non-current inventory is still close to peak levels in New York State (only down 5%). By contrast, California is down 59%, Arizona is down 66% and Nevada is down 47%. This explains why Northeast real estate prices are still bumping along the bottom of the bathtub while the Southwest is not.
Home prices
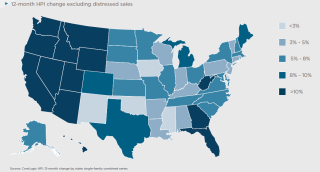
increased 11.9% year-over-year, according to CoreLogic. According to chief economist Dr. Mark Fleming: “In the first six months of 2013, the U.S. housing market appreciated a remarkable 10%. This trend in home price gains is at the best pace since 1977.” They are forecasting prices to increase 12.5% in July. You can see what markets are hot and what markets are not below:
There were some interesting observations out of mortgage REIT Invesco Mortgage Captial (IVR). They noted that spreads have widened on agency paper and believe there is good value here. They are taking the view that the spread widening is temporary and was due to a perfect storm of REIT de-leveraging, mutual fund outflows and dealers clearing inventory for quarter’s end. What does this mean to us? That mortgage rates have room to fall, even if the 10 year bond doesn’t move.
Filed under: Morning Report | 11 Comments »
Posted on August 5, 2013 by Brent Nyitray
Vital Statistics:
| |
Last |
Change |
Percent |
| S&P Futures |
1701.8 |
-2.2 |
-0.13% |
| Eurostoxx Index |
2807.7 |
-3.3 |
-0.12% |
| Oil (WTI) |
105.9 |
-1.0 |
-0.95% |
| LIBOR |
0.265 |
-0.001 |
-0.45% |
| US Dollar Index (DXY) |
81.99 |
0.077 |
0.09% |
| 10 Year Govt Bond Yield |
2.62% |
0.03% |
|
| Current Coupon Ginnie Mae TBA |
104.6 |
-0.1 |
|
| Current Coupon Fannie Mae TBA |
103.8 |
-0.2 |
|
| RPX Composite Real Estate Index |
200.7 |
-0.2 |
|
| BankRate 30 Year Fixed Rate Mortgage |
4.38 |
|
|
Markets are flattish after a wild week with an unexpectedly strong GDP report, a dovish FOMC statement, and a disappointing jobs report. This week is very data-light, so I don’t expect a whole lot of movement. We do have some Treasury auctions this week, but I don’t see that as market moving. Bonds and MBS are down small.
The 10 year traded in a range of 2.57% to 2.74%. So far, it is looking like 2.74% is acting as resistance.
Another data point showing the first time homebuyer is being put off by higher rates – Beazer Homes announced a drop in orders as traffic has slowed due to higher interest rates. So far we have seen drops in orders from Pulte and Beazer – both geographically diverse builders with an emphasis on lower price points.
Filed under: Morning Report | 47 Comments »
Posted on August 2, 2013 by Brent Nyitray
Vital Statistics:
| |
Last |
Change |
Percent |
| S&P Futures |
1698.2 |
-2.0 |
-0.12% |
| Eurostoxx Index |
2801.2 |
-7.4 |
-0.26% |
| Oil (WTI) |
107.4 |
-0.5 |
-0.42% |
| LIBOR |
0.267 |
0.001 |
0.38% |
| US Dollar Index (DXY) |
82 |
-0.336 |
-0.41% |
| 10 Year Govt Bond Yield |
2.61% |
-0.09% |
|
| Current Coupon Ginnie Mae TBA |
104.3 |
0.6 |
|
| Current Coupon Fannie Mae TBA |
103.8 |
0.6 |
|
| RPX Composite Real Estate Index |
200.7 |
-0.2 |
|
| BankRate 30 Year Fixed Rate Mortgage |
4.46 |
|
|
If you went to sleep just before Wednesday’s GDP report and just rolled out of bed, you would be forgiven for asking what all the hoopla is about. If not, you would be suggesting that Webster’s put the 3 day intraday chart of the 10-year bond yield as the illustration for the word “whipsaw.”
Bonds are rallying hard after a weak jobs report. Stocks are selling off as well. TBAs are up 3/4 of a point.
The
July jobs report sent yields down 14 basis points (yes) on disappointing numbers. 162,000 jobs were added in July, and June was revised downward. The unemployment rate fell from 7.6% to 7.4% as the labor force participation rate dropped from 63.5% to 63.4%. Hourly earnings ticked down month-over-month and weekly hours fell. Overall, a “meh” report, with the caveat that summertime jobs reports tend to be volatile and no matter how hard the Bureau tries to make seasonal adjustments for all the things going on (seasonal work, students, teachers, etc) it is a difficult task.
Given that GDP growth has averaged about 1% over the past 3 quarters and the labor market is improving at a snail’s pace, it makes you wonder what the Fed is thinking about when they say they want to taper this fall.
The Fed seems to alternate between characterizing growth as “modest” and “moderate.” Ever wonder what the line between the two is?
The WSJ attempts to parse.
Filed under: Morning Report | 21 Comments »
Posted on August 1, 2013 by Brent Nyitray
Vital Statistics:
| |
Last |
Change |
Percent |
| S&P Futures |
1692.9 |
12.4 |
0.74% |
| Eurostoxx Index |
2797.4 |
29.2 |
1.06% |
| Oil (WTI) |
106.9 |
1.9 |
1.82% |
| LIBOR |
0.266 |
0.000 |
0.00% |
| US Dollar Index (DXY) |
82.06 |
0.605 |
0.74% |
| 10 Year Govt Bond Yield |
2.63% |
0.06% |
|
| Current Coupon Ginnie Mae TBA |
104.3 |
-0.2 |
|
| Current Coupon Fannie Mae TBA |
103.7 |
-0.3 |
|
| RPX Composite Real Estate Index |
200.7 |
-0.2 |
|
| BankRate 30 Year Fixed Rate Mortgage |
4.39 |
|
|
Stock markets are higher after a dovish FOMC statement yesterday and lower than expected initial jobless claims. Bond and MBS are down.
The FOMC statement was interpreted as dovish yesterday. There wasn’t any discussion of tapering, as the Fed seemed to go back to its older language that said QE could increase or decrease depending on the data. They are forecasting that the economy will improve through the second half of the year. The only other notable change was that they reaffirmed the risks of dis-inflation, which was enough to get previous dissenter James Bullard back in the fold.
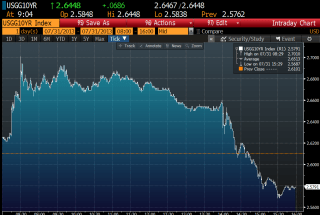
The 10 year had sold off hard on the ADP jobs number and the GDP number, but it rallied hard after the statement. The range was 2.57% to 2.7%. You can see just how big the swing was below:
The final shoe to drop will be the jobs report on Friday.
The Case-Shiller
first quarter report is out. Most of the info is old news, but some is not. CoreLogic is forecasting that prices increase 6.5% year over year over the next 12 months. Over the next 5 years, they expect prices to increase at a 4% per year rate. The usual suspected – Phoenix, Sacramento, etc are leading the charge. Bringing up the rear are Long Island, Hartford, Edison NJ, Kansas City, and Newark.
Filed under: Morning Report | 27 Comments »
Posted on July 31, 2013 by Brent Nyitray
Vital Statistics:
| |
Last |
Change |
Percent |
| S&P Futures |
1683.3 |
-1.4 |
-0.08% |
| Eurostoxx Index |
2755.1 |
-4.1 |
-0.15% |
| Oil (WTI) |
103.6 |
0.5 |
0.46% |
| LIBOR |
0.266 |
0.001 |
0.23% |
| US Dollar Index (DXY) |
82.12 |
0.290 |
0.35% |
| 10 Year Govt Bond Yield |
2.68% |
0.07% |
|
| Current Coupon Ginnie Mae TBA |
103.8 |
-0.4 |
|
| Current Coupon Fannie Mae TBA |
103.3 |
-0.4 |
|
| RPX Composite Real Estate Index |
200.7 |
-0.2 |
|
| BankRate 30 Year Fixed Rate Mortgage |
4.36 |
|
|
Markets are slightly better after some good economic data. At 2:00 pm we will get the FOMC decision. Mortgage Applications fell. Bonds and MBS are getting beaten up on the good data.
The ADP jobs report showed the private sector added 200k jobs in July, and June was revised upward to 198k. The ADP report is supposed to mimic the final jobs number, not the advance estimate we will get on Friday.
The advance estimate of second quarter GDP growth came in at + 1.7% This was higher than the 1% estimate. First quarter GDP was revised down by a lot… from + 1.8% to + 1.1%. That said, it looks like the growth came from inventory build as consumer spending cooled. If spending doesn’t rebound, that will depress growth in the future.
Count Richmond California as the next locality threatening to use eminent domain to seize mortgages. Unsurprisingly, SIFMA (the Securities Industry Financial Markets Association) which runs the TBA market
condemned the idea. SIFMA told San Bernardino that if they proceeded down the eminent domain path, that mortgages originated in that jurisdiction would become ineligible for TBA trading. This would effectively cut off the locality from Ginnie Mae and Fannie / Freddie loans. Which is 90% of the mortgage market. FHFA nominee Mel Watt has taken a pass on the whole eminent domain issue, which is yet another reason why he faces an uphill battle for confirmation.
Filed under: Morning Report | 27 Comments »
Posted on July 30, 2013 by Brent Nyitray
Vital Statistics:
| |
Last |
Change |
Percent |
| S&P Futures |
1686.8 |
4.3 |
0.26% |
| Eurostoxx Index |
2760.1 |
18.3 |
0.67% |
| Oil (WTI) |
103.9 |
-0.6 |
-0.60% |
| LIBOR |
0.265 |
-0.001 |
-0.38% |
| US Dollar Index (DXY) |
81.66 |
0.000 |
0.00% |
| 10 Year Govt Bond Yield |
2.58% |
-0.02% |
|
| Current Coupon Ginnie Mae TBA |
104.3 |
-0.1 |
|
| Current Coupon Fannie Mae TBA |
103.9 |
0.1 |
|
| RPX Composite Real Estate Index |
200.7 |
-0.2 |
|
| BankRate 30 Year Fixed Rate Mortgage |
4.36 |
|
|
Markets are higher this morning on no real news. Bonds and MBS are up
The S&P / Case-Shiller
home price index rose 1.05% month over month and 12.2% year over year in May. The usual suspects (Phoenix, Lost Wages, and San Francisco) showed 20%+ gains while the Midwest and East Coast showed low / mid single digit increases. New York brought up the rear with a 3.3% increase. This has been borne out by the homebuilders, where the ones with a heavy West Coast focus have outperformed the ones that are East Coast / diversified.
Mortgage REIT American Capital Agency (AGNC) reported second quarter earnings last night. Book value got hit by 12%, but the interesting data point is the state of their TBA portfolio. The To-Be-Announced (or TBA) market is what sets mortgage rates. Over the second quarter, their TBA portfolio fell from 27.5 billion to 14.5 billion. That is a lot of paper they just dumped. They consider themselves to be positioned where they want to be at this point from a duration hedging standpoint. The key takeaway – we’ll have to see what Annaly (NLY) has to say, but so far, it appears that a substantial chunk of the selling in the TBA market is done. That is good news for mortgage rates, and I wouldn’t fall out of my chair with shock to see lower mortgage rates in the context of a stable 10-year.
Completed foreclosures were 55,000 in June, down 20% year over year and up 2.5% from May, according to CoreLogic. Approximately 1 million homes in the U.S. were in some stage of the foreclosure process, compared to 1.4 million a year ago. This represents 2.5% of all homes with a mortgage. The states with the most work left to do are Florida (8.6%), New Jersey (6%), New York (4.8%), Connecticut (4.2%) and Maine (4.1%).
Filed under: Morning Report | 48 Comments »
Posted on July 29, 2013 by Brent Nyitray
Vital Statistics:
| |
Last |
Change |
Percent |
| S&P Futures |
1683.4 |
-3.2 |
-0.19% |
| Eurostoxx Index |
2748.6 |
6.6 |
0.24% |
| Oil (WTI) |
105.1 |
0.4 |
0.37% |
| LIBOR |
0.266 |
0.001 |
0.38% |
| US Dollar Index (DXY) |
81.71 |
0.050 |
0.06% |
| 10 Year Govt Bond Yield |
2.58% |
0.02% |
|
| Current Coupon Ginnie Mae TBA |
104.4 |
0.1 |
|
| Current Coupon Fannie Mae TBA |
103.8 |
-0.1 |
|
| RPX Composite Real Estate Index |
200.7 |
-0.2 |
|
| BankRate 30 Year Fixed Rate Mortgage |
4.35 |
|
|
Markets are down this morning as we head into a data-intensive week. Merger Mondays are back with a few big transactions. Bonds and MBS are down small.
We have 3 big events in bonds this week – first we have the FOMC meeting on Tues and Wed. The FOMC statement will undoubtedly be parsed very closely. We will also get the advance estimate of 2Q GDP on Wed. Finally, on Friday we get the jobs report. So lots of potential market-moving stuff towards the back end of the week.
There is a lot of discussion over who will be the next Fed Chairman after Bernanke’s term is finished in January. Bernanke has said he doesn’t want the job anymore. The two names mentioned are Janet Yellen and Larry Summers. Given that Summers hasn’t even done a stint as a Fed governor, he would be a surprising pick. This looks like so much theater. The next Fed Head will be Yellen. Yellen is an even bigger dove than Bernanke, so keep that in the back of your mind when you think about taper timing.
This week we will have a lot of earnings reports from the mortgage REITs. While we expect to see declining book values, the more interesting data will involve how much the REITs have de-leveraged. Some have done nothing (Capstead). Others have sold paper and still have increased leverage ratios because the value of their portfolio has dropped. What we hear from the REITs will tell us a lot about how much selling remains to be done in the MBS market, and that will tell us which way we want to lean with rates.
Filed under: Morning Report | 39 Comments »
Posted on July 26, 2013 by Brent Nyitray
Vital Statistics:
| |
Last |
Change |
Percent |
| S&P Futures |
1675.5 |
-8.5 |
-0.50% |
| Eurostoxx Index |
2744.8 |
4.5 |
0.16% |
| Oil (WTI) |
104.4 |
-1.1 |
-1.03% |
| LIBOR |
0.265 |
0.001 |
0.45% |
| US Dollar Index (DXY) |
81.77 |
-0.203 |
-0.25% |
| 10 Year Govt Bond Yield |
2.55% |
-0.02% |
|
| Current Coupon Ginnie Mae TBA |
104.5 |
0.2 |
|
| Current Coupon Fannie Mae TBA |
104 |
0.1 |
|
| RPX Composite Real Estate Index |
200.7 |
-0.2 |
|
| BankRate 30 Year Fixed Rate Mortgage |
4.38 |
|
|
Markets are lower on no real news. Bonds and MBS are up small.
There isn’t much in the way of economic data this morning. I would expect activity to dwindle as most of the Street will be on the L.I.E. by noon.
Yesterday was a big day for real estate-related earnings – we heard from three homebuilders – Meritage, D.R. Horton, and Pulte. As far as the question “Has higher mortgage rates affected traffic and purchase activity?” goes, the answer is yes, at least in some areas. Meritage (who is primarily in the West / Southwest) noted an increase in orders, as did Pulte. Pulte noted that buyers still have a “sense of urgency.” On the other hand, D.R. Horton, which is more geographically diversified reported a decrease in orders. That was huge. D.R. Horton said that buyers are “alarmed” at the rapid rise in rates and it has affected sales. I guess it makes sense when you think about it – on the West Coast, inventory is depleted and prices are rising at double digit rates. So it would make sense that buyers would feel a sense of urgency – the fear is not being able to find a house. Elsewhere in the country, with prices flat / up small, that doesn’t exist. Horton is at the lower price points as well, so maybe you are starting to get into DTI issues with first time homebuyers. Anyway, the increase in rates is starting to bite as far as purchase activity goes.
Filed under: Morning Report | 39 Comments »
Posted on July 25, 2013 by Brent Nyitray
Vital Statistics:
| |
Last
|
Change
|
Percent
|
|
S&P Futures
|
1678.3
|
-5.5
|
-0.33%
|
|
Eurostoxx Index
|
2728.3
|
-24.0
|
-0.87%
|
|
Oil (WTI)
|
104.6
|
-0.8
|
-0.77%
|
|
LIBOR
|
0.264
|
-0.001
|
-0.19%
|
|
US Dollar Index (DXY)
|
82.06
|
-0.230
|
-0.28%
|
|
10 Year Govt Bond Yield
|
2.59%
|
0.01%
|
|
|
Current Coupon Ginnie Mae TBA
|
104.2
|
-0.2
|
|
|
Current Coupon Fannie Mae TBA
|
103.7
|
0.0
|
|
|
RPX Composite Real Estate Index
|
200.7
|
-0.2
|
|
|
BankRate 30 Year Fixed Rate Mortgage
|
4.39
|
|
|
Markets are lower in spite of some strong earnings reports and a decent durable goods report. Initial Jobless claims were 343k. Bonds and MBS are down small / flat.
Mortgage REIT Hatteras Financial released earnings yesterday, and reported a 20% drop in book value. Hatteras invests in agency ARM product, so it is on the slightly more esoteric side, but they made one interesting observation: The MBS market (and the 7/1 ARM market in particular) suffered a powerful sell-off in the last two weeks of June, and has yet to bounce back. So it wasn’t simply end-of-quarter liquidation. What does this mean for us? That non-QE supported MBS spreads are finding new levels. What does that mean in English? That once QE ends, we may find the TBA market experiencing the same thing – a permanent increase in spreads, which means higher rates, even if the 10 year bond doesn’t move. Make hay now….
More than half the mortgage modified in 2009 under the Home Affordability Modification Program (HAMP) have defaulted, according to a report from the Special Inspector General for the Troubled Asset Relief Program (SIGTARP). This report will certainly make a push for HARP 3.0 even more difficult. Interesting fact: of the $38.5 billion allocated to housing support programs in 2009, only 22% (or about $8.6 billion) has even been spent.
The Detroit bankruptcy is going to be interesting for municipal bonds, especially GOs (general obligations). There are two types of muni bonds – revenue bonds, where the principal and interest is paid for by some project (like a bridge) and general obligation bonds, where interest is paid for out of general revenues. Liquidity in munis is terrible to begin with – banks won’t hold them as inventory because they aren’t allowed to take the tax deduction on the interest payments, so nobody will make a market in them. Retail holders of these bonds may find themselves unable to sell. If banks won’t buy them, then who will buy these things? Hedge funds, who are buying them with an eye towards going to the mat in bankruptcy court. And they aren’t paying par. They probably care in the 40s.
Filed under: Morning Report | Leave a comment »


 Brent Nyitray
 Fairlington Blade
 Let the mutherfuker burn!
 jnc4p
 Kevin S. Willis
 Michigoose
 lmsinca
 markinaustin
 Arcanaut
 novahockey
 quarterback
 ScottC
 yellojkt


