Morning Report: Productivity and Quantitative Tightening 9/2/15


Stocks are higher this morning after Chinese markets rallied to almost unchanged after an early swoon. Bonds and MBS are down.

Mortgage Applications rose 11.3% last week as purchases rose 4.1% and refis rose 16.8%. The 30 year fixed rate mortgage was steady at 4.08%. While the bond market has been pretty volatile, TBAs have been much more steady, tending to fade the moves of the bond market. This means you might see a big drop in the 10 year yield, hope to lock at a great rate, only to find that rates are lower, but not as much as the big move in Treasuries would suggest.

The ADP jobs report showed payrolls increasing by 190,000 jobs, which is less than forecast. July was revised lower as well. The Street is forecasting an increase of 218,000 in the official report on Friday.

After a couple big quarters, unit labor costs fell in the second quarter by 1.4%. This number tends to be volatile, as does productivity. The Fed pays close attention to these numbers.

The ISM New York Index fell pretty dramatically in August, from 68.8 to 51.1. The 68.8 reading was unusually good, while the 51.1 reading was unusually bad.

Factory orders rose 0.4% in July, lower than the 0.9% forecast. Ex-transportation, factory orders fell 0.6%.

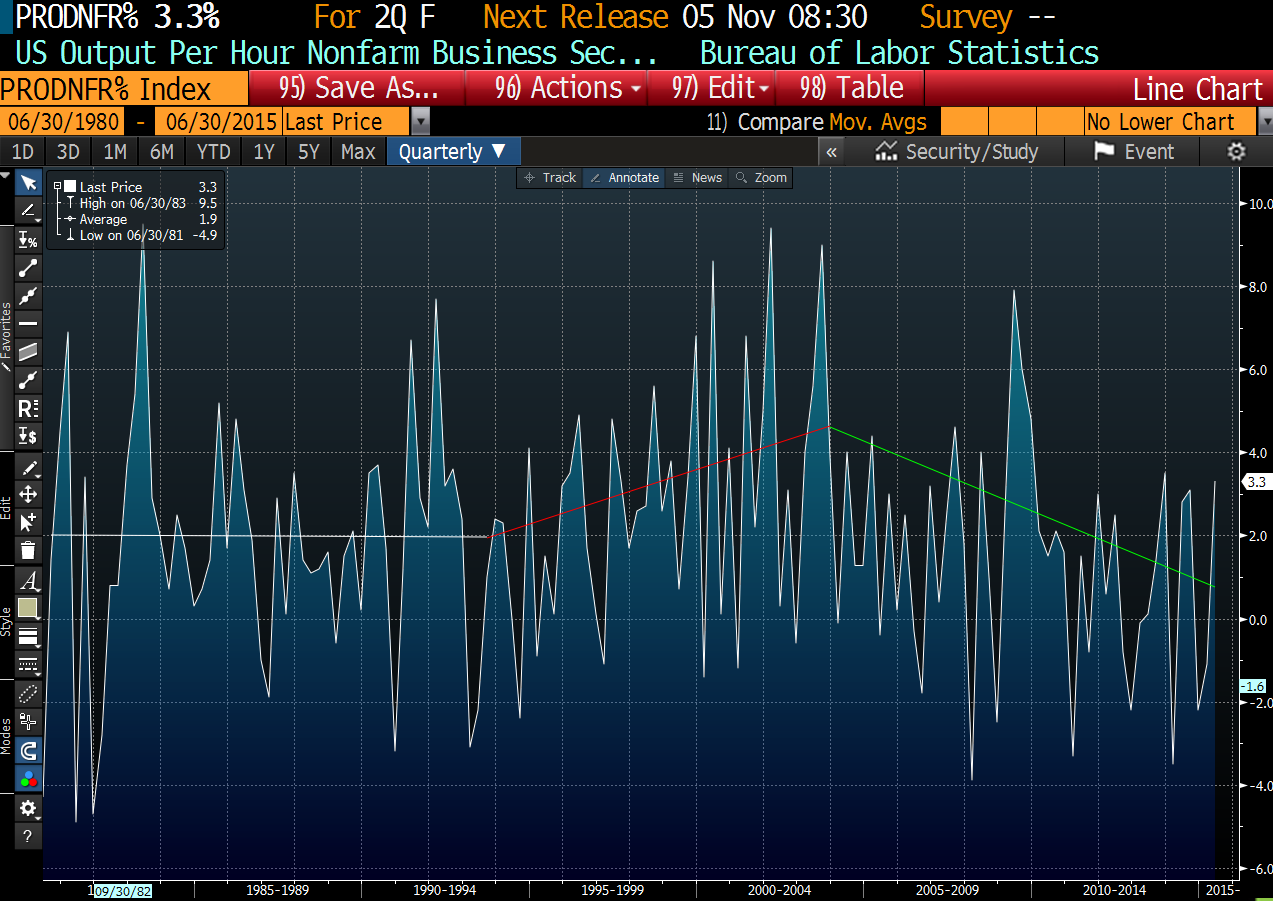
Productivity rebounded in the second quarter to an annualized rate of 3.3%. Overall, productivity growth has been in a downtrend for the past dozen years or so. This is one reason why wage inflation has been so hard to come by – productivity growth has been declining. Take a look at the chart below. You can see productivity flatlining around 2% in the 1980s, then a big acceleration in the 1990s as the personal computer goes from a glorified typewriter to an indispensible tool on everyone’s desk. That continues into the early 00s as the internet helps business become more productive. Finally, you see the decline as the PC and Internet phenomenons become played out. While the mainstream media mocked Jeb Bush for talking up the importance of productivity, he was right.
Is “quantitative tightening” the new buzzword? Not yet, but as central banks worldwide begin to let go of some of their reserves, it may become more common. For the past two decades, central banks (especially China) have been accumulating reserves as they manage their trade balances and their currencies. The net effect has been a bid under Treasuries and a release of money into the system. As China slows, this is reversing as they sell Treasuries to support their currency. When they sell Treasuries, they put pressure on US interest rates and the withdrawal of liquidity acts like a tightening. Punch line: this is the second-order effect of the global slowdown – you might see upward pressure on interest rates, a rising dollar, and a withdrawal of liquidity. This would compound the effect of any Fed tightening. Which means a bumpier road ahead as the Fed pursues normalization. This might explain why the Fed has chosen to not sell (and even to keep re-investing) its portfolio of Treasuries and MBS that it bought during QE.

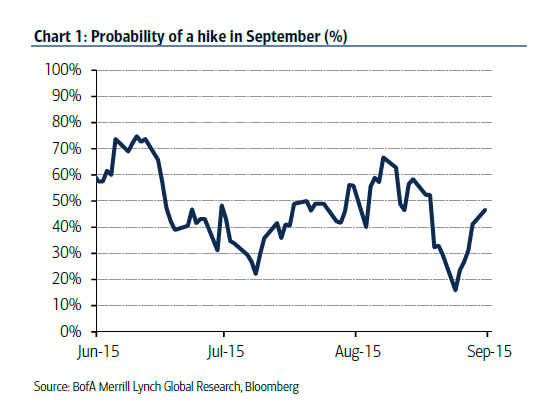
As world markets recover from last week’s bloodbath, the probability of as Sep rate hike is increasing.
Morning Report: Chinese Treasury sales 9/1/15

Stocks are lower this morning on global growth fears. Bonds and MBS are up.

IMF Managing Director Christine Lagarde said that global growth will likely remain weaker than the IMF was projecting two months ago. Chinese manufacturing fell to a 3 year low.

China continues to sell US Treasuries in order to support its currency. There has been a fear that China could take down the US by dumping Treasuries and pushing up interest rates here. In reality, the US has more leverage here. China’s economy is beginning to soften, and the last thing they would want to do is injure their biggest customer. Second, Japan would gladly take China’s supply of Treasuries. Third, the article mentions that China has no better alternatives than US Treasuries to stash a trillion dollars. Actually I think that is wrong. The proceeds will go to pay off domestic debt pledged against falling asset prices within China.

The ISM Manufacturing Survey fell to 51.5 in August, missing the Street expectation of 52.5. Prices paid fell from 44 to 39.

Economic Optimism took a big hit in August as well, as the index fell from 46.9 to 42, missing the Street expectation of 47.1 by a country mile.

Constructions spending rose 0.7% in July and June was revised upward from 0.1% to 0.7%.

Obama threw a bone to organized labor as his National Labor Relations Board ruled that companies that use contractors are considered joint employers. This makes parent companies liable for how their subcontractors treat their employees and also is intended to make it easier for unions to get a foothold in the big fast food chains. Who else has to worry about this? The homebuilding industry, which uses a lot of contract labor and has since the 1980s. “Are we concerned that this ruling might have some impact? I think we are alert to the ruling. We are aware that the Labor Department feels its mandate is broad, but we think that our business is highly differentiated from what’s being discussed in the current case or even extensions,” said Stuart Miller, CEO of Miami-based Lennar. Given how much homebuilding means to the overall economy, depressing the sector even further is not really what the economy needs at the moment. And the lack of housing supply leads to…

Higher prices and low affordability. The CoreLogic Home Price Index rose 1.7% in July, which is up 6.9% year over year. Prices remain 6.6% below their August 2006 peak.

Morning Report: China stops supporting its stock market bubble 8/31/15

Stocks are lower this morning on overseas weakness. Bonds and MBS are up. Slow news day.

China has given up on using state funds to support its stock market. The government has spent about $200 billion trying to support the stock market.

The highlight of the week will be the jobs report on Friday. This will be the last jobs report ahead of the September FOMC meeting. After last week’s market sell-off, the Fed Fund futures contracts took their assessment of a Sep hike from around 50% to about 30%.

Aside from the jobs report, we have some important economic data this week with the ISM surveys and construction spending. That said, the jobs report will be the big event.

The ISM Milwaukee Index came in at 47.67, a bit lower than expectations.

The Chicago Purchasing Manager’s index was almost flat at 54.4.

Stanley Fischer made some hawkish comments in Jackson Hole on Friday, which is what stopped the rally in stocks.

I had a long interview with Louis Amaya on his Capital Markets Today show. You can access it here. I discuss the economy, real estate, the Fed and China. The interview starts at the 3 minute mark.

Morning Report: Volatility isn’t going to influence the Fed much 8/28/15

Stocks are taking a breather after a big two-day rally. Bonds and MBS are up.

Personal Income rose 0.4% in July, in line with expectations. Personal Spending rose 0.3%. The Core PCE Index (The Fed’s preferred measure of inflation) rose at 1.2% YOY. Nice to see a little wage inflation. On the other hand, the low PCE inflation is going to worry the Fed.

Note that the National Labor Relations Board just issued a pro-union decision to make a company that hires a temporary agency for workers a joint employer. This will supposedly make it easier for workers to unionize and it makes the ultimate employer liable for what happens to temps. This was considered a big win for the unions. Does it ultimately result in higher wages, or simply more campaign cash for Democrats? I am betting on the latter.

St. Louis Fed Head James Bullard says that the recent volatility in the markets isn’t going to be much of a factor in the FOMC’s decision-making next month. The Fed Funds futures however discounted the probability of a Sep rate hike from about 50% to about 30%.

Pending Home Sales rose 0.5% in July. The real estate market is inching better, but tight supply and affordability issues are holding things back a little.

Consumer sentiment fell in August, according to the University of Michigan. The 91.9 reading came in below expectations.

Morning Report – Strong Q2 GDP 8/27/15

Markets are higher this morning as yesterday’s rally held and was followed throughout the world. Bonds and MBS are down.

Second quarter GDP was revised upward to 3.7%, a strong reading. Consumption rose 3.1%, and the core personal consumption expenditure inflation index rose 1.8%. After seeing these numbers, it is easy to see why the Fed was looking to hike rates in September. That was before the global financial market sell-off. The September jobs report next week will be huge.

Initial Jobless Claims fell slightly to 271k, as we sit at more or less record lows.

The Bloomberg Consumer Comfort Index rose to 42 from 41.1 last week. Roughly 1/3 feel positive about the economy, while 54% feel positive about their personal finances.

The sell-off in stocks has been dramatic – in fact the last time we saw this big of a downward move over several days was 1940. The more interesting market has been bonds, which have barely benefited from the big drop downward, and gave up all of those gains almost immediately. The US dollar has been getting whacked during this sell-off as well, which means foreign money is dumping Treasuries. It probably is the petro-economy states doing it, however I have been hearing rumblings of Chinese selling. Whether this is a new dynamic in the market or not remains to be seen, however the action in the 10-year feels like the path of least resistance is now down in price / up in yield.

The Washington Post has another article talking about how stocks are “rigged” based on trading on Monday. Yes, stocks were all over the place, however the structure of the market has fundamentally changed as a result of technology and regulation. There used to be professional market makers for NASDAQ stocks and the specialist on the floor of the NYSE that would be the buyer when everyone else is selling. On days like Monday, they would lose money, but make up for it in normal trading, by selling a stock 1/8 or 1/16 above where they were willing to buy it. Nowadays, with sub-penny spreads, the market maker will never make back losses on days like Monday, so they no longer do it. The only ones left are the high frequency traders, who may or may not be liquidity providers. Stocks aren’t “rigged” – investors are getting what they pay for.

Ray Dalio (of Bridgewater) explains why the Fed may hike rates a quarter of a point or so before launching QE4. His point is that there are two cycles to pay attention to: the first, which is the shorter term cyclical economy that lasts a decade or so versus the long-term cycle, which lasts closer to a century. He is making the argument that the Fed is probably going to do another big easing before the big tightening. This tightening might be 25 or 50 basis points, which he doesn’t consider a major tightening. The Fed is focused on the classic recession – expansion phase which began in 2005 and is more or less where we are today. Dalio believes we are at the end of a debt supercycle, and the last time we went through a debt supercycle deleveraging period was in the 1930s. And while US corporations (and households to a large extent) have gone through a major deleveraging, the rest of the world has not – especially China, which is just entering their deleveraging phase. Interestingly, these supercycles are not new – even the Bible refers to them as 50 year cycles followed by a massive forgiveness (called jubilees, even though they aren’t all that much fun).

Morning Report: Consensus shifting rapidly on a rate hike 8/26/15

Green on the screen again this morning as stocks try to rebound. Yesterday, stocks traded up early only to give it all back late in the day and close with big losses. Bonds and MBS are falling again.

Durable Goods orders were strong at 2%, and June’s number was revised upward. Capital Goods Orders Non-defense, ex-air (a proxy for business capital investment) rose 2.2% versus a 0.3% expectation, while June was revised upward from 0.9% to 1.4%. These were the highest readings in a year.

Mortgage Applications rose 0.2% last week as purchases rose 1,7% and refis fell 1%. Surprising that refis fell given the 17 basis point drop in the 10 year, but it looked like TBAs (which set mortgage rates) largely ignored the move in the bond market.

Not sure what caused yesterday’s late day sell-off, but the S&P 500 made a 60 point swoon in the last hour of trading to close down 26 points.

The other interesting thing about this sell-off has been the fact that bonds have not reacted much to the sell-off. The flight to safety trade has been almost non-existent in Treasuries. Odd, since the sell-off has taken down the probability of a rate hike in September. In fact, many strategists are moving out their estimate for the first hike to 2016.

Larry Summers was arguing over the weekend that financial conditions are acting like a tightening, and therefore the Fed doesn’t really need to raise rates right now. Hotlanta Fed President Dennis Lockhart said that conditions in the financial markets have complicated the Fed’s decision. By any measure, inflation is nowhere to be found. Given the fear of replicating the 1937 mistake, the Fed is probably going to err on the side of caution. Aside from the psychological discomfort of having rates at 0%, what reason is there to raise rates?

The carnage in the stock markets in Asia have created some bargains. HTC (the cellphone maker) is trading at a discount to cash. Market cap of $39.7B, no debt, $47.2 billion of cash. Like buying dollar bills for 84 cents. In crisis, opportunity.

Morning Report: Green on the Screen as China cuts rates 8/25/15

Markets are higher this morning after the People’s Bank of China cut interest rates and required reserves. Bonds and MBS are down.

The Chinese Government is going back to the big levers to try and support asset prices – using rate cuts and reserve requirement cuts. They are also using pension fund money to buy stocks and have prohibited insiders and large investors from selling. John Hilsenrath from the Wall Street Journal described China this way: China is like a CDO. You don’t know what’s inside, how well it performs or where the leverage is until it’s under stress. I think that is a very apt description.

The FHFA House Price Index rose 0.2% in June, lower than expectations. The S&P Case-Shiller index of real estate prices fell 0.12% in June but is up 5% year-over-year.

New Home sales rose to an annualized pace of 507k in July, slightly lower than expectations. Surprisingly, consumer confidence rose in a big way to 101.5 from 91.

McMansion builder Toll Brothers reported numbers this morning which missed analyst estimates. Revenues and deliveries both declined. Average selling prices actually declined – first time we have seen that out of the builders. That said, signed contracts were up 30% in dollars and 12% in units as ASPs rise to $834k from $717k last year at this time. The stock is up half a buck pre-open, but then again pretty much everything is green this morning.

During the big sell-off in the markets, Treasuries only moved grudgingly higher. I had been reading that the Middle East (which is getting crushed by low oil prices) was selling the 10 year in a big way. Interestingly, TBAs and mortgage rates have been fading the move in the bond markets. People have been moving back their timing estimates for the first rate hike and bonds are not reacting much to it.

For those that are market history buffs, here is a cool chart showing the economy from the American Revolution through WWII.

Morning Report: Shades of 1937?

The #1 trending topic on Twitter is #BlackMonday.

The global stock market sell-off continues this morning, with S&P futures down 64 handles. Bonds and MBS are up small.

Markets sold off hard overnight, with Japan down 4.6%, China down 8.5%, and Europe generally down 4.5%. Commodities are getting clocked, with oil down to $39 a barrel. Emerging markets are getting crushed.

The Chicago Fed National Activity Index rebounded from -0.07 in June to 0.34 in July.

The sell-off in risky assets over the past week has pushed out the market’s forecast for the first rate hike out of the Fed. Futures are pricing in a first hike in the Dec – March timeframe. Over the weekend, Larry Summers penned an editorial in the Financial Times encouraging the Fed to stand pat for a while. He makes the point that the sell-off in assets has a tightening effect all by itself, and hiking rates in this disinflationary environment risks another 1937.

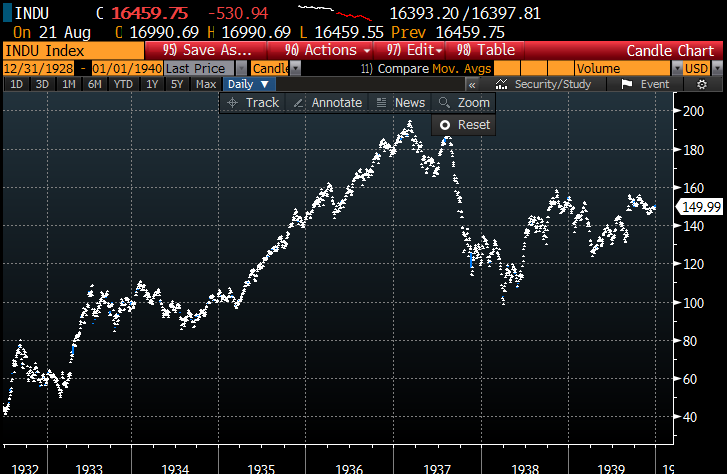
After stocks bottomed in 1932, the Dow Jones Industrial Average went on a tear, increasing almost fivefold in 5 years. In 1937, however they started a brutal 1 year bear market, where stocks got cut in half. The most common explanation for the sell-off was the Fed’s tightening in late 1936 and early 1937. Now, there are a lot of reasons for the sell-off in the 1930s (markets sensing something afoot in Europe, FDR’s undistributed profits tax, etc), but the Fed is very cognizant of their role in the “recession in the depression” and this will certainly guide their decision-making.

With stocks hitting air pockets on the downside, you would expect to see Treasuries flying. Yes, they are up, but not by as much as you would expect. Supposedly there has been massive supply of Treasuries coming out of the Middle East, which is keeping a lid on prices.

Morning Report: Is the Midwest making a comeback? 8/21/15

Stocks are lower this morning again after yesterday’s bloodbath. Bonds and MBS are up small.

Some people think the bond market’s strength is telling the Fed not to hike rates. I agree that bonds are pricing in the view that inflation is never, ever, ever going to come back. However, the US interest rate market is so manipulated by central banks (indeed all bond markets are these days) that I don’t think bond prices are the reliable signal they typically are.

Foreclosure inventory is down 24% year over year, according to Black Knight Financial Services. The delinquency rate has fallen to 2.2%, pretty much a post-crisis low.

Is the rust belt making a comeback? House prices are rising again in the Midwest as the auto industry recovers and the place becomes simply too cheap for business to ignore. Of course parts of the Midwest were ground zero for CRA lending, especially places like Detroit, which is filled with abandoned homes worth $10,000 with $100,000 mortgages on them. If you want to see what economic collapse looks like, check out this video of Toledo Ohio, my hometown. Most of these houses are worthless, and this is why I have always thought the fears of the big foreclosure inventory were overblown. These houses may count for the foreclosure numbers, but they certainly are not competing with anything and are probably never going to sell.

Morning Report: Not much clarity from the FOMC minutes 8/20/15

Stocks are lower this morning after Asian markets got roughed up overnight. Bonds and MBS are up.

Initial Jobless Claims came in at 277k, a bit higher than expected but still at or close to 4 decade lows. The Bloomberg Consumer Comfort Index rose to 41.1.

Existing Home Sales rose to 5.59 million in July from 5,48 million. The median home price rose 5.6% YOY to $234,000. This puts the median house price to median income ratio around 4.3x, which is higher than historical averages. Distressed sales fell 2 percentage points YOY to 7%. First time homebuyers fell slightly to 28% from 29% a year ago. Investor purchases fell from 16% to 13% and days on market fell from 48 to 42. Unsold inventory is about 4.9 months’ worth, which indicates a tight market.

In other economic news, the Index of Leading Economic Indicators unexpectedly fell, while the Philthy Fed Index rose.

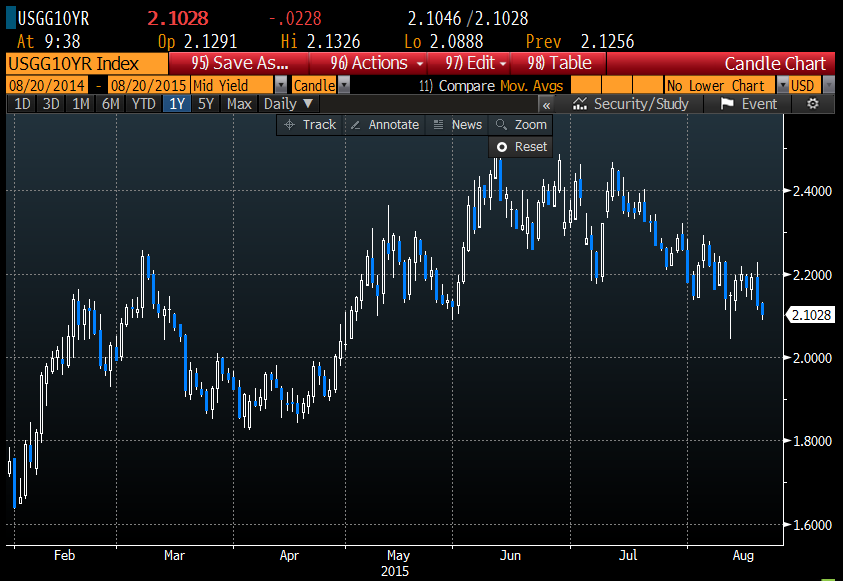
With the 10 year bond trading around 2.1%, we are at 3 – 4 month lows. Loan officers, you might want to ping any of your borrowers that are floating or who were on the fence for a refi.

The FOMC minutes didn’t really add any certainty to the September vs. December debate, however it did change the market’s perception of the probability of a rate hike from 50% to 36%. The key statement: “Most judged that the conditions for policy firming had not yet been achieved, but they noted that conditions were approaching that point.” The minutes address the labor market this way: (I bolded the interesting parts for emphasis)

“Participants agreed that labor market conditions had improved further, citing increases in payroll employment and job openings, the decrease in the unemployment rate, and some further reduction in broader measures of labor market underutilization. Although the labor force participation rate declined in June and the national hiring and quits rates were little changed in May, several participants noted that reports from business contacts in their Districts pointed to continued job gains and relatively strong labor markets. They cited anecdotal reports of firms having concerns about retaining workers and facing difficulties in filling even medium- and lower-skilled jobs. However, several participants contended that, despite the progress over the past few years, some noticeable margins of slack remained, citing as evidence the high number of workers not actively searching for jobs but available and interested in work as well as the high share of employees working part time for economic reasons compared with pre-recession levels.

The ongoing rise in labor demand still appeared not to have led to a broad-based firming of wage increases. While business contacts in a number of Districts continued to report that the pace of wage increases had picked up, recent national readings on hourly compensation and average hourly earnings of employees had remained subdued. The most recent employment cost index, released in April, had suggested an increase in wage gains. However, questions were raised about how to interpret this reading because the pickup was concentrated in the Northeast and might have resulted from particular factors that were not associated solely with a general tightening of labor market conditions, such as minimum wage adjustments and market conditions in certain occupations. In addition, it was noted that considerable uncertainty remained about when wages might begin to accelerate and whether that development might translate into increased price inflation.”

I found it interesting that filling lower-skilled jobs is difficult. If that is the case, then wages at the low end of the scale are going up, whether or not the government passes a new minimum wage law. (Of course the left is going to try and claim the minimum wage law did it, if wages do in fact rise). This would push the Fed to start hiking sooner rather than later. On the other hand, conditions in China and the fall in commodities (which they also mentioned) are going to naturally pull us towards a disinflationary scenario. The Fed does not foresee any sort of contagion from China, however they thought the same thing about the end of the subprime bubble. Punch line – not many people changed their forecasts after the minutes, and it is going to probably hinge on the August jobs report in a few weeks.

Zerohedge had an interesting oberservation: The Fed last hiked rates 110 months ago. Since then there have been 697 rate cuts around the world.

Did the Bernank get himself a new boat?