Posted on February 29, 2016 by Brent Nyitray
The ISM Milwaukee Index improved to 55.2 from 50.4, while the Chicago Purchasing Manager index fell to 47.6 from 55.6.
Originator and servicer Walter Investment reported lower than expected earnings this morning and the stock is down about 10%. for 2015, originations were up 36% and the servicing portfolio increased by 4%. In the fourth quarter, origination volume was up 8% YOY.
Walter wasn’t the only company to miss this morning: Ocwen also is down about 11% after missing its quarter. Delinquencies rose to 13.7% from 13.1%.
Filed under: Economy, Morning Report | 4 Comments »
Posted on February 25, 2016 by Brent Nyitray
Stocks are flat this morning on no real news. Bonds and MBS are up.
Initial Jobless Claims came in at 272k, an increase of 10k from last week.
Durable Goods orders rebounded smartly after a terrible December. They were up 4.9%, way better than the Street expectations.
Capital Goods orders rose 3.9% as well. Capital Goods orders are a proxy for business capital investment, so whatever turmoil is happening in the financial markets doesn’t seem to be affecting Main Street, at least not yet.
House prices rose 1.4% in the fourth quarter, according to the FHFA House Price Index. Home prices have now surpassed their bubble peaks and are making new highs. Note that this index is a sub-index of the real estate market – it only looks at homes with conforming mortgages, so it excludes all cash distressed sales and the jumbo market.

In other economic data, the Bloomberg Consumer Comfort Index fell slightly last week to 44.2. Consumer comfort is crawling back to the bubble days, but still is lower than the Big 90s when the stock market bubble was raging.

One thing that is apparent in this election cycle is that it is hip to bash big business. Why won’t they fight back and tell their side of it? In essence, they dismiss the current populism as so much heated campaign rhetoric and believe that when the election is over, it is back to business as usual. FWIW, they have scored some big victories with the Ex-Im bank and the TPP trade deal. Wall Street, for some inexplicable reason, continues to be content with being a punching bag.
The Atlanta Fed lowered their Q1 GDP estimate to 2.5% from 2.6%.
Filed under: Economy, Morning Report | 40 Comments »
Posted on February 24, 2016 by Brent Nyitray
Markets are getting pounded on the new worry du jour: Brexit. Bonds and MBS are rallying..
Brexit is the threat of the UK leaving the EU. It has implications mainly in the foreign exchange markets, but if the markets need something to worry about, well there you go.
Mortgage Applications fell 4.3% last week as purchases rose 2.2% and refis fell 7.7%. The spike in rates last week killed the refis.
New Home Sales continue to disappoint. Sales fell in January to 494k from 544k in December. For whatever reason, homebuilders continue to hold back production and rely in price hikes to move the top line.
Regardless, people are still optimistic about the housing sector going forward. Toll Brothers mentioned that a dearth of skilled labor is an issue. Interestingly, average selling prices on signed contracts are falling for them in some areas of the country (the Mid-Atlantic and the South) and are flat in the West. Their urban luxury apartment sector was where all the ASP growth was. Perhaps the builders have pushed price hikes about as far as they can and now buyers are beginning to balk.
Filed under: Economy, Morning Report | 39 Comments »
Posted on February 23, 2016 by Brent Nyitray
Stocks are lower this morning on fears of another yuan devaluation. Bonds and MBS are down.
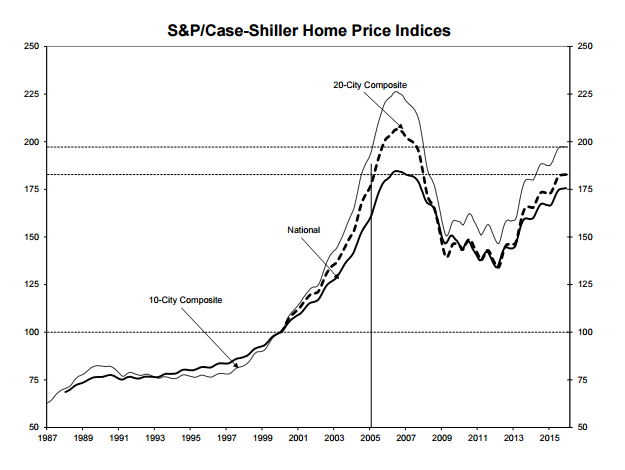
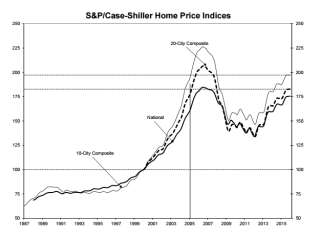
Home Prices continued to rally in December, according to the Case-Shiller Home Price Index. They were up 0.8% on a month-over-month basis and up 5.7% on a year-over-year basis. Prices remain about 11.5% below their July 2006 peak. Note the FHFA House Price index which we will get on Thursday is already at new highs.
Existing Home Sales were up 0.4% at 5.47 million units in January, according to the National Association of Realtors. On a year-over-year basis, they are up 11%, the biggest gain in 3 years. The median home price rose 8.2% year-over-year to $213,800 as supply constraints continue to drive up prices. Housing inventory is 1.82 million units, which represents a 4 month supply. A balanced market is more like 6 – 6.5 month’s worth. Ultimately, the big price increases are unhealthy because incomes have yet to really exhibit growth (although that may be changing). The median house price to median income ratio is roughly 3.8x, using the median income data from Sentier. 3.3 – 3.7x which is about normal.
Speaking of home supply, McMansion builder Toll Brothers reported earnings this morning. Revenues were driven again by an 11.7% increase in average selling prices and not by unit growth. Gross margins fell, which speaks to increasing costs. So far this February, deposits and contracts are flat with last year. The decline in stocks probably has a lot to do with it as the luxury buyer is going to be more sensitive to asset prices than the first time homebuyer.
Interesting to see this dynamic with the builders – a reluctance to build more units despite higher prices. Interestingly, CalAtlantic (the new name for Standard Pacific and Ryland after their merger) is bringing back the buydown loan.
In other economic news, consumer confidence slipped in in February, and the Richmond Fed Manufacturing Index both fell.
Blackrock is warning clients that the Fed is not likely to sit out the rest of 2016, the way the Fed Funds futures markets are predicting. Efficient market theorists might scoff at that notion, however the interest rate markets are so manipulated by central banks at the moment it makes sense to look at market signals with a jaundiced eye. What does that mean to mortgage types? Make hay now, because no one knows how long these low rates are going to stick around.
Speaking of credit markets, the new subprime – auto loans – are beginning to exhibit signs of trouble. Auto loans are being priced like mortgages, however a mortgage is secured by a generally appreciating asset, while an auto loan is secured by a depreciating asset. This is the result of financial repression, which is the act of pushing interest rates to the floor. Investors who have to earn a return (like pension funds and insurance companies) are forced to move further and further out on the risk curve to earn their required return. The actuarial tables really couldn’t care less that interest rates are zero.
Filed under: Economy, Morning Report | 67 Comments »
Posted on February 19, 2016 by Brent Nyitray
Markets are lower this morning on no real news. Bonds and MBS are down.
Real Average weekly earnings increased 1.2% in January.
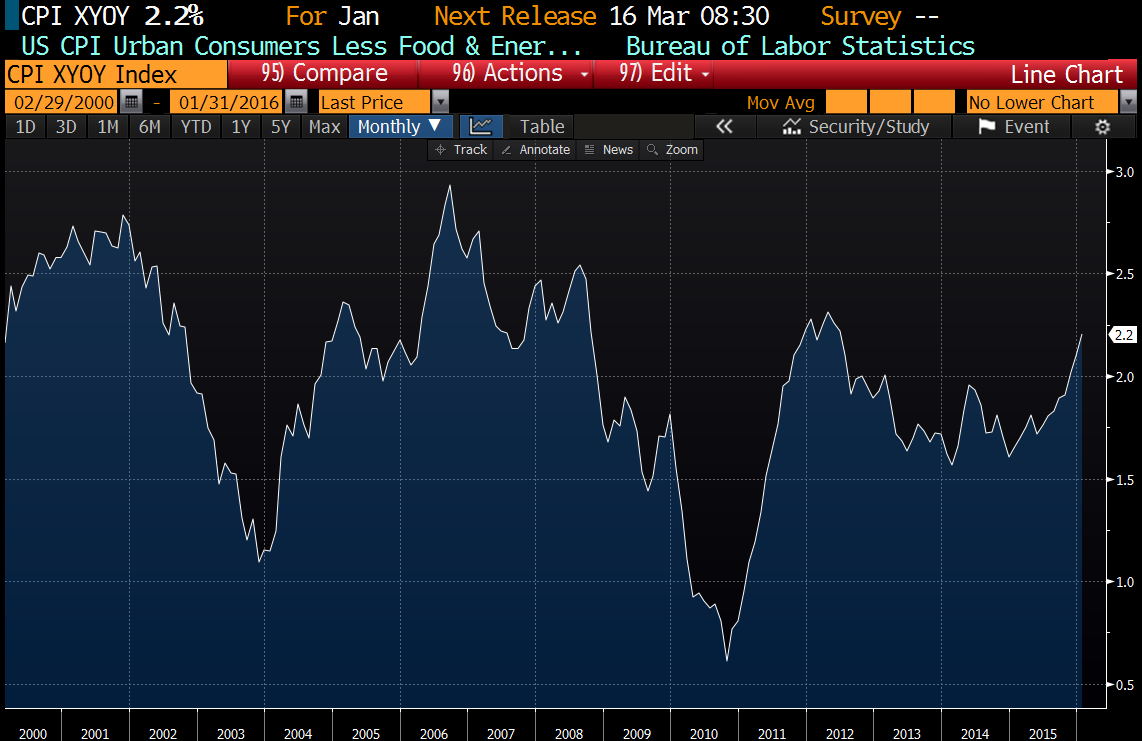
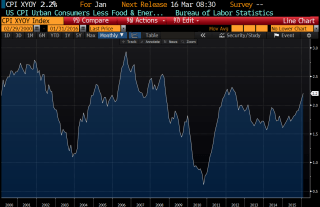
Inflation at the consumer level was flat month-over-month and up 0.3% YOY. Ex food and energy, it was up 2.2%, which is the highest level since June of 2012. This would indicate the Fed is actually getting there as far as its inflation target. That said, the Fed prefers to use the Personal Consumption Expenditure index, which is still below their target.
Chart: YOY inflation, ex-food and energy:
The thinking behind negative interest rates, explained. European economists give their take on it. Basically they work well in smaller. open economies as a lever to manipulate foreign exchange rates, but they aren’t all that effective for larger economies which are trying to boost inflation and growth. In other words, they might work for Denmark, but probably won’t do much good here. Japan recently went negative, so that will be a good test of that theory.
There is legislation afoot to eliminate the caps on VA loans, which will make them much more popular in high cost areas. Basically it will become a no money down jumbo. It has passed the House, and the prospects are good in the Senate and the WH.
Filed under: Economy, Morning Report | 65 Comments »
Posted on February 18, 2016 by Brent Nyitray
Stocks are higher this morning after oil continues its rally. Bonds and MBS are flat
Initial Jobless Claims fell from 269k to 262k., while the Philly Fed improved to -2.8.
The Bloomberg Consumer Comfort Index fell slightly to 44.3 from 44.5 the prior week. The Economic Expectations index fell markedly from 47 to 42.5.
The Index of Leading Economic Indicators improved slightly in January from -0.3% to -0.2%.
Mortgage Delinquencies fell from 4.99% to 4.77% and foreclosures fell from 1.88% to 1.77% in the fourth quarter, according to the MBA.
The FOMC minutes were released yesterday, and for the most part they were a non-event as far as the markets were concerned. The Fed did spend some time talking about the slowdown in China, and the reverberations in the markets. A number of officials are beginning to think the inflation forecasts are too high. In addition, the stresses in the financial system act as a tightening even if rates go nowhere. The Fed seems to be setting the stage for a cut in the GDP and inflation forecasts at the March meeting, as well as a pause in tightening. Separately, the OECD took down its forecast for global growth to 3.0% from 3.3%.
Mortgage REIT MFA Financial reported earnings this morning. They continue to position their portfolio of MBS more towards credit risk and less towards interest rate risk. When the private label securitization market comes back, REITs like MFA will be the big buyers of non-QM paper. Their appetite for non-agency MBS will be the key driver bringing back the widespread use of products that don’t fit in the agency box.
FHFA Chairman Mel Watt says that the GSE’s lack of capital is the most serious risk to the mortgage market right now. He says that guarantee fees have increased 25 basis points since 2009 and they are now “appropriate.” He also said that the current state of conservatorship is “not a desirable end state” and said that the GSE’s protection from market forces “presents itself in multiple decisions, including pricing.”
Filed under: Economy, Morning Report | 50 Comments »
Posted on February 17, 2016 by Brent Nyitray
Stocks are higher this morning as yesterday’s rally has follow-through on overseas markets. Bonds and MBS are down.
Mortgage Applications rose 8.2% last week as purchases fell 3.7% and refis rose 16%.
Housing starts came in 1.1 million, missing the 1.17 million estimate. Building Permits were flat at 1.2 million.
The Producer Price Index rose 0.1% in January. The core index (ex food and energy) rose 0.4%. The headline number was up 0.6% YOY and the core number was up 0.8%.
Industrial Production jumped in January by 0.9%, however the preior month was revised lower from -0.4% to -0.7%. Manufacturing Production rose 0.5%. Capacity Utilization improved markedly from 76.4% to 77.1%.
At 2:00 pm, we will get the FOMC minutes. Given the uncertainty around the Fed’s future plans, we could see the market more sensitive to these than usual.
Neel Kashkari of the Minneapolis Fed gave a speech to Brookings yesterday, calling for even more regulation for the banks and to turn them into public utilities. Of course any examination over whether the Fed had a hand in creating the real estate bubble in the first place is nowhere to be found.
Filed under: Economy, Morning Report | 61 Comments »
Posted on February 16, 2016 by Brent Nyitray
Green on the screen as investors return after a long weekend. Bonds and MBS are down small.
The Empire Manufacturing Index improved slightly to -16.64 versus -19.37 in the prior month.
The NAHB Homebuilder Sentiment Index fell to 58 from 61 in February.
Saudi Arabia, Russia, Venezuela and Qatar agreed to freeze production at January levels provided the other members of OPEC agree to go along. Apparently this has been in the works for a while, so oil isn’t having much of a reaction.
Household debt increased 0.4% in the fourth quarter, according to the NY Fed. Student Loan and Auto loan financing are growing the most, while mortgage and HELOC is steady or falling. Credit quality for mortgage debt remains strong, however you can see the increase in low-FICO auto loans (the new subprime). Debt levels below:

As the Spring Selling Season begins, inventory remains tight, especially close to urban areas. The supply of homes is the lowest since 2005.
Filed under: Economy, Morning Report | 75 Comments »
Posted on February 11, 2016 by Brent Nyitray
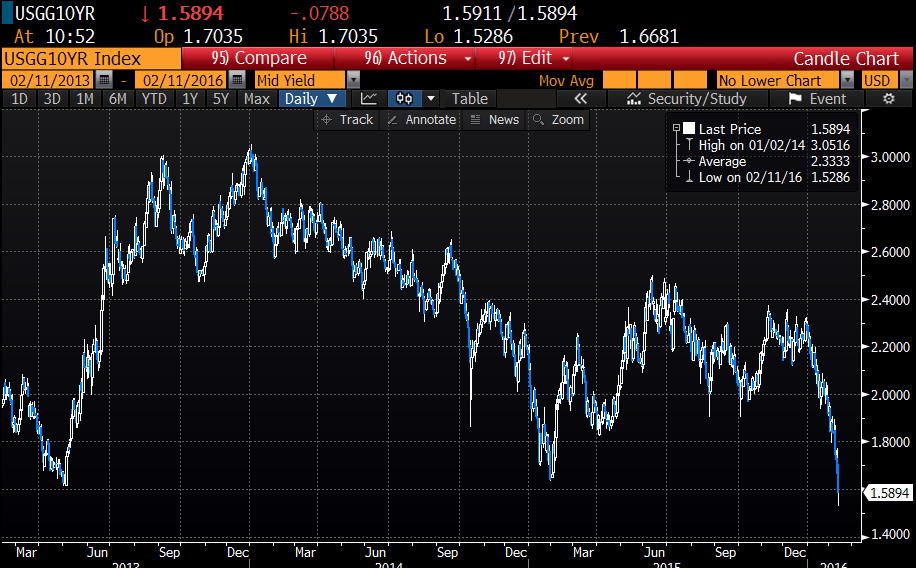
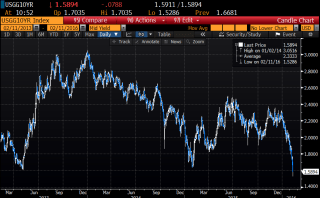
Global stock markets are down again on no real news. Whatever comfort markets took in Janet Yellen’s remarks yesterday are over. Bonds and MBS are up, with the 10 year bond yield pushing a 1.5% handle.
Loan officers, you have been given an unexpected gift with the 10 year. Rates are now at the pre “taper tantrum” level when the Fed started bracing the markets for the end of QE. So I guess the Fed didn’t need to purchase $4 trillion worth of assets to get rates down?
Initial Jobless Claims fell to 269k from 285k last week. It bears repeating that these numbers are exceptionally good and are associated with boom times. The tape doesn’t care, but still…
The Bloomberg Consumer Comfort Index rose slightly to 44.5 from 44.2 last week. Lower gasoline prices are helping improve the mood.
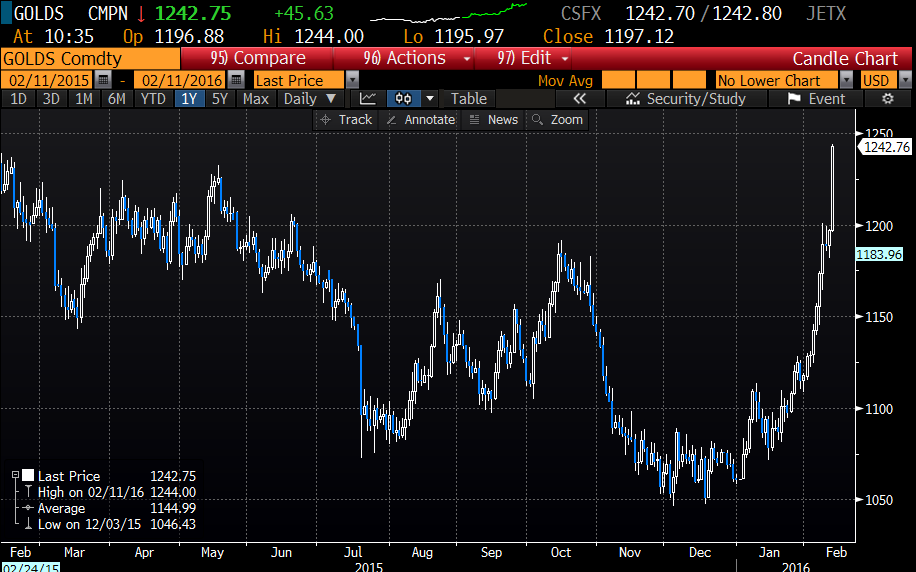
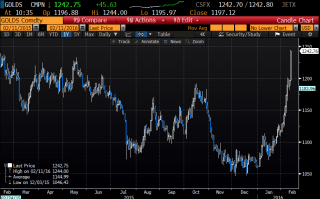
Most commodities have been getting crushed lately, however one has been on a tear: Gold. Gold is a strange animal, in that it is one of the few financial assets that isn’t some else’s liability. The price of gold can be considered to be the (inverse) confidence indicator in the world’s central banks. Gold up, confidence down.
Continuing on the central bank thread, one of the bright spots in the US markets has been auto sales. This has been driven by a couple things: The biggest was that people deferred replacing cars until they absolutely had to due to the lousy economy. However another reason is cheap credit, and some hedge funds think they have found the new “big short” in subprime auto. When you can get an 8 year loan for a new car at a rate below the 30 year fixed rate mortgage, something is awry.
So, yet another pillar holding up the economy was based on cheap credit. Janet Yellen must feel like Michael Corleone: “Just when I thought I was out, they pull me back in.”
The House Financial Services Committee is having a hearing today on FHA MIP. Expect Democrats to push for another cut and Republicans to be against it. The Democrats are in a strange position with the base continuing to push for even tougher regulations for the industry and the affordable housing types getting sick and tired of the tight credit that results.
Filed under: Economy, Morning Report | 76 Comments »
Posted on February 10, 2016 by Brent Nyitray
Stocks are higher this morning based on prepared testimony for Janet Yellen’s appearance before Congress. Bonds and MBS are down small.
Keep in mind that the Chinese stock market is closed all week in observance of the Chinese New Year, so the biggest catalyst for downside movement in the markets will be absent this week.
Janet Yellen is traveling to the Hill for her Humphrey Hawkins testimony. In her prepared remarks she did spend some time talking about the turmoil in the financial markets and that acknowledgement was soothing enough to stocks to give them a boost. Overall, however the message is that the US economy is improving, and rate are going up gradually. The rest of the testimony will probably be a bunch of ideological questions from various congresscritters trying to get the Chairman of the Fed to agree with their ideological worldview.
Goldman is forecasting 3 rate hikes in 2016. Given the overall weakness in the global economy and the rush to negative interest rates globally, it may not affect long-term interest rates in the US (or mortgage rates for that matter).
Blackrock is forecasting that US growth has probably peaked for the near term as more and more central banks enter the negative interest rate vortex. I wonder what our grandkids will think about today’s PhD standard. If it ends up not working, do we go back to the gold standard?
In New Hampshire, Bernie Sanders won the Democratic primary vote, and Donald Trump won the Republican primary vote. John Kasich had a surprisingly strong showing.
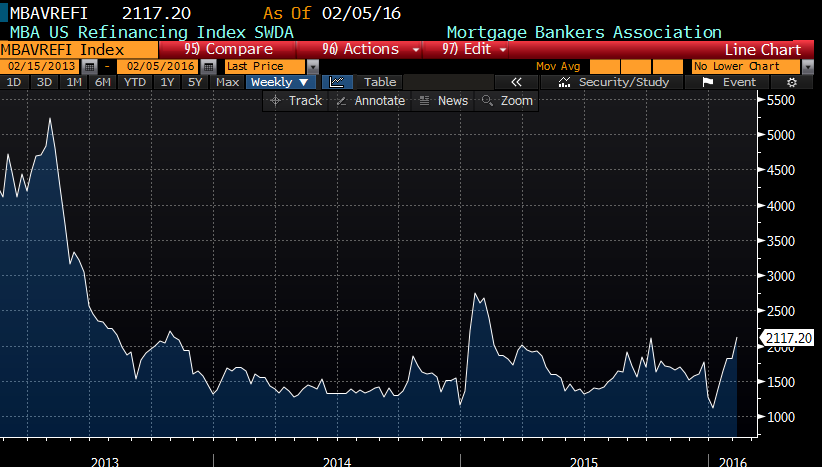
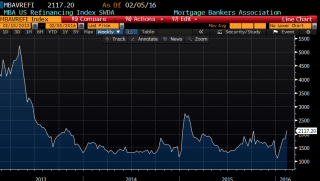
Mortgage Applications rose 9.3% last week as purchases were up 0.2% and refis were up 15.8%. The refi index has had a nice run since rates started collapsing, but we are nowhere where we used to be compared to 2013.
Competition in the jumbo market is fierce, and the typical rate for a jumbo is now 15 basis points below a conforming mortgage. Historically, jumbos have cost an extra 25 basis points to the borrower.
Do you think your underwriters are approving too many shaky loans? Move them to Seattle. Are they too conservative? Move them to San Diego.
Filed under: Morning Report | 52 Comments »


 Brent Nyitray
 Fairlington Blade
 Let the mutherfuker burn!
 jnc4p
 Kevin S. Willis
 Michigoose
 lmsinca
 markinaustin
 Arcanaut
 novahockey
 quarterback
 ScottC
 yellojkt