Morning Report: Inflation returning? 3/16/16

Markets are lower this morning after inflation comes in a little hotter than expected. Bonds and MBS are down.

The consumer price index fell 0.2% month-over month, but the core index, which excludes food and energy, rose 0.3% and is up 2.3% year-over-year. This makes the FOMC statement (and the press conference that follows) more significant this afternoon. Remember, the decision will be out at 2:00 pm EST, so expect some volatility in bonds around that time.

Bonds sold off on the CPI number and the more dramatic move was in the 2-year, not the 10-year. The 2 year yield increased 3 basis points on the news to .99%. Movements in the 2-year signify the market’s expectations about what the Fed is up to. The 10 year is more driven by longer-range economic forecasts. The 10 year was up, sold off on the news and is now flat on the day.

Housing starts rose to an annualized pace of 1.178 million in February and January was revised upward to 1.12 million. Building Permits fell however to 1.17million from 1.2 million. The drop in permits was driven by multi-family construction as single-fam remains slow and steady.

Mortgage Applications fell 3.3% as purchases rose 0.3% and refis fell 5.6%. Refis now constitute 55% of the total number of loans, down about 9 percentage points over the last month.

The strong dollar is still making life tough for manufacturers. Industrial production fell 0.5% month-over-month, while manufacturing production rose 0.2%. Capacity Utilization fell to 76.7%.

Marco Rubio is out after losing his home state of Florida to Donald Trump. John Kasich won Ohio, which keeps him in the race and makes him the de facto “Establishment Candidate. Ted Cruz is still in and he is probably going to split the Trump vote, while Kasich solidifies the establishment vote. Policy-wise, Kasich and Hillary are almost identical. Trump is warning that there will be riots if he has the delegates (or is close) and loses a contested convention. The convention is 4 months away. A lot can happen.

On the Democratic side, Hillary did well, so we can stick a fork in the #FeelTheBern hashtag.

Morning Report: Homebuilder Sentiment Flat 3/15/16

Markets are lower this morning as the dollar rallies and commodities fall. Bonds and MBS are up.

The FOMC meeting begins today. The decision will come out at 2:00 pm EST tomorrow, along with the new economic and Fed Funds forecasts. Here is Tim Duy’s take on the state of play. His take: while you could make an argument to tighten, the Fed still considers the bigger risks to be to the downside. The doves are ascendant on the Board.

Retail Sales fell 0.1% in February, although declining gasoline prices had a lot to do with it. Ex-autos and gas, they were up 0.3%. The control group, which also strips out building products was flat. The downward revisions to January got everyone’s attention however as the initial 0.2% estimate was revised downward to -0.4%.

Inflation at the wholesale level remains well below the Fed’s target. The Producer Price Index fell 0.2% in February as well. Ex-food and energy, it was flat on a month-over-month basis and is up 1.2% YOY.

The Empire Manufacturing Index rebounded smartly to .62 after a heavily negative start to the year.

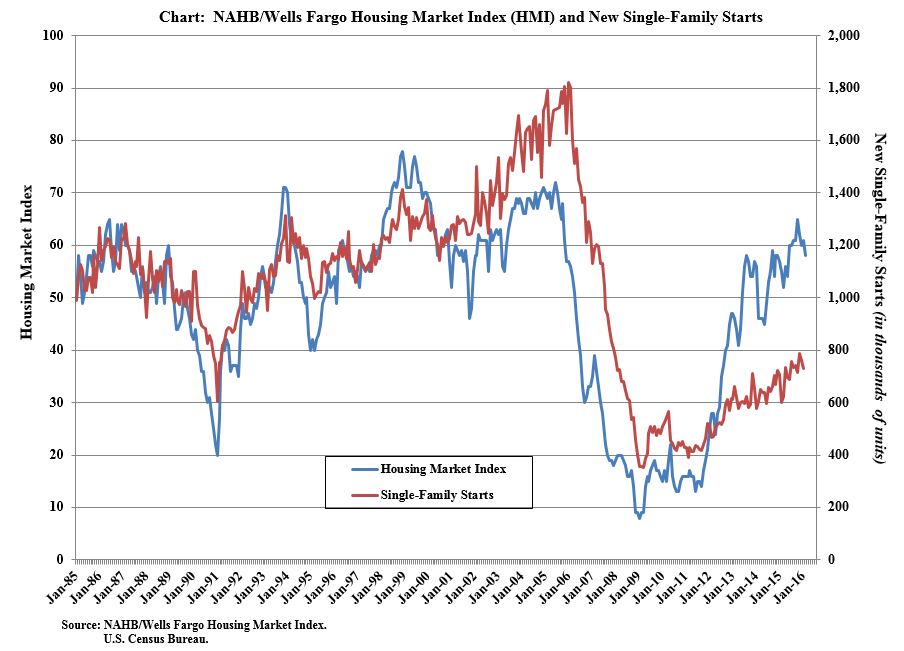
The NAHB Homebuilder Sentiment Index was unchanged at 58 in March. This is a 9 month low. A shortage of lots and labor continue to be the biggest headaches facing the sector. The builders have been able to drive the top line by raising prices, not by pushing volume. You can see below how the index has tracked versus housing starts. The divergence is as big as it has ever been.

Voters go to the polls in several states today, including Florida and Ohio, which are do-or-die races for Marco Rubio and John Kasich respectively. The Democratic side seems pretty much set at this point, unless Bernie Sanders pulls a free rabbit out of a hat.

Morning Report: FOMC week 3/14/16

Stocks are lower this morning as oil gets roughed up. Bonds and MBS are up.

There is no economic data this morning, however the rest of the week looks pretty active, with retail sales, inflation data, housing starts, and industrial production. Of course we have the FOMC meeting Tuesday and Wednesday as well.

Mohammed El-Arian lays out his prediction for the FOMC meeting this week. Bottom line: No move in rates, and an emphasis on data-dependency. They will mention overseas weakness, but won’t make the statement that it will affect the US economy all that much. They will be sanguine on overall US data without becoming too hawkish on wages and inflation. So, generally a dovish take on things.

It is hard to come up with a good reason to take away the punch bowl when investor sentiment is hitting 2 year lows. Of course the ultimate poll is the market, and not some survey. Where are investors doing well these days? Rental properties.

Note that the recent increase in US rates was driven at least partially by increases in Euro rates. That move seems to be unwinding (in other words, Euro rates are heading back down). This will probably help guide US rates lower as well, especially if we get a dovish statement on Wednesday.

Morgan Stanley is out with a call saying yields are going lower. Their forecast: 1.45% 10 year by the end of September. While the US economy is doing ok, the rest of the world is not. They think the next rate hike will be in December.

Why is the first time homebuyer sitting out? Freddie Mac attributes at least some of the reason to misconceptions about buying, specifically credit scores and down payments. Many young borrowers still believe you need 20% down and perfect credit to qualify for a mortgage. Freddie has launched their Real Estate Professionals Resource Center to give pros the lowdown on products that can get a young borrower into a home.

Morning Report: Markets yawn at the new ECB stimulus 2/10/16

Stocks are flat this morning after the ECB’s new stimulus plans earned a big yawn from the markets. Bonds and MBS are down.

The ECB cut interest rates again, and threw a kitchen sink worth of QE, lender subsidies, and other goodies.They will also start buying corporate debt. Not sure what the markets were looking for, but Euro rates are higher this morning with the German Bund yielding 32 basis points, up 8. This is what is dragging US rates higher. Buy the rumor, sell the fact, I guess.

Initial Jobless Claims came in at 259k, while the Bloomberg Consumer Comfort Index ticked up slightly to 43.8.

Americans have regained most of the wealth lost when the real estate bubble burst. Homeowners’ equity has more or less doubled since the lows of 2009. Since 2013, real estate has outperformed ther S&P 500 by 16 percentage points.

Morning Report: Consumers are becoming less bullish on home price appreciation 3/9/16

Stocks are higher this morning as commodities rally and the market anticipates more stimulus from the European Central Bank tomorrow. Bonds and MBS are down small.

Mortgage Applications edged up 0.2% last week as purchases increased 4.2% and refis fell 2.3%. The 30 year fixed rate mortgage rose 6 basis points. We saw a big move up in ARM rates from 3.02% to 3.2%. In an environment where the yield curve is flattening, switching from an ARM to a 30 year fixed is the trade to make.

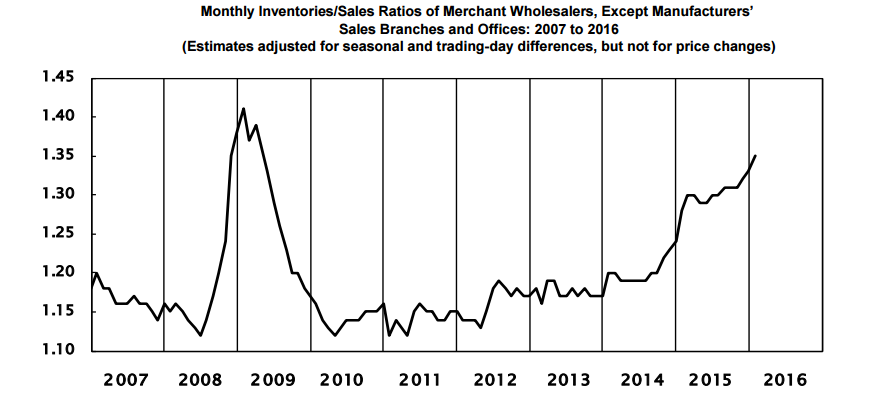
Wholesale sales fell 1.3% last month while inventories built up 0.3%. The inventory-to-sales ratio is 1.35 month’s worth, which is the highest since April of 2009. This is a negative sign for the economy going forward, as inventory build adds to GDP, and a buildup essentially “borrows” growth from future quarters. While this number doesn’t carry the same weight it did 20 years ago, it still matters.

Marco Rubio had a tough day yesterday. John Kasich is looking more and more like he could be the “establishment candidate.” Bernie Sanders beat Hillary in Michigan, as anti-trade populism resonates deeply in the hard-hit rust belt.

Consumers are becoming a touch less bullish on future home price appreciation, according to the latest Fannie Mae National Housing Survey. They anticipate that home prices will appreciate 1.7% next year, as opposed to 2.2% last month. We are certainly seeing some signs of softness in the oil states as well as the high end. Their view on the economy is about the most negative it has been since the big equity sell-off in August. 56% believe the economy is on the wrong track, and only 37% believe the economy is on the right track. This statistic explains the appeal of Sanders and Trump these days, two candidates who would ordinarily get zero traction.

Global financial markets are forecasting that the age of ZIRP will be with us for 10 years or more. Sound far-fetched? Japan has been at 0% interest rates for over 20 years. Interest rate cycles are long. While the US may not be in the sort of deflationary trap that Europe and Japan are in, relative value trading will help keep a lid on rates going forward. In fact, the US may be more at risk of future asset bubbles than deflation.

With rates so low, consumers are happy to rack up the credit card debt. The average credit card debt level for a US consumer is $7,879, closing in on the unsustainable levels we saw early in the Great Recession.

Morning Report: Conflicting signals in the labor market 3/8/16

Stocks are lower this morning on bad export numbers out of China. Bonds and MBS are up.

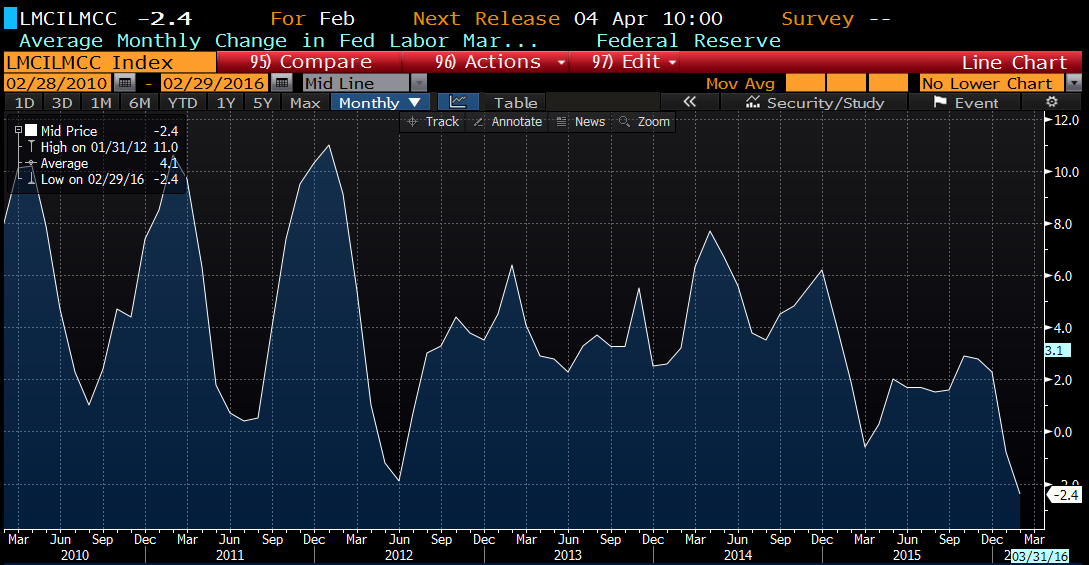
The US Labor Market Conditions Index fell in February, This is a relatively new index created of 19 different labor market indicators. Not sure what caused the recent drop in the index, as most of the big indicators are positive. Perhaps the disappointing wage growth in the last jobs report is causing it. Certainly the labor market does not seem to be the worst in four years..

Consumer credit rose by $10.5 billion in January, the lowest in a year. Lower levels of credit card debt drove the deceleration.

Small Business Optimism hit a 2 year low, according to the NFIB. Worryingly, job creation fell for the first time in quite a while, as small businesses shed about .12 workers per firm. The difficulty in finding qualified workers also fell in importance, although it is still elevated. Washington remains the biggest impediment, with taxes and red tape occupying the #1 and #2 concerns for small business. The report summed it up this way: “Overall, a “ho hum” outcome, confirming that the small business sector is not headed up with any strength, just treading water waiting for a good reason to invest in the future.”

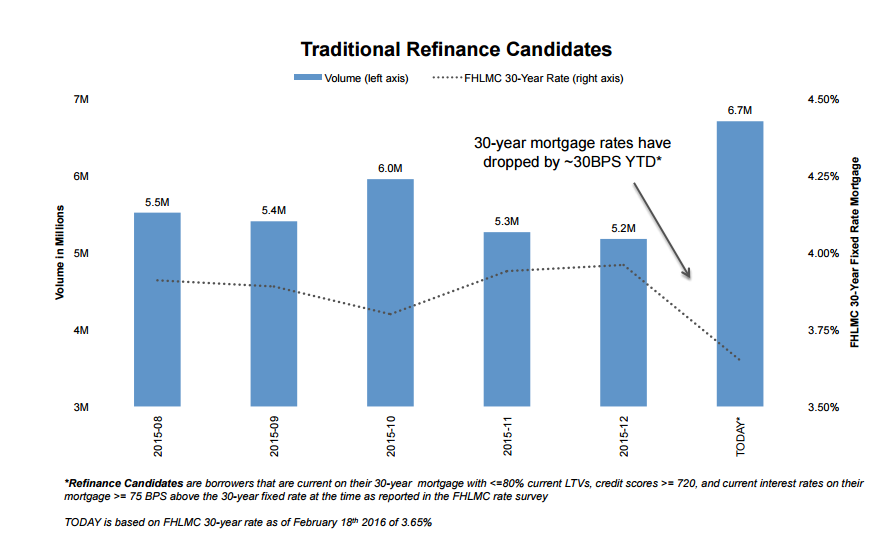
The big drop in interest rates has bumped up the refinanceable population to 6.7 million borrowers from 5.2 million last month, according to Black Knight Financial Services.   An additional 15 basis point drop in rates would add another 2.1 million borrowers. This data is based on mid-February numbers, with a FHLMC 30 year rate of 3.65%. Just another reason why 2016 might be a little better than expected.

Foreclosure activity continues to fall, according to CoreLogic. Foreclosure inventory is down 21.7% to 456,000 homes, and completed foreclosures fell 16% in January. Serious delinquencies also fell to 1.2 million mortgages, the lowest since 2007. Foreclosure activity is making the home price recovery more durable: “The improvement in distressed properties continues across the country in every state which is contributing to the lack of stock of available homes and resulting price escalation in many markets,” said Anand Nallathambi, president and CEO of CoreLogic. “So far the trend toward lower delinquency and foreclosures has been immune from shocks from such things as the collapse in oil prices attesting to the durability of the housing recovery.”

Morning Report: Mixed jobs report 3/4/16

Stocks are flattish after the jobs report. Bonds and MBS are down.

Jobs report data dump:

  • Nonfarm payrolls +242k
  • Unemployment rate 4.9%
  • Average hourly earnings -0.1%
  • Labor force participation rate 62.9%
  • Average weekly hours 34.4

Overall, an okay report: payrolls were better than expected, but hourly earnings disappoint. The increase in the labor force participation rate is a good thing to see. While it will depress wage growth at least initially, it will make for a stronger economy down the road. FWIW, there may be measurement issues regarding the wage measure that will supposedly be unwound in the next report.

Bonds sold off on the jobs report, with the 10 year and the 2 year bond yields up 3 basis points. I doubt this report will change any minds with regard to the March FOMC meeting, which most people seem to think will have no move in rates and hawkish language.

More evidence of wage inflation: Costco is upping the lower end of their wage scale from $11.50 to $13.00. They announced it on their earnings conference call last night. This will hit their earnings per share by about 1.3% over the next year. Competition for workers is becoming more intense as unemployment stays below 5%.

Morning Report: Lots of economic data this morning 3/3/16

Stocks are slightly lower as a slew of economic data comes in this morning. Bonds and MBS are flattish.

Outplacement firm Challenger, Gray and Christmas reported that announced job cuts rose 21.8% in February to 61.6k. The energy sector accounted for 25k of the losses, followed by chemicals, computer, and industrial goods. The West and the Midwest bore the brunt of the cuts. Remember these are announced job cuts and often never actually happen. Overall, the employment picture is looking decent, however we’ll get a better look tomorrow.

Here is a table of the industries hit. Note that aside from energy, job cuts are pretty low. Note that these are not net numbers either – they don’t take into account any sort of hiring.

Initial Jobless Claims rose to 278k last week. Anything below 300k is a good number.

The ISM Non-manufacturing composite fell slightly to 53.4 in February from 53.5 in January. Business continues to be decent in the services sector.

Factory Orders fell 1.6% in January, while durable goods orders rose 4.7%. Capital Goods Orders rose 3.4%.

Why is wage growth so difficult to find? Productivity growth has been weak since peaking around 1999 – 2000. This was the tail end of the big boost from the Internet and the decade-long transformation of the PC into a tool on everyone’s desk. Last quarter it came in at -2.2%. Productivity has been negative for 3 out of the past 4 years, and that is not a recipe for wage inflation.

Unit Labor costs rose 3.3% in the fourth quarter, which drove the drop in productivity as output only increased 1%.

The Markit US Services PMI fell slightly in February to 49.7 while the composite PMI was flat at 50.

The Bloomberg Consumer Comfort Index fell to 43.6 from 44.2 last week. Falling perceptions of the economy drove the decline.

2012 Presidential Nominee Mitt Romney is going to try and push back the Trumpmentum with a speech tonight.

Nothing too earth-shattering in the Fed’s Beige Book which was released yesterday. Overall, manufacturing is flattish compared to last month, however labor markets improved overall, and “wage growth varied considerably, from flat to strong, across all districts.”

Morning Report: Global yields continue to fall 3/2/16

Stocks are lower this morning after yesterday’s strong rally. Bonds and MBS are down.

Mortgage Applications fell 4.8% last week as purchases fell 0.6% and refis fell 7.2%.

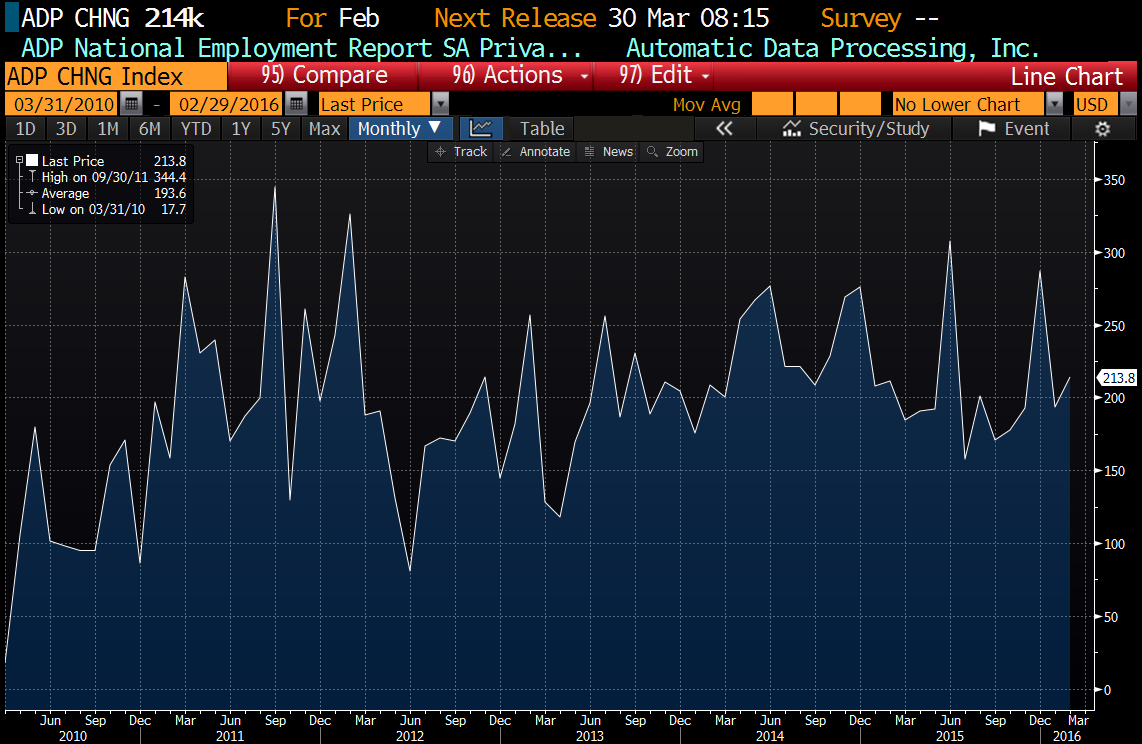
The ADP Employment change came in stronger than expected at 214k jobs. The Street is forecasting an increase of 195k payrolls for Friday’s jobs report. All of the activity was in the services sector, as the manufacturing sector lost about 9,000 jobs and the financial sector added only 8,000.

Chart: ADP jobs

The ISM New York Index fell slightly to 53.6

Donald Trump and Hillary Clinton were the big winners on Super Tuesday. You can probably stick a fork in Sanders at this point. For the GOP, the question is whether Donald Trump is a plurality winner or a majority winner. The establishment is hoping that once they coalesce around a single candidate, the numbers will swing to that candidate. If they go the brokered convention route, Trump will almost certainly run as an independent, which guarantees a Clinton landslide.

Yesterday was a bloodbath in Treasuries, with the 10 year yield increasing about 9 basis points to 1.82%. The 2 year yield increased 7 basis points. If we see strong wage growth on Friday’s jobs report, we could see further weakness in Treasuries.

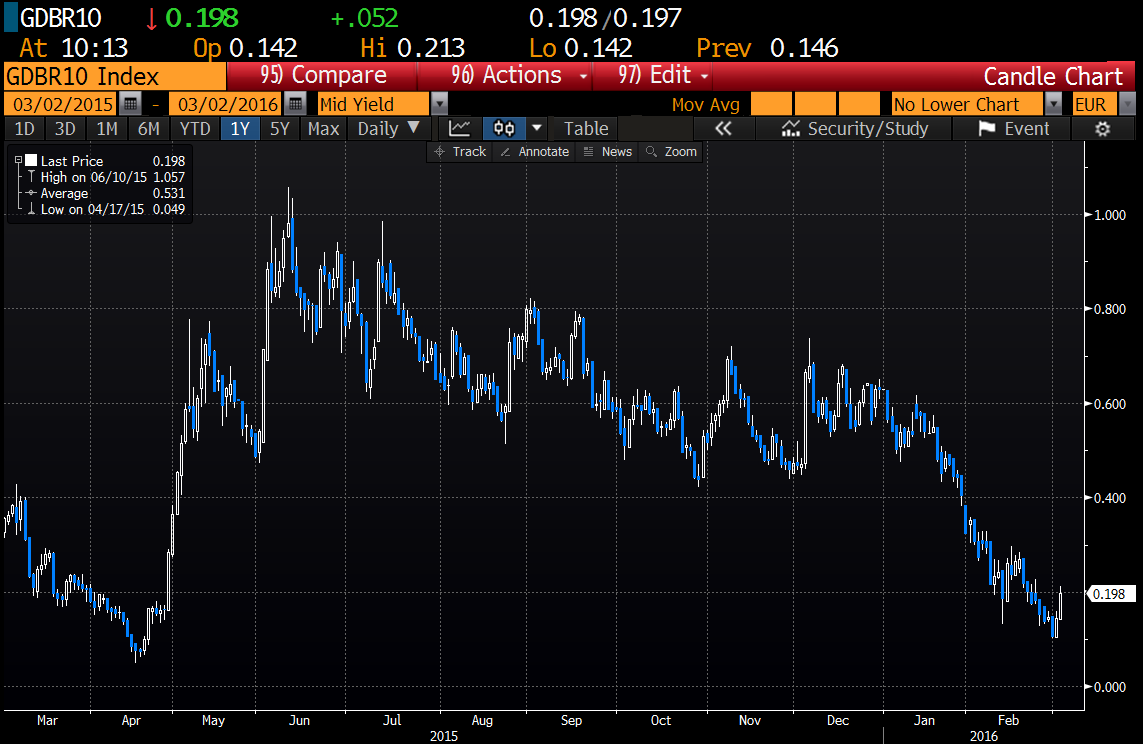
To put the current 1.85% 10 year yield in perspective: when the Fed hiked rates last December, the yield was 2.3%. That said, the fact that interest rates are falling globally will prevent Treasuries from falling too much. Note the German 10 year Bund is close to the sub 10 basis point lows of last spring, and currently yields 18 basis points. The Japanese Government 10 year bond yield is negative 5 basis points. Global investors look at Treasuries yielding more than Italian, Spanish, and Irish bonds and see relative attractiveness, especially since the US is about the only country not trying to devalue its currency. That should help keep a lid on rates.

Chart: German Bund Yield

The collapse in global bond yields is sending a signal that the Fed isn’t going to ignore – that deflation remains a threat. Janet Yellen has pledged to let the labor market “run hot” for a while and that means letting wage growth run. The big question is what happens to the labor force participation rate. If these workers come back, that will prevent too much wage inflation and will be ultimately better for the economy in the longer term. If they don’t, then look for wage inflation to begin and the Fed to move earlier.

Morning Report: Markets at odds with Fed forecasts 3/1/16

Green on the screen this morning as oil and emerging markets rally and the Chinese act to boost lending. Bondsd and MBS are flat.

The ISM manufacturing Index improved to 49.5 from 48.2 last month. Still below 50, which indicates a slowdown, but better than expected. The Markit US Manufacturing PMI came in at 51.3, better than expected.

Construction Spending rose 1.5% in January, much higher than the 0.3% forecast. Public construction drove the increase. Private residential construction was flat for the month.

The turmoil in the financial markets and the global economy have cooled the market’s forecast for further rate hikes. The Fed Funds futures contracts are now forecasting only a 10% chance of a rate hike at the upcoming March meeting and a coin toss for one by December. This is at odds with the last dot graph from the December FOMC meeting, where the median forecast was 1.25% by the end of 2016.

Vehicle sales are coming in strong this morning. Ford Feb sales were up 20%, while Fiat Chrysler sales were up 12% on strong Jeep sales. SUVs were the big gainer overall, as lower gasoline prices entice drivers to switch to bigger cars. Much of this growth is being fueled by cheap credit, however there is so much pent-up demand for new cars (the average age of a car in the US is 11.4 years) that this growth is probably sustainable for the near term and isn’t just a cheap credit story.

Today is Super Tuesday, where 12 states are holding primaries. So far, it looks like Hillary Clinton and Donald Trump will emerge as the winners.

Elmer Fudd warns of “distortions to savings and investment” due to negative interest rates. As the primary architect of the Great United States Housing Bubble, it would have been nice if he had worried about monetary policy-driven distortions to savings and investment say, 15 year ago.

Home prices continue to rise according to CoreLogic. Prices rose 1.3% MOM and are up 6.9% YOY. According to Corelogic, prices remain about 7% below their April 2006 peak. Overvalued markets include many in Texas, Washington DC, and Florida. You can see in the map below, which areas are cheap and expensive (green=cheap, red=expensive).

NAR is predicting existing home sales of 5.38 million in 2016, with average home price appreciation of 4% to 5%. It looks like the Northeast is finally starting to pick up a bit, with contracts up 11% in January.