Morning Report

Vital Statistics:

Last Change Percent
S&P Futures 1341.4 -0.8 -0.06%
Eurostoxx Index 2471.7 -22.2 -0.89%
Oil (WTI) 101.61 -0.2 -0.19%
LIBOR 0.4931 -0.002 -0.40%
US Dollar Index (DXY) 79.952 0.225 0.28%
10 Year Govt Bond Yield 1.96% 0.03%

Global equity markets are weaker this morning as European leaders delay a vote on the Greek bailout until 2/20.  The finance leaders were able to squeeze some more concessions from political leaders, but there are still differences over surveillance and control. Separately, Moody’s threatened a downgrade of the global banking sector. Bonds and mortgage backed securities are slightly lower as well.

GM posted a record profit! I am sure tomorrow’s editorial pages will be filled with columns praising the auto bailout and using this earnings announcement as justification. Well, if you repudiate your debt and get rid of all that pesky interest, you had better post record earnings.  GM’s numbers were still below estimates and the stock is down a couple of percent pre-open. As an aside, Chrysler has to issue senior secured debt at 8%.  That is a usurious rate for senior secured debt. See, that is what happens when you re-order the priority of creditors. Investors remember.

Economic data this morning:  Producer Price Index more or less in line with expectations, running at 4.1% annually.  Initial Jobless Claims continue to fall, coming in at 348k vs 365k expected. We are more or less back in the historical “normal” range. Housing starts came in at 699k, above expectations, but still very low. In prior recessions, housing starts bottomed at 750k – 850k.  The last time we were above 1 million units was June of 2008.  1.5 million is normal. The lack of residential construction has been the achilles heel of the recovery so far.

Chart:  Housing Starts:

The minutes of the FOMC meeting were released yesterday. They really don’t add anything to what was said in the press conference after the rate decision.  The minutes don’t really address the question most had regarding the recent good economic data. “Many participants noted some indicators bearing on the economy’s recent performance had shown greater-than-expected improvement, but a number noted less favorable data…” The tone of the minutes was that the economy was improving, albeit slowly, and there is no reason to take our foot off the gas for the moment.  Maybe the Fed believes the Greek negotiations are simply a big kabuki dance and that a default is unavoidable.

RealtyTrac has released its U.S. Foreclosure Market Report for January 2012. Key Quote: “Although overall foreclosure activity was down from a year ago for the 16th straight month in January, we continue to see signs on a local and regional level that the frozen-up foreclosure process is beginning to thaw.” They predict increasing foreclosures in the coming months especially given the settlements in early Feb between the nation’s largest lenders and 49 state attorney generals. Clearing out the shadow inventory of foreclosed homes is a necessary but not sufficient condition for a recovery in house prices.

Bits & Pieces (Wednesday Night Open Mic)

The Rev. Manning advised Ron Paul to whip Obama’s behind with the Constitution. Or did, can’t link to it now because his YouTube account has been suspended and he’s under a federal investigation for being a birther. How come this happens to him, but not Donald Trump, eh? Well, here’s a clip from one of Rev. Manning’s interesting rants now set to music. Jammin’!

Also from World Net Daily, John Stossel explains that when politicians talk about “cutting” spending, that word does not mean what they think it means.

Bruce Carlson of My History Can Beat Up Your Politics tackles the long history of negative campaigning. I cannot recommend his podcast enough. He asserts that early newspapers were essentially the blogs of the day, and also tackles the economics of the emancipation of the slaves.

4 Things Star Wars Fans Need to Accept About George Lucas.

Whose a scruffy lookin' Nerf Herder now, your highness?

Media Matters wanted to hire gumshoes to dig up dirt on the employees of Fox News in order to “discredit” them. That such a strategy might backfire, and make their side look like the bad guys while not impacting Fox’s viewership a jot or a tittle apparently never occurred to them.

That’s it for me! — KW

Barack Obama’s Black History Minute

Apparently recorded the same year he graduated from law school, and 5 years before he ran for the Illinois Senate.


He had a different speaking style then, I think.

Morning Report

Vital Statistics

Last Change Percent
S&P Futures 1352.7 5.0 0.37%
Eurostoxx Index 2504.6 16.3 0.65%
Oil (WTI) 101.52 0.8 0.77%
LIBOR 0.4951 -0.003 -0.50%
US Dollar Index (DXY) 79.543 0.159 0.20%
10 Year Govt Bond Yield 1.93% -0.01%

Markets are higher this morning on statements from the Bank of China regarding support for the European bailout and its willingness to help. Concerns about an eventual Greek deal are offsetting some of these gains. Bonds and mortgage backed securities are flat.

Mortgage Loan Delinquencies are increasing again, according to TransUnion. 64% of MSAs reported increases, which was flat compared to Q3, but much higher than Q2.  There are seasonal factors at work here, and the continuing decline in real estate prices are certainly playing a part, but that is not an encouraging data point economically. As if the foreclosure pipeline wasn’t big enough already.

Not that the markets really care, but it looks like we have a payroll tax deal.

The Empire State Manufacturing Index came in at stronger than expected. This is a touchy-feely indicator of general business conditions put out by the New York Fed.  This index is notoriously volatile, so big moves should be taken with a grain of salt, but it shows that the expansion is gaining momentum in New York State.  Separately, industrial production was flat and capacity utilization unexpectedly fell.

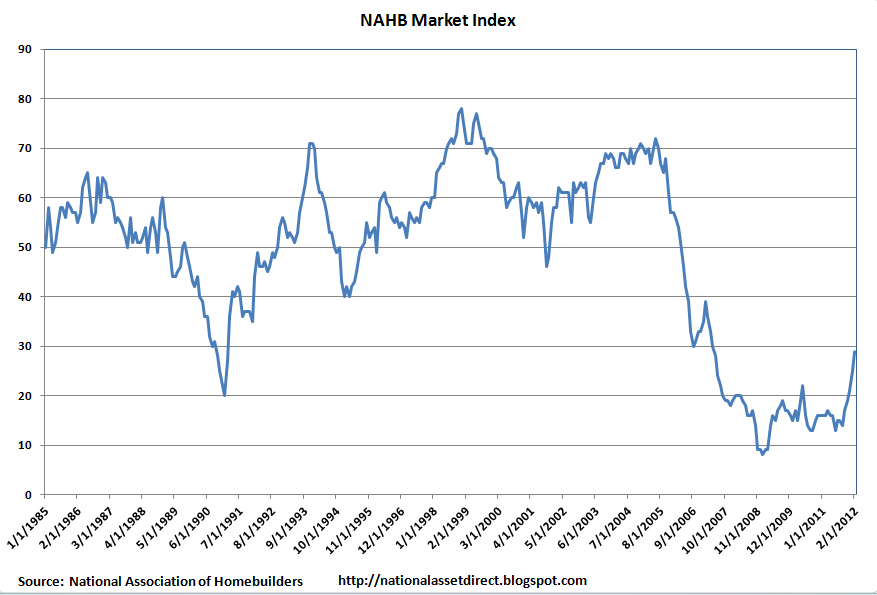
The National Association of Home Builders will release their market index at 10:00 am. Residential construction has been the missing piece of the recovery, but has been showing signs of life lately.  Earnings reports from the homebuilders have been constructive.

The FOMC minutes will be released this afternoon. I am very curious to see why the Fed is behaving as if the economy is rolling over, while the data suggest otherwise.

Last, Ezra Klein at the Washington Post has a story on how the World Cup affects trading.  I can attest to this personally, having been a block trader at Bear Stearns in London for a number of years.  When England was playing a match, the phones would stop ringing and everyone had their backs to their screens, watching the match.  You could actually see major stocks like British Petroleum and Vodafone stop trading.  As an American, it was strange to watch.

****EDIT

The National Association of Homebuilders released their market index at 10:00 am.  The index came in better than expected and it looks like conditions are improving at an accelerating rate.

Chart:  NAHB Market Index:

Morning Report

Vital Statistics:

Last Change Percent
S&P Futures 1344.3 -4.8 -0.36%
Eurostoxx Index 2486.5 -5.1 -0.20%
Oil (WTI) 101.08 0.2 0.17%
LIBOR 0.4976 -0.005 -0.99%
US Dollar Index (DXY) 79.279 0.144 0.18%
10 Year Govt Bond Yield 1.94% -0.03%

Markets are a touch weaker after a disappointing retail sales number. Advance retail sales for January were up .4% vs. expectations of .8%.  S&P futures sold off slightly on the number while bonds and mortgage backed securities rallied. For those who follow charts, the S&P is right up against resistance at the 1350 level.  If we break through, the next stop is 1600 or so.

European markets are flat in spite of Moody’s downgrades of Spain, Portugal, and Italy yesterday. The ratings agencies have been behind the curve for the whole crisis. European finance ministers are set to meet in Brussels tomorrow to approve a second Greek bailout.

Andrew Ross Sorkin has a good article on the Volcker Rule and the Costs of Good Intentions. At issue is where one draws the line between bona fide market making and proprietary trading. Bona Fide market making serves a purpose in that it keeps trading costs down and adds liquidity to the market. (FWIW, Paul Volcker doesn’t necessarily think this is a good thing). The crux of the issue is whether investment banks will be allowed to maintain an inventory of product. If they aren’t permitted to maintain any inventory of any size, then all trades will be agency trades.  In other words, if the bank can’t find the other side of your trade, you’re out of luck.

The CFPB has laid out a broad outline of some of the changes it expects to make for mortgage servicers. The initial steps will involve changes to billing statements – new rules to make it clearer when resets will occur, better contact information, and a statement from HUD.  An example of the new template is here.  The rules will also address forced-place insurance, where servicers can put a homeowner in a new, more expensive insurance plan if they fall behind in their payments.

Does anyone find it ironic that the rule which sets new tax rates on dividends is named after a guy who’s company doesn’t pay them?

Happy Valentine’s Day!

I’ve never been a fan of Al Sharpton, but who knew the man had such a sense of humor?  This had me laughing out loud:

The Rev on romance.


And too bad Scott’s busy this week.  A Libertarian economist’s POV on why FOX’s Megan McArdle is wrong on why brick-and-mortar universities will go away:

Assortative mating works best when the cognitive elites are able to combine signaling behaviors for their superior genes, particularly for doing economics, with the physical proximity that supplies bonding behaviors and oxytocin and also the opportunity to sniff the pheromes.


Since we got onto a first dance wedding song kick (a bit) on Mark’s Funny Valentine post last night, I’ve been listening to Al Jarreau , so here’s another one of my favorites:

After All


And, while I don’t count myself amongst the bitter folks, I thought that this story on NPR about three anti-Valentine’s Day books was amusing.


Happy Valentine’s Day, all ATiM-ers!!

The two best “Funny Valentines”

IIRC, this song first became popular when the great, then young, west coast jazz trumpeter, Chet Baker, sang it.

A couple of years later, it was made popular again when Ella sang it on the Rodgers and Hart Songbook.

Still later in the 50s, Frank Sinatra sang it.  But for reasons that are part of a funny story I will tell here someday, I do not play Sinatra.

Sting butchered it in a live concert.

Chet Baker and Gerry Mulligan, along with Brubeck and Desmond, defined west coast “cool” jazz.  When we were in high school, we really loved that stuff.  Baker did not often sing, but until he died in the 80s, whenever he played he would be asked to sing this.  Like any jazz guy, he never sang it the same way twice.  This first rendition was my favorite, and the one that put the song on the map as a “standard”.

And Ella was Ella.  I met her once.  I was 14.  She was gracious, as if it mattered to her that I knew who she was.  She was with the blind singer, Al Hibbler, at the time, and although I did not recognize him, when she introduced us, I knew who he was – he had made a hit of “Unchained Melody”.  I fumbled in embarrassment, but Ella made it AOK.

Happy Valentine’s Day, all.

Morning Report

Vital Statistics:

Last Change Percent
S&P Futures 1349.1 8.5 0.63%
Eurostoxx Index 2495.7 14.9 0.60%
Oil (WTI) 100.32 1.6 1.67%
LIBOR 0.5026 -0.003 -0.67%
US Dollar Index (DXY) 78.775 -0.229 -0.29%
10 Year Govt Bond Yield 1.99% 0.01%

World markets are rallying on the positive Greek austerity vote over the weekend.  European finance ministers will meet on Wednesday to approve the second bailout plan.  Does this mean the crisis in Greece is over?  Not really.  Bondholders have to accept the proposed haircuts and if there are holdouts (and the holdout trade is a staple of distressed hedge funds), there will still be risk of default.

Heard on the Street has a good piece on corporate profit margins and what that means for the economy.  Productivity has been falling, and that perversely can portend good things.  After the financial collapse, companies dramatically cut their workforces and held off on capital spending unless it was absolutely necessary.  As demand returned, companies squeezed as much output as they could from existing resources.  They held off hiring and making investment in productivity-increasing capital. Stocks have reacted positively to growth in profit margins as revenues increased while costs stayed stagnant.  This was reflected in the productivity numbers (which measure amount of output per input).  Lately, productivity increases have been smaller and smaller, meaning that effect has largely been played out.  This means if companies want to meet increased demand, they have to hire – their existing workforces are maxed out.  Which bodes well for unemployment and wages.  What does that mean for corporate profits and stocks?  It means that the top line (revenues) will have to drive profit growth.  Tepid economic growth will mean stagnant profits.

The SEC has launched an “informal inquiry” into the private equity industry. What a shock. It must be nice to have government agencies with subpoena power to conduct oppo research. (Couldn’t the NYT find a more menacing picture of Henry Kravis?)

No economic data today.  I am very interested to see the minutes of the FOMC meeting on Wednesday.

NOT ENOUGH MDs

We here have been educated to understand the supply problem in American health care, thanks to NoVAH, Mike, and Michigoose, although many, if not all, of us understood the general outlines of this basic issue before we got here. This morning we read this:

http://www.washingtonpost.com/blogs/ezra-klein/post/the-health-reform-laws-biggest-threat-30000-too-few-doctors/2012/02/10/gIQALEQp4Q_blog.html?wpisrc=nl_wonk

What I did not know, until I read this article, is that Medicare covers the lion’s share of the cost of training medical residents.  Further, in order to make ACA’s package politically marketable, in the negotiations, there was no increase in the funding for residents.  Thus ACA built into itself the seeds of its own failure, and this is what NoVAH has been saying to us, although I don’t recall his having pointed to the failure to increase funding for residents.

When I read ACA in detail for my clients, I looked at it from the POV of the effect on small biz, which I decided was actually nil, for my clients.  A myopic view, I admit, but it fit my assignment.  A shortfall of 30000 new doctors in a near time frame will greatly increase health care costs above what they would have been if 30000 new docs had been trained.

Funday Sunnies

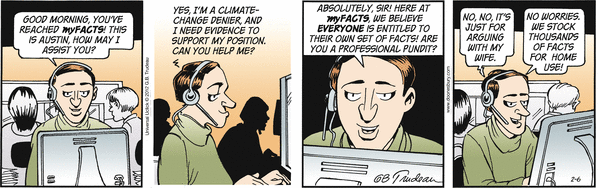
I don’t want to step on any toes, but here are some politically tinged comic strips which made me chuckle this week. Doonesbury ran with this concept all week, which kept getting funnier and funnier:

Doonesbury

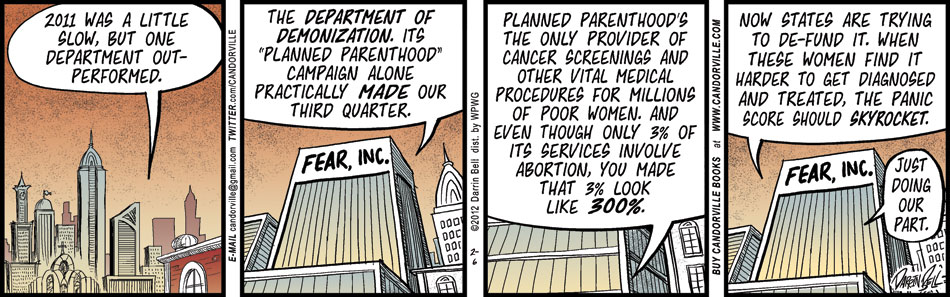
Given the lead time of newspaper comic strips, this one was rather presciently timed to coincide with the Komen Kerfuffle:

Candorville 2-10-2012

Candorville

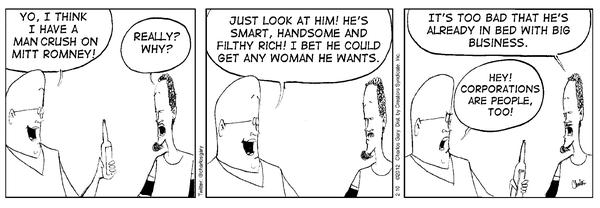
And that Mitt Romney is one handsome devil:

Cafe Con Leche 2/10/2012

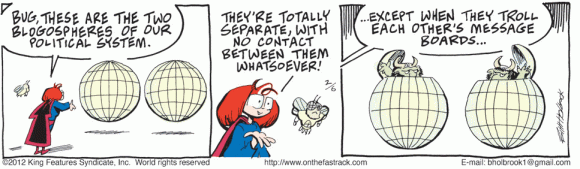
Finally, this one in particular seems to sum up what is wrong with the internet:

On The Fastrack 2/6/2012

On The Fastrack

See you in the funny papers.

(edited to increase image size and add hyperlinks)