Weekend Report

Fix income inequality with $10 million loans for everyone!

By Sheila Bair, Published: April 13

Are you concerned about growing income inequality in America? Are you resentful of all that wealth concentrated in the 1 percent? I’ve got the perfect solution, a modest proposal that involves just a small adjustment in the Federal Reserve’s easy monetary policy. Best of all, it will mean that none of us have to work for a living anymore.

For several years now, the Fed has been making money available to the financial sector at near-zero interest rates. Big banks and hedge funds, among others, have taken this cheap money and invested it in securities with high yields. This type of profit-making, called the “carry trade,” has been enormously profitable for them.

So why not let everyone participate?

Under my plan, each American household could borrow $10 million from the Fed at zero interest. The more conservative among us can take that money and buy 10-year Treasury bonds. At the current 2 percent annual interest rate, we can pocket a nice $200,000 a year to live on. The more adventuresome can buy 10-year Greek debt at 21 percent, for an annual income of $2.1 million. Or if Greece is a little too risky for you, go with Portugal, at about 12 percent, or $1.2 million dollars a year. (No sense in getting greedy.)

Think of what we can do with all that money. We can pay off our underwater mortgages and replenish our retirement accounts without spending one day schlepping into the office. With a few quick keystrokes, we’ll be golden for the next 10 years.

Of course, we will have to persuade Congress to pass a law authorizing all this Fed lending, but that shouldn’t be hard. Congress is really good at spending money, so long as lawmakers don’t have to come up with a way to pay for it. Just look at the way the Democrats agreed to extend the Bush tax cuts if the Republicans agreed to cut Social Security taxes and extend unemployment benefits. Who says bipartisanship is dead?

And while that deal blew bigger holes in the deficit, my proposal won’t cost taxpayers anything because the Fed is just going to print the money. All we need is about $1,200 trillion, or $10 million for 120 million households. We will all cross our hearts and promise to pay the money back in full after 10 years so the Fed won’t lose any dough. It can hold our Portuguese debt as collateral just to make sure.

Because we will be making money in basically the same way as hedge fund managers, we should have to pay only 15 percent in taxes, just like they do. And since we will be earning money through investments, not work, we won’t have to pay Social Security taxes or Medicare premiums. That means no more money will go into these programs, but so what? No one will need them anymore, with all the cash we’ll be raking in thanks to our cheap loans from the Fed.

Come to think of it, by getting rid of work, we can eliminate a lot of government programs. For instance, who needs unemployment benefits and job retraining when everyone has joined the investor class? And forget the trade deficit. Heck, we want those foreign workers to keep providing us with goods and services.

We can stop worrying about education, too. Who needs to understand the value of pi or the history of civilization when all you have to do to make a living is order up a few trades? Let the kids stay home with us. They can play video games while we pop bonbons and watch the soaps and talk shows. The liberals will love this plan because it reduces income inequality; the conservatives will love it because it promotes family time.

I’m really excited! This is the best American financial innovation since liar loans and pick-a-payment mortgages. I can’t wait to get my super PAC started to help candidates who support this important cause. I think I will call my proposal the “Get Rid of Employment and Education Directive.”

Some may worry about inflation and long-term stability under my proposal. I say they lack faith in our country. So what if it cost 50 billion marks to mail a letter when the German central bank tried printing money to pay idle workers in 1923?

That couldn’t happen here. This is America. Why should hedge funds and big financial institutions get all the goodies?

Look out 1 percent, here we come.

outlook@washpost.com

Sheila Bair is a former chairman of the Federal Deposit Insurance Corp. and a regular contributor to Fortune Magazine.

Morning report

Vital Statistics:

Last Change Percent
S&P Futures 1377.7 -8.2 -0.59%
Eurostoxx Index 2316.8 -35.4 -1.51%
Oil (WTI) 103.1 -0.5 -0.49%
LIBOR 0.466 -0.001 -0.11%
US Dollar Index (DXY) 79.53 0.249 0.31%
10 Year Govt Bond Yield 2.01% -0.04%
RPX Composite Real Estate Index 171.3 0.3
Markets are weaker this morning after a disappointing GDP report out of China. The Consumer Price Index showed prices increasing 2.7%, which was more or less in line with expectations. Stocks and bonds didn’t react much to the data. Google, JP Morgan, and Wells Fargo all reported better than expected earnings and are flat to slightly down pre-market.
JP Morgan reported better than expected earnings this morning. The highlight has been the mortgage origination which contributed $1.6 billion in revenue, an increase of 80% from Q111. Servicing revenue dropped 5% and the entire activity broke even. A Bloomberg story on Morgan’s earnings cites a Friedman Billings analyst who thinks Q2 will be the best quarter for the mortgage business in a long time.
Christine Lagarde (head of the IMF) urged the US government to pursue a policy of principal reduction in mortgage debt. As I have discussed in prior posts, that probably isn’t going to happen, at least with respect to conforming loans. Still, I don’t rule out some sort of mortgage relief given that this is an election year.
Google is trying a new wrinkle in corporate governance. As part of their earnings release last night, they announced a stock split. Sort of. Google has two classes of shares – the supervoting shares held by the founders, and the reduced vote shares that currently trade. They are introducing a third share which will be nonvoting. Google shareholders will get as a dividend 1 share of nonvoting stock. The new stock will be used for employee equity-based compensation and other corporate uses, which means Google can issue stock without diluting Sergey and Larry’s control over the company.

Morning Report

Vital Statistics:

Last Change Percent
S&P Futures 1365.9 1.9 0.14%
Eurostoxx Index 2318.7 -22.7 -0.97%
Oil (WTI) 102.8 0.1 0.06%
LIBOR 0.467 -0.002 -0.43%
US Dollar Index (DXY) 79.57 -0.230 -0.29%
10 Year Govt Bond Yield 2.02% -0.02%
RPX Composite Real Estate Index 171 0.2
Equity markets are generally flat after early strength was given back on disappointing economic data. Bonds have reversed earlier declines and MBS are up as well.
The PPI showed that wholesale price inflation remains broadly in check, although the core numbers (ex-food and energy) were slightly higher than expected, running at 2.9%. Initial Jobless Claims were much higher than expected, 380k vs 355k. The trade deficit was lower than expected due to a drop in imports. Futures sold off on the numbers. Some of the other indicators (NAPM, ISM) have been coming in weak as well, signalling the economy might be headed for a slowdown.
The market may be picking up on the sheer amount of fiscal tightening that is scheduled to begin on Jan 1, as the Bush tax cuts expire and the budget cuts from the debt ceiling debates kick in. Of course, no one really wants this to happen, but it is an election year, and they will take effect if nothing happens to stop it. So the market is probably going to start handicapping this a little.
Bill Gross continues to cut Treasuries and buy MBS. This is basically a bet that the Fed will continue Operation Twist in a different way after it expires in June – by trying to influence mortgage rates directly by buying current coupon MBS and repoing short.
RealtyTrac released its US Foreclosure Market Report for Q1, noting that foreclosure activity was the lowest since Q407. Activity dropped in the non-judicial states and increased in the judicial ones. Foreclosure starts have been ticking up, and everyone expects a wave of foreclosures to hit the market as the shadow inventory gets liquidated.
Janet Yellen said that the Fed may have to maintain ultra-low interest rates even beyond 2014. Yellen is one of the more dovish members of the FOMC, and her statements stand in contrast to other members who are noting pricing pressures.
In earnings, Google and Nationstar report after the close. JP Morgan and Wells Fargo report Friday before the open.

NHL Picks

I will have nothing to say on health policy for awhile. My schedule is packed from here until early June.

Pens in 6
Bruins in 5
Devils in 5
Rangers in 6

Kings in 7
Blues in 6
Blackhawks in 7
Predators in 7

Pens over Preds in 6
Fluery is your Conn Smythe winner — only because Malkin won’t be able to abuse Ruk’s team, as seen below:

Morning Report

Vital Statistics:

Last Change Percent
S&P Futures 1367.0 9.9 0.73%
Eurostoxx Index 2353.9 32.4 1.39%
Oil (WTI) 101.25 0.2 0.23%
LIBOR 0.4687 -0.001 -0.11%
US Dollar Index (DXY) 79.641 -0.219 -0.27%
10 Year Govt Bond Yield 2.03% 0.04%
RPX Composite Real Estate Index 170.77 0.2
Equity markets are firmer as the sell-off takes a breather and investors digest Alcoa’s numbers. Spanish yields are lower as well. Italy sold 11 billion euros of T-bills at 2.84% vs 1.405% a month ago. Bonds are a touch weaker and MBS are flat. Mortgage applications were down 2.4% last week.
As Spain becomes the latest worry, the natural question becomes “Who holds the old maid?” Not the Japanese, who cut their exposures to all but the highest Euro credit last year.
The CFPB has put out proposed rules for servicers aimed at improving transparency and accountability. Certainly the tone of the piece (putting “service” back into servicing and “preventing runarounds”) suggests the government is going to regulate servicers more closely, and partially explains why you can’t give away MSRs these days.
Everyone is trying to read the tea leaves on Acting FHFA Director Ed DeMarco’s commentsregarding principal forgiveness for conforming loans. Some saw a change in tone. Others did not. The problem with principal forgiveness is that someone has to eat the losses. There certainly does not appear to be the political appetite to pass losses on underwater homes to taxpayers, and members of Congress realize their state pension funds (not to mention their own!) would get slammed if the losses were passed to them. Neither option is particularly appetizing to politicians on either side of the aisle. So, Ed DeMarco remains a very convenient guy in Washington, allowing the Left to fulminate over his obstinate refusal to budge on principal reductions, safe in the knowledge that they won’t have to face the consequences of what they advocate.
Are lenders moving back out on the risk curve? Seems like it, at least as far as credit cards and auto loans are concerned. Aside from a few hard money lenders, we aren’t seeing this in the mortgage business yet, as it remains impossible to securitize this sort of paper.

Florence and the 4th Amendment

I promised Mark I’d post some thoughts on Florence v. Board of Freeholders, the recent 4th Amendment case from SCOTUS. Since this post isn’t a scholarly document, I’m not going to provide extensive references or links.  My sources are the opinions from the various cases, which can be found at various sites on the web.

First, a brief summary of the case from Lyle Denniston at SCOTUSblog:

Insisting that it has no expertise in how to run a jail or prison, the Supreme Court divided 5-4 Monday in ruling that every person arrested and held temporarily can be subjected to a routine strip search, so long as it involves only a visual inspection without touching or abusive gestures.  The prisoner, however, may be told to manipulate some part of the body.  Some difference of emphasis among the five Justices in the majority made it appear that the decision might be more limited than at first glance.

The ruling, it appeared, did not authorize jail officials to conduct a strip search unless the prisoner was to be placed among other prisoners at the facility.  Two Justices wrote separately in an effort to stress that aspect of the ruling, and their votes were essential to the 5-4 result.

The decision was a clear defeat for challengers to strip searches as a general policy.  The Court explicitly refused to limit the authority to use strip searches only to situations in which a specific individual gave officers a reason to consider that prisoner to be dangerous or likely to be carrying a concealed weapon or drugs.   The same kind of visual inspection of an arrestee’s naked body, the Court declared, can be applied to anyone placed in the general population of a jail or prison, even if only temporarily.

If you’re still interested, then there is more below.

Continue reading →

Morning Report

Vital Statistics:

Last Change Percent
S&P Futures 1377.0 2.1 0.15%
Eurostoxx Index 2359.4 -33.1 -1.38%
Oil (WTI) 102.05 -0.4 -0.40%
LIBOR 0.4692 0.000
0.00%
US Dollar Index (DXY) 79.863 0.130 0.16%
10 Year Govt Bond Yield 2.05% 0.00%
RPX Composite Real Estate Index 170.57 0.0
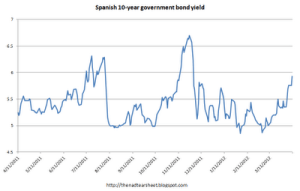
Markets are generally weaker as Europe plays catch-up with the US markets. US bonds and MBS are flat. Spanish yields are 17 basis points higher on no major economic news. An unexpected drop in imports pushed the Chinese trade balance into a surplus and is flashing warning signs about Chinese domestic demand.
With Greece temporarily off the front pages, all eyes turn to Spain. The new Spanish government is determined to implement austerity measures and reduce the budget deficit by almost 2/3 in 2013. Spain had a massive property bubble, which has weakened their banking system considerably. The banks are thought to be marking their real estate portfolios and mortgage bonds at unrealistic levels.
One powerful method of clearing the excess housing inventory is the short sale, and often times it is a lengthy, painful process as banks and other creditors drag their feet, hoping for better prices. Senator Sherrod Brown (D-OH) has introduced legislation to force banks to make a decision within 75 days of a request from a homeowner.
Bloomberg has been tracking a story about J.P. Morgan’s massive credit default swap positions in their Treasury department, which is raising questions about Dodd-Frank and proprietary trading versus hedging. The trader, Bruno Iksil, has been selling protection on an index of investment-grade bonds (Markit CDX North America Investment Grade Series 9) and is thought to have sold $100 billion worth of protection on the index. This is the trade that blew up AIG and I cannot imagine what it possibly could be hedging. As a bank, JP Morgan generally makes loans so it makes money if US corporations generally do well, and poorly when US corporations don’t do well. Selling protection is the exact same bet. The article goes on to speculate that this may be part of a spread trade, but even then a spread trade is a speculative position, not a hedge. Anyway, regulators and politicians seem to be lining up against this trade, and if JP Morgan is forced out, they will undoubtedly pay dearly to exit.
Chart: Spanish 10-year government bond yields

Morning Report

Vital Statistics:

Last Change Percent
S&P Futures 1374.7 -15.5 -1.11%
Eurostoxx Index 2392.5 -5.9 -0.25%
Oil (WTI) 101.65 -1.7 -1.61%
LIBOR 0.4692 0.000 0.00%
US Dollar Index (DXY) 79.92 0.034 0.04%
10 Year Govt Bond Yield 2.03% -0.02%
RPX Composite Real Estate Index 170.61 -0.1

Slow news day.

Equity futures are lower on the back of Friday’s lousy employment report. Bonds and MBS are rallying, with the 10-year again flirting with a 2% yield. European markets are closed for the Easter holiday, so volumes will be light.

Friday’s employment report showed an increase in 120,000 private sector jobs and a drop in the unemployment rate to 8.2%. The reason for the drop in unemployment was due to a drop in the labor force participation rate, which has fallen from 64% to 63.8% since December. These are the 99-ers who have exhausted their unemployment benefits and no longer count as part of the labor force.

Alcoa kicks off Q1 reporting season tomorrow after the close.

Bites & Pieces (Passover/Good Friday/Easter Edition)


Mark shared with us his Italian Jewish version of Passover soup last night (and I’m looking forward to trying it, Mark!); I didn’t know about the split over rice.  The things you learn on this blog!

At any rate, here is my take on Matzoh Ball Passover soup (which you won’t have time to make for tonight, but there’s always next year!) and a few Easter recipes for your viewing pleasure.


Chicken Soup with Matzoh Balls

For the soup (which I usually make a day or two ahead; basically I make chicken stock since I remove all of the solids):

  • 1 3- 4 lb chicken (or I often use a bunch of chicken thighs instead)
  • Kosher salt
  • 4 celery stalks, roughly chopped
  • 2 large carrots, roughly chopped
  • 1 onion cut in eighths
  • 2 leeks, thoroughly rinsed and roughly chopped
  • 3 garlic cloves, peeled
  • 4 sprigs flat-leaf parsley
  • 3 sprigs dill
  • 1/2 tsp peppercorns
  • 2 bay leaves

Rub chicken (if using whole chicken) inside and out with salt and let sit for about 15 minutes.  Rinse thoroughly, place in a large stockpot and add water to cover by three inches.  Bring to a boil over high heat and skim off foam until it stops appearing.  At that point, add the rest of the ingredients, reduce heat to medium low and simmer until chicken is falling off the bones.

Remove the chicken from the pot and remove the bones, placing them back into the soup–save the meat for another use.  Simmer for another hour, then strain all solids out through a couple layers of cheesecloth, cover the soup and refrigerate until the fat on top solidifies and can be removed.  Wise and experienced cooks will keep this schmaltz wrapped in the refrigerator for wonderful uses later.

For the matzoh balls (this part of the recipe is from a genuine Jewish grandmother who lives in NYC):

  • 4 eggs
  • 1/2 cup seltzer
  • 1 tsp salt
  • Dash black pepper
  • 1 cup matzoh meal
  • 1/2 cup melted shortening (or schmaltz)

Beat the eggs, then add the seltzer, salt and pepper.  Add the matzoh meal and shortening, mixing well.  Cover and refrigerate overnight.

Put a large pot of salted water on to boil, then wet your hands in cold water and form walnut-sized balls with the matzoh dough.  When the water comes to a boil add the balls and simmer, covered for 45 minutes.  Do not remove the cover until done.

The last line of the e-mail when she sent me the recipe:  “If they are good I get all the credit, if not it’s yours.  Enjoy!”


Lamb with Yogurt Sauce

What is more traditional than lamb at Easter?  This is one of my favorite ways to fix it.

  • 1 5 – 6 lb leg of lamb
  • 4 garlic cloves, thinly sliced

For the marinade:

  • 1 tbs garlic, minced
  • 3 tbs dried oregano
  • 1/2 cup lemon juice (~2 lemon’s worth)
  • 1/2 cup EVOO
  • 1 cup dry red wine

For the yogurt sauce:

  • 2 cups plain nonfat yogurt
  • 1 small cucumber peeled, seeded and coarsely grated
  • 2 garlic cloves, minced
  • 2 tbs really good EVOO
  • 2 tbs lemon juice
  • 3 tbs fresh mint, chopped

Make incisions in the lamb and insert the garlic slices into the holes.

Whisk the marinade together and add the lamb.  Marinate overnight in the refrigerator.

Line a sieve with cheesecloth and place it over a bowl.  Place the yogurt in the sieve and let drain overnight in the refrigerator. . . or use Greek yogurt for this and skip this step.

Preheat oven to 375 degrees, remove the lamb from the marinade, salt and pepper and place in a roasting pan.  Roast, basting occasionally with the reserved marinade until the lamb is 135 degrees.

Finish making the sauce by placing the cucumber in a sieve and salting heavily; let drain for 30 minutes, then rinse thoroughly and squeeze the cucumber dry.  Add the cucumber and remaining ingredients to the drained yogurt and mix thoroughly.

After the lamb rests for 5 – 10 minutes, slice and serve with the yogurt sauce.


Hot Cross Buns

A Betty Crocker Classic

  • 1/2 cup warm water
  • 2 pkg active dry yeast
  • 1/2 cup lukewarm milk
  • 3/4 cup unseasoned mashed potatoes
  • 1/2 cup sugar
  •  1 1/4 tsp salt
  • 1/2 cup butter
  • 2 eggs
  • 1 cup raisins
  • 1 tsp cinnamon
  • 1/4 tsp nutmeg
  • Half of 4 1/2 cups sifted AP flour

Add the yeast to the water and stir to dissolve

Stir the remaining ingredients into the yeast until smooth, then continue adding flour, mixing by hand, until the dough handles easily.  Turn onto a lightly floured board and knead until smooth.

Let dough rise until doubled (about 1 1/2 hours), then punch down and divide in two.  Shape each part into 16 buns.  Place in 2 greased 9″ baking pans (or 2″ apart on a greased baking sheet).  Let rise until double (~30 minutes).  Brush with an egg yolk glaze (1 egg yolk beaten with 2 tbs water) and bake for 20 – 25 minutes. Cool slightly, then make a cross on top with white icing.


Deviled Eggs


Why?  I have no idea why this is considered a traditional Easter food, but two different people told me that, and one of them is my Mom, so who am I to argue?
 

  • 6 hard-cooked eggs
  • 1/2 tsp salt
  • 1/4 tsp pepper
  • 1/2 tsp dry mustard
  • ~3 tbs vinegar or salad dressing to moisten filling

Cut eggs in half and remove yolks.  Mash yolks with remaining ingredients, then refill the whites, heaping the filling up lightly. Dust with paprika and serve.


A  joyous holiday weekend to all, no matter what your persuasion!  And feel free to edit this post to drop in your own recipes. . .

Faux Morning Report

Vital Statistics:

Last Change Percent
S&P Futures 1398.0 10.0 0.7%
Eurostoxx Index 2392.54 19.24 .8%
Oil (WTI) 100.31 -1.35 -1.33%
LIBOR 0.4692 0.000 0.00%
US Dollar Index (DXY) 80.046 0.268 0.34%
10 Year Govt Bond Yield 2.055% -0.105%
RPX Composite Real Estate Index 170.92 0.3

Almost all markets are closed today except for the USD fixed income market, so all Vital Statistics numbers are actually from yesterday’s close, except for the the 10y treasury yield.

Labor statistics came out this morning at 8:30. Change in non-farm payrolls came in at a very disappointing 120k (205k expected) with only a minor revision upward for last month, up 13k to 240k. Manufacturing jobs were up 37k, higher than expected (20k), and the unemployment rate fell again to 8.2% from last month’s 8.3%. But overall the numbers were very disappointing, which was reflected in the reaction of the only market open for trading.

Interesting price action on the treasuries right before today’s employment data came out. After closing yesterday at a yield of around 2.17%, the 10yr note hit 2.24% about 2 minutes before the numbers were released, and then with the disappointing employment data, the market rallied tremendously, and is now at 2.05%. The markets are somewhat illiquid with Europe on holiday and even a lot of the US market taking Good Friday off, so that can explain some of the large movement. Not a lot of people around to cover the large amount of buying after the number. But still the market seems to be hoping for, and betting on, some form of QE III, despite the minutes from last month’s Fed meeting ostensibly quelling that possibilty.

Futures markets close in about 5 minutes (11:15 EST) and the bonds will close by 1pm. So the day is pretty much over now. Europe is closed on Monday as well, so it will be interesting to see how the Euroean markets react on Tuesday to the violent move in US after a 4 day layoff. But Sunday night in Asia and then Monday morning should give us some idea if this rally is a bit overdone or if the market really is intent on seeing sub 2.00% yields again on the 10yr.

Happy Easter and Happy Passover to all who celebrate those things. To the rest…it’s looking like golfing weather is finally here.