Best “Whole” Album

I’m taking a page from Ace of Spades,

http://minx.cc/?post=336709

What are the best whole albums? The one’s where every song is great. The author of the post listed the following:

“#1 Dark Side of the Moon, #2 Back in Black, #3 Led Zepplin IV, #4 Who’s Next, #5 Joshua Tree, #6 London Calling, #7 Van Halen, #8 The Cars, #9 Purple Rain, #10 Appetite for Destruction,, with Honorable Mentions to: Quadrophenia, Synchronicity, Making Movies, Los Angeles (X), Bloodletting, Pet Sounds, Armed Forces, Yellow Brick Road, Revolver, Holy Diver, Paulie’s Boutique, Hysteria, OK Computer, Violator, and In the Court of the Crimson King. “

Some I agree with and some I think are wrong. I would add (or substitute):

Allman Bros., Eat a Peach as well as
Live at the Filmore East
Led Zepplin, Led Zepplin II
Sex Pistols, Never Mind the Bullocks
Bob Dylan, Blood on the Tracks
AC/DC, Dirty Deeds
Lynyrd Skynyrd, Pronounced

I’ll add more in the comments. Ace’s commenter’s skew younger than me, but there are some great suggestions in there.

What about your favorites?

Latest interview on Capital Markets Today

We discuss the fiscal cliff, sequestration cuts, debt ceiling, QM rules, Jack Lew, Fexit, and 2013 economic forecasts


http://tobtr.com/s/4257903

Morning Report – Housing starts and bank earnings 01/17/13

Vital Statistics:

  Last Change Percent
S&P Futures  1471.6 6.0 0.41%
Eurostoxx Index 2710.7 8.2 0.30%
Oil (WTI) 94.8 0.6 0.59%
LIBOR 0.302 -0.001 -0.33%
US Dollar Index (DXY) 79.61 -0.198 -0.25%
10 Year Govt Bond Yield 1.87% 0.05%  
RPX Composite Real Estate Index 191.7 0.3  

Markets are higher after a good housing starts number and lower than expected unemployment claims. Bank of America and Citi both reported lower than expected 4Q earnings. Bonds and MBS are down.

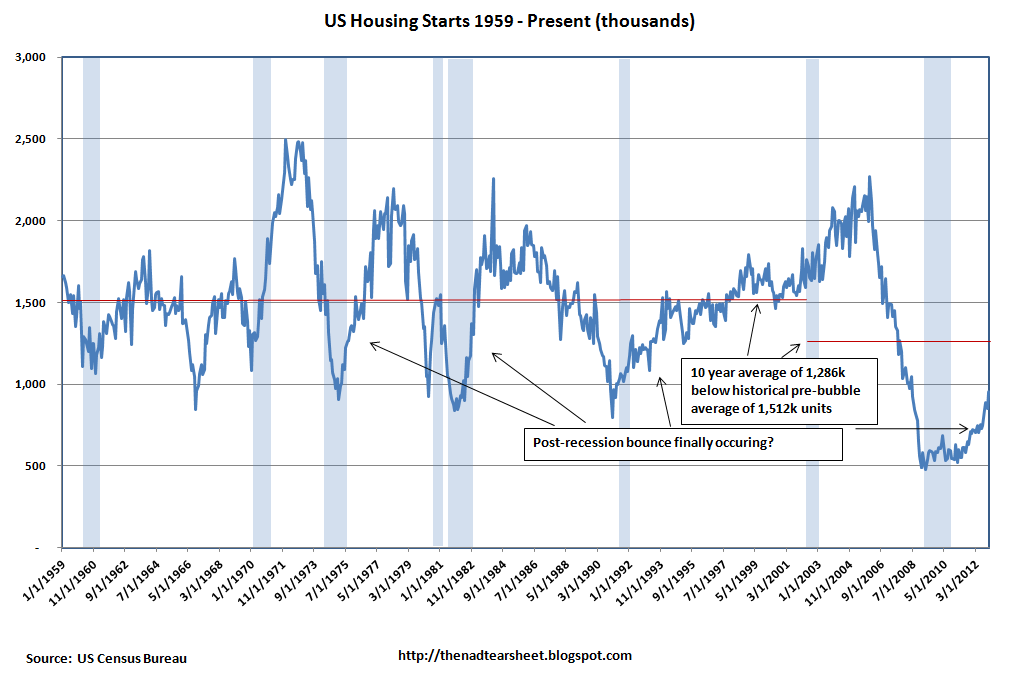
Housing starts took a big jump upward in December, to an annualized pace of 954k, an annualized increase of over 100k. This is the highest level since June 2008. Multi-family starts accounted for about a third of the increase.  Building Permits increased at a 1.8% MOM and 29% YOY.  Remember, we have historically started 1.5 million units per year, and our 954k annual number basically represents the low points of all recessions since 1957 up to the post-bubble recession.

Chart:  Housing Starts


The CFPB is releasing new rules for servicers today.  It essentially eliminates the practice of “dual tracking” where a servicer works to mod a loan and simultaneously initiates foreclosure proceedings in case the mod doesn’t work out or the borrower fails to pay.  That might have the unintended consequence of less mods and more foreclosures.  Foreclosures cannot be initiated until the account is more than 120 days delinquent. This rule pre-empts state law, so timelines will get extended in non-judicial states. Servicers with less than 5,000 loans will be exempt.

Speaking of unintended consequences, the Fed is now worried about bubbles in farmland and junk bonds, the direct result of QE. Unwinding QE (it needs a name – Fed Exit – Fexit?) will be a touchy deal.  The buzzword for Fexit will be “convexity risk” Think Orange County in 1994 on steroids.  Not only will MBS bids fade because of interest rate volatility, they will also have to contend with the Fed dumping paper in an effort to shrink its balance sheet.  A 2014 recession is a distinct possibility. 

What it took to get a mortgage in 2012, according to Ellie Mae:  748 FICO, 23/34 DTI, 21% down.  Average interest rate 3.9%, average time to close, 48 days, 62% were refis. 

Morning Report – What a difference a year makes. 01/16/13

Vital Statistics:

  Last Change Percent
S&P Futures  1462.4 -2.8 -0.19%
Eurostoxx Index 2688.7 -12.9 -0.48%
Oil (WTI) 93.32 0.0 0.04%
LIBOR 0.303 0.000 0.00%
US Dollar Index (DXY) 79.86 0.085 0.11%
10 Year Govt Bond Yield 1.80% -0.03%  
RPX Composite Real Estate Index 191.7 0.3  

Markets are weaker this morning after the World Bank cut its global growth forecast.  Goldman and JP Morgan both reported better than expected earnings. Mortgage applications rose 15% last week and the CPI showed that inflation remains under control. Industrial production rose .3% and capacity utilization rose to 78.8%.  Bonds and MBS are up.

The National Association  Homebuilders Confidence index held at 47 in January, the highest level since April of 2006. A reading of 50 represents the point where builders view conditions as neutral. Conditions improved in all areas of the country, with the West performing the best, while the Midwest and Northeast performing the worst. This is the second sentiment report that has the “what a difference a year makes” theme.

The CoreLogic Home Price Index rose 7.4% YOY in Nov 2012. This is the largest gain since May of 2006.   Excluding distressed sales, home price increased nationally by 6.7%.  December’s gain is forecast to be down .5% MOM (reflecting the typical seasonal pattern) and will be up 8.4% YOY. Mark Fleming, the Chief Economist made a point about QM – “that the recently released Qualified Mortgage rules issued by the CFPB are not expected to significantly restrict credit availability relative to today.”  I am sure Cordray is breathing a sigh of relief on that one… the point of the QM rule was to expand credit.  

Bank of America is intent on growing the mortgage business again after a hasty retreat in 2011. Of course this meant they missed the mother of all refinancing booms. They exited the wholesale business and basically ceded the market leader position to Wells Fargo. It also signals that they believe the worst is behind them with respect to Countrywide. 

It is looking more and more like Republicans will not force a showdown on the debt ceiling (though “clean” debt ceiling increases have been rare in the past).  The polls aren’t with them and the politics aren’t there. Republicans will probably save spending cut demands for the sequester and the continuing resolution.

It looks like the case against Stevie Cohen has hit a wall.


Morning Report – The Debt Ceiling Dance 01/15/13

Vital Statistics:

  Last Change Percent
S&P Futures  1457.5 -6.8 -0.46%
Eurostoxx Index 2701.4 -13.7 -0.51%
Oil (WTI) 93.67 -0.5 -0.50%
LIBOR 0.303 -0.001 -0.33%
US Dollar Index (DXY) 79.65 0.158 0.20%
10 Year Govt Bond Yield 1.82% -0.02%  
RPX Composite Real Estate Index 191.9 0.0  

Futures are deteriorating on fears that Congress won’t find a way to raise the debt ceiling. Fitch ratings said that it would put the US credit rating under review for a downgrade if there is a delay in raising the debt ceiling. The Bernank weighed in on the debt ceiling at the University of Michigan yesterday. The producer price index showed inflation remains under control at the wholesale level and Dec retail sales were better than expected.  Bonds and MBS are up.

The Empire State Manufacturing Survey indicated that conditions for New York State manufacturers continued to decline at a modest pace. Roughly 20% of businesses surveyed expected to increase payroll, while the same number expect to decrease payroll. Capital Expenditures dropped again to its lowest level since 2009. That said, the outlook for 2013 remained mildly positive.

Lennar reported a profit of 56 cents a share for the 4th quarter and FY12 EPS of $3.11 a share.  Revenues were up 42% in Q4, and backlog was up 32%. Margins also increased.  The CEO noted that the housing recovery seemed to accelerate in Q4 as low mortgage rates, affordable home prices, lower foreclosures and a compelling rent vs own comparison drove the recovery.  

The CoreLogic Market Pulse showed that 2012 was better than expected for the housing market. They raise a good point though, that 2012 had no major economic shocks – no Japanese tsunami, no debt ceiling debate / downgrades, no major blow-ups of big financial entities. They characterize 2012 as “a year in recovery, but not one in which the country has actually recovered.”  They foresee further recovery next year, but note that supply has been constrained as many move-up buyers have been underwater.  As prices rise, those properties will be put back on the market. As the economy recovers, the first-time homebuyer will become in a better position to purchase these properties, which will provide the increased demand to meet the increased supply. 

The debt ceiling debate has been getting more confrontational, with the President using hostage-taking metaphors during his speech yesterday. Sen Pat Toomey (R-PA) has introduced a bill to avert default by requiring Treasury to prioritize payments (with interest, SS, and active duty military pay taking precedence) and allowing them to borrow just enough to cover those expenses if revenues aren’t enough. My personal belief is that Republicans know the politics aren’t there for a debt ceiling standoff, but they will accept the full sequestration cuts. The sequestration cuts were designed to never happen – the cuts were supposed to be unpalatable to both sides.  Much to the surprise of Democrats, Republicans are more comfortable with cutting defense than they thought, which means that the roughly $109 billion of spending in 2013 will get left on the cutting room floor. 

To put the sequestration into perspective:  the 2012 budget was $3.729 trillion.  The 2013 budget is $3.803 trillion.  The increase is roughly $74 billion.  In other words, the actual cut to government spending is $109 billion – $74 billion or about $35 billion.  $35 billion is 22 basis points of GDP. We are currently spending 24% of GDP, while the highest taxes as a percent of GDP have ever gotten in a touch over 20%, primarily during the equity bubble when capital gains tax receipts were huge. To get spending down to where we are able to balance the budget under the best of conditions, we would need to lop off $567B from 2012, or about 4% of GDP.  Republicans would be wise to give Obama what he wants on the debt ceiling and then force the Administration to explain why cutting spending by 22 basis points of GDP is somehow intolerable. Of course, the Administration has already telegraphed how it will fight this battle (terrorists will run wild, pollution will increase, airplane accidents will happen, we won’t be able to deal with natural disasters) so Republicans will be well advised to separate out the necessary functions of the government (basic safety net, FAA, FBI, FDA, etc) from the “nice-to-haves” like foreign aid to places like Egypt, agricultural subsidies, green energy subsidies, etc.

Morning Report – The week ahead 01/14/13

Vital Statistics:

  Last Change Percent
S&P Futures  1466.5 -0.7 -0.05%
Eurostoxx Index 2720.1 2.3 0.08%
Oil (WTI) 93.97 0.4 0.44%
LIBOR 0.304 0.000 0.00%
US Dollar Index (DXY) 79.6 0.041 0.05%
10 Year Govt Bond Yield 1.84% -0.02%  
RPX Composite Real Estate Index 191.9 0.4  

Markets are down small after disappointing iPhone data out of Apple. There is no economic data this morning, although the Bernank speaks at the University of Michigan after the close. This week will be heavy with bank earnings, with US Bancorp, JP Morgan, Goldman, Bank of America all reporting 4Q / full year.  Wed and Thurs are the most interesting economically, with Housing starts and Capacity utilization / Industrial Production.  Bonds are up 1/2 a point while MBS are up small.


David Blitzer of S&P discusses the outlook for housing in 2013. He thinks (a) housing is going to be an outsized contributor to GDP next year and (b) shadow inventory fears are overblown.


Different industry groups weigh in on the QM from the CFPB:


  • The MBA notes that cap on points is moronic when you are comparing different note rates
  • The Center for Responsible Lending complains that prime mortgages are protected under QM
  • The National Association of Federal Credit unions loves the special dispensation for them


Emily Meier, RIP

On behalf on Lulu:

I just received this email from Emily’s husband.

Linda,

Emily died last night at a little after 9. She was peaceful and without pain. She stopped breathing for 15 seconds or so, and then took a big breath. Then stopped again for longer, and then took another breath, not as strong as the first. Then a third, and a fourth. And then no more.

She was a wonderful person and a wonderful wife.

Bob

I’m really going to miss my correspondence with her. She was a terrific friend, a wonderful writer, a devoted wife, mother and grandmother, and a political junkie extraordinaire. She’s at peace now dammit.


I will never forget her generosity, humor, and intelligence, especially demonstrated when she discussed Suite Harmonic with us.

Morning Report – Notes from the CFPB conference 01/11/2013

Vital Statistics:

  Last Change Percent
S&P Futures  1467.5 0.4 0.03%
Eurostoxx Index 2713.3 5.1 0.19%
Oil (WTI) 93.31 -0.5 -0.54%
LIBOR 0.304 -0.001 -0.33%
US Dollar Index (DXY) 79.6 -0.140 -0.18%
10 Year Govt Bond Yield 1.89% 0.00%  
RPX Composite Real Estate Index 191.6 -0.1  

Markets are flattish after Wells Fargo’s earnings beat expectations and import prices showed that inflation remains contained. Bonds and MBS are up small.


Richard Cordray of the CFPB laid out the outlines of what will be considered a qualified mortgage at a presentation in Baltimore yesterday.  Big picture, he believes that lenders were too loose with credit in the past, but now they are too tight.  The Rule will be called Reg Z, or the Ability-to Repay and Qualified Mortgage Standards under the Truth in Lending Act.  These rules are intended to both protect consumers and increase access to credit. The highlights are


  • A cap in points and fees
  • No exotic (IO, increasing principal, 30 year + maturity, balloon) loans
  • DTI < 43%.  Period.  (In other words, nothing on FICO or down payments)
  • DTI ratios must be calculated on the expected long term payment, not teaser rates on ARMs.
  • Provides immunity from homeowner lawsuits under the QM rules for prime loans.  Rebuttable presumption for subprime.
  • Safe harbor is only for homeowner lawsuits under QM rules, all other rules still apply
  • Rules will take effect 1/10/14 and will be phased in over a period of years
  • Community banks / credit unions, and low income lenders will have relaxed standards
There were several housing advocates, consumer advocates, etc on the panel.  For the most part, they lauded the agency, but thought the QM rules were too skewed in favor of the financial industry. They also feared that it would restrict CRA lending. On the other hand, SIFMA praised the rule. The most eye-opening comment came from Cordray himself, when he said that he believed that we would not have had a financial crisis if these “ability to repay” rules would have been in effect before.  Really.  Of course the term “housing bubble” was not uttered during the entire discussion. 
 
Will it increase lending? My sense is that unless the GSEs and FHA agree to insulate lenders from buy-back risk if they follow the QM rules, it will not in any meaningful way.
 
Well Fargo’s earnings release beat expectations on the top line, but net interest margins were disappointing. Particulars regarding mortgage banking:
  • Originations fell from $139B in Q3 to $125B in Q4, reflecting the normal seasonal decline. Originations were up 4% YOY.
  • Pipeline at quarter end was $81 billion, down 16% QOQ and up 13% YOY.
  • Net interest margin declined from 3.89% to 3.56% YOY.  Q3 NIM was 3.66%
  • Total delinquency and foreclosure rate was 7.04% down from 7.96% in Q3
  • They continue to wind down the legacy Wachovia assets.  The “Pick a Pay” loan portfolio has a UPB of $63.8 billion and is being marked at $58.3 billion, or at 91%.  Note, the UPB is ex-writedowns already taken.


Morning Report – QM Day 01/10/13

Vital Statistics:

  Last Change Percent
S&P Futures  1464.7 8.9 0.61%
Eurostoxx Index 2712.4 6.0 0.22%
Oil (WTI) 94.4 1.3 1.40%
LIBOR 0.305 0.000 0.00%
US Dollar Index (DXY) 80.35 -0.206 -0.26%
10 Year Govt Bond Yield 1.90% 0.04%  
RPX Composite Real Estate Index 191.7 -0.3  

Markets are higher this morning after positive news out of Ford and Nokia.  Initial Jobless Claims increased 4k to 371k, higher than the 365k estimate.  The ECB left rates steady and predicted a gradual recovery for the Eurozone this year.  Bonds and MBS are down.

WaPo has a write-up of the new QM rules expected to be released today by Richard Cordray in Baltimore.  You can watch the speech here. Expected changes:  Upfront fees will be capped at 3%, though exceptions will be made for loans under 100k, and IO mortgages will be banned.  Ability to repay will be based not on the teaser rate, but on the expected rate later on.   DTI ratios must be below 43%.  The rules will be phased in over the next 7 years. The CFPB estimates that 75% of the mortgages issued in 2011 would have met the standards. If the banks follow these rules, they will be protected from many homeowner lawsuits, but not necessarily buy-back risk. Jumbos will probably the area most affected by the new rules. MND has the gory details here.

What does the appointment of Jack Lew as Treasury Secretary mean?  That the Administration will be focusing its energy on budget battles going forward. He is not considered (at least by the Left) to be the sort of guy that will be addressing unemployment, or pushing for Keynsian stimulus. As such, he probably isn’t going to be tremendously dollar-negative, although in an era of competitive devaluations, it is hard to be a dollar bear anyway. The tight relationship between the Fed and Treasury will end. He is probably going to be a tough negotiator for the WH’s budget priorities – higher taxes on the rich no no non-defense spending cuts. He also has an unusual signature, (OoooooO) which will be gracing your dollar bills soon enough. 

Acccording to NAR, 2012 will go down as a record year for housing affordability. The index came in at 198.2, which means the median borrower had 198% of the minimum income required to purchase the median price existing family home, assuming 20% down and 25% of income going to P&I payments. Tight credit standards remain the sticking point.

Thinking outside the box:  Instead of paying the unemployed, pay their employers to keep them on. Through the work-sharing plan, employees get a shortened work week, with unemployment benefits partially compensating them for lost wages. 

The hits keep coming:  Morgan Stanley is laying off 1,600 workers.

Battle Royale:  Ackman vs Loeb in Herbalife.

Emily has not yet left the room

She is near death, but her effort to wrench a last drop of beauty from life moved me deeply. I am grateful to Lulu for sharing it with me and I have permission to share it with you.

Here is a poem written in collaboration with my dear friend, Eileen Hunter, as I navigate this confusing time. It was originally titled “Small Blue Trucks.”

“Death Road”
Emily Meier

Smoke swirls across the wall,
One vase of roses becomes six
Bronze globes gild the dining room
The walls are pinball machines.
In the dining room, the kitchen, and a wall of the bedroom,
a pattern of blue and red.
In the living room they are a beauty
of blue and red circle balls.
On the living room walls they are a pattern
of New York News
travelling in black and white,
telling the city’s story.
Small blue trucks with white lights
merge into the scene, quiet and pale.
A mystery. I touch them.
I like the kittens. Eileen does too.