Morning Report – Negative Q4 GDP? 01/30/2013

Vital Statistics:

  Last Change Percent
S&P Futures  1502.2 -2.9 -0.19%
Eurostoxx Index 2741.1 -8.1 -0.30%
Oil (WTI) 97.63 0.1 0.06%
LIBOR 0.299 -0.002 -0.67%
US Dollar Index (DXY) 79.42 -0.142 -0.18%
10 Year Govt Bond Yield 1.99% 0.00%  
RPX Composite Real Estate Index 193.1 -0.3  


Markets are lower on a surprisingly weak 4Q GDP number, which showed the economy contracted by .1%.    The ADP employment change report showed the economy added 192k jobs in January.  Mortgage Applications fell 8% last week.  Later today, we will get the FOMC rate decision. The 10 year, which was above 2% earlier is back down below.  MBS are up small.

The Q4 GDP number was surprisingly weak (the Street was at + 1.1%) and will undoubtedly be revised upward as it does not jive with the other data points out there.  Certainly the earnings reports we are seeing out of Corporate America do not indicate a recession.  This is the “advance” report (the first of three) and is based on incomplete data.  The next estimate will be released at the end of Feb.  

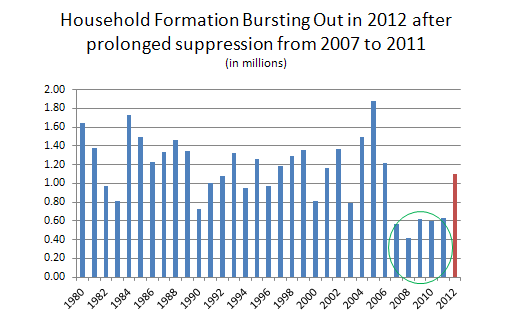
NAR has a good piece on the home ownership rate and household formation. The latest homeownership rate of 65.3% is the lowest since 1996.  Renters have been increasing.  They estimate that household formation broke out of its doldrums in 2012 and will be close to normalcy – around 1.1 million.  Note that this represents pent-up demand for housing as the Great Recession drove the low numbers, not demographics.  Of course some of these new households will go to rentals, but many will start purchasing starter homes, and they are the key to get transactions flowing again. This would also help ease the burden on the sandwich generation.

Chart:  Household Formation:

Looks like the sequester is going to happen, though the recent GDP report may give lawmakers a push to do something about it.  

When the FOMC statement is released, people will be focusing on the end of QE. Aside from the effect on interest rates, there is also the question about the size of the Fed’s balance sheet.  A recent paper projects the Fed’s balance sheet to start contracting in 2015, with a return to a more normal size in early 2018.  The Fed has been highly profitable during QE, since its own buying influences prices and makes its holdings of MBS and Treasuries more valuable. But what happens when they begin to sell?  The Fed may in fact lose money over the next few years, which will undoubtedly bring a political angle into the future role of the Fed.  Whoever succeeds Ben Bernake will, like Paul Volcker, preside over a Fed that will be unpopular, to say the least. 

Morning Report – The Secular Bear 01/29/13

Vital Statistics:

  Last Change Percent
S&P Futures  1492.9 -4.2 -0.28%
Eurostoxx Index 2736.0 -8.5 -0.31%
Oil (WTI) 96.55 0.1 0.11%
LIBOR 0.301 -0.001 -0.33%
US Dollar Index (DXY) 79.8 0.023 0.03%
10 Year Govt Bond Yield 1.96% -0.01%  
RPX Composite Real Estate Index 193.4 0.8  

Stock index futures are weaker as the Fed kicks off its January FOMC meeting. The markets will be parsing the press release looking for clues regarding the end of QE, specifically the timing and the economic variables that influence the decision. Today is a very heavy earnings day, with Danaher, Ford, EMC, International Paper, and Pfizer reporting. Bonds and MBS are up a tick or two.

The S&P Case-Schiller index of home values rose 5.5% YOY and .6% MOM in the month of November.   The hardest hit areas (Phoenix, Detroit, Las Vegas) showed the biggest YOY increases (Phoenix was up 23%!), while the New York declined 1.2% 

DR Horton reported a 39% increase in revenues and a 26% jump in homes closed from a year ago.  Orders were up 39% and backlog was up 62%. Like the other homebuilders, DHI is reporting general strength in their housing markets.  There was a shift towards larger houses as well, as the dollar increase in the value of homes built increased 60%, while the number of units increased 39%.  They are looking forward to the spring selling season with optimism.  The stock is up about 4% pre-open. 

Is the “risk on” trade we have been waiting for since 2007 finally on?  Trim Tabs is reporting that last month was a record month for inflows for stock mutual funds and ETFs – the last time we had inflows of this magnitude was the winter of 2000, right as the tech bubble was bursting.  Time to be cautious or time to break out the champagne?  Reason for optimism:  There are no, repeat no, signs of overheating in the economy.  If anything there is a tremendous amount of pent-up demand.  That is not recessionary, and should therefore be bullish for stocks.  Reason for pessimism:  Interest rates are going up. The great secular bull market in bonds that began with Paul Volcker’s tightening in 1981 is ending. The end of QE will mean long-term rates will rise, and short-term rates will soon follow. Also, we are in a secular bear market for stocks, and those rare animals typically last a lot longer than 12 years. 

This secular bear market in stocks resembles the bear market of the 1970s. with stocks trading in a large range that oscillates over a period of years, while going nowhere.  To put the 1970s in perspective, the Dow Jones Industrial Average was at roughly the same place when I graduated from high school as it was when I was born.  

Chart:  Dow Jones Industrial Average 1965 – 1983: 

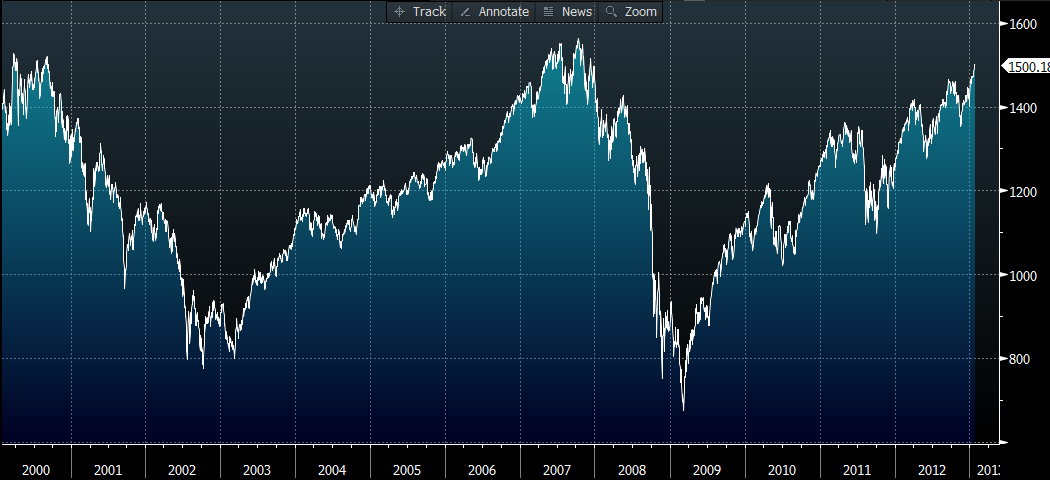
Compare to the S&P 500 since 2000: 


Similar oscillating pattern, with higher highs, and lower lows. If you believe in charts, they suggest a further run to eclipse the previous high and then a swoon lower. So, you might have another 8% – 10% left before the market heads back down again. 

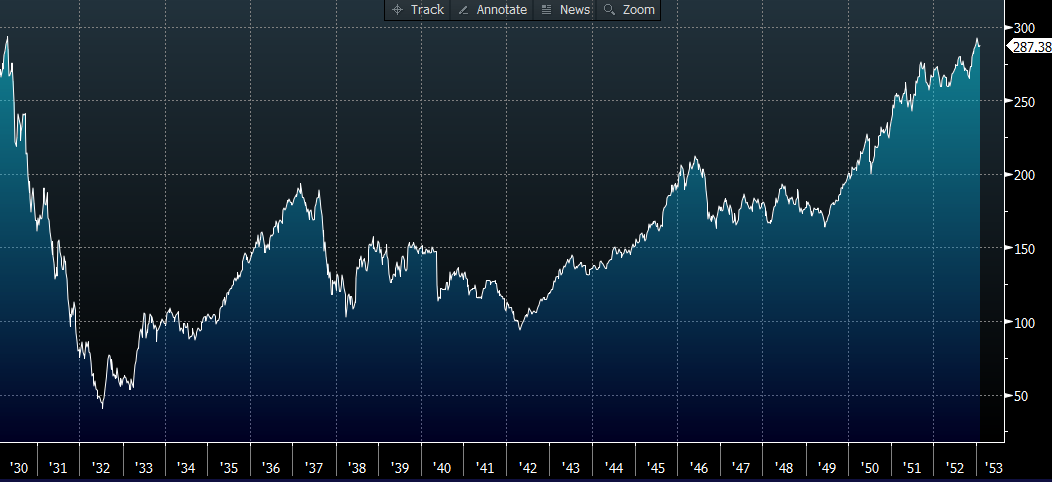
Of course we have one other secular bear market to look at:  the granddaddy of them all:

23 years of a secular bear – it took until 1953 to recover the losses from the 1929 crash.  Some stock market darlings – Radio Corporation of America (aka RCA) never regained its peak from the 1920s. The economic backdrop of deleveraging has a lot more in common with the Depression bear than the 1970s bear which was driven by commodity price shocks and inflation.

Of course as Wall Street loves to say, past performance is not indicative of future performance, and charts are just that – representations of history that may or may not be relevant. The market may not follow either pattern.  But, remember the great secular bull market in stocks from 1983 – 2000 was accompanied by a secular bull market in bonds that began at roughly the same time.  That will not be the case this time around. 

Morning Report – New Fannie Mae DIL program 01/28/13

Vital Statistics:


Last

Change

Percent

S&P Futures 

1497.4

1.7

0.11%

Eurostoxx Index

2747.9

3.7

0.13%

Oil (WTI)

96.17

0.3

0.30%

LIBOR

0.302

0.001

0.33%

US Dollar Index (DXY)

79.84

0.092

0.12%

10 Year Govt Bond Yield

1.96%

0.02%


RPX Composite Real Estate Index

192.6

0.0


Markets are slightly higher this morning after a strong earnings report from Caterpillar and strong durable goods numbers. Bonds continue their swoon, with the 10 year approaching 2%. Is the “risk on” trade we have been waiting for since 2008 finally at hand?  MBS are down as well.

Fannie Mae is offering deed-in-lieu options for underwater borrowers who are current on their mortgage and have experienced some sort of hardship like illness, job change, or other problems.  It effectively allows these homeowners to “toss the keys to the bank” and walk away from their underwater property with the underwater portion of their mortgage debt forgiven. The program does not address mortgages, so a second-lien holder could prevent a homeowner from walking away.

The Federal Appeals Court has rejected Obama’s recess appointments, specifically his appointments to the NLRB and the CFPB. Cordray’s appointment to head the CFPB was an interim appointment, and he will have to go through the process for his 5-year term.  Will it change anything for people in the industry?  Probably not.

Since we have kicked the debt ceiling can down the road for a few months, the next item is the sequestration – which is all of the automatic spending cuts that kick in.  Half will be in defense, and half will be in non-defense discretionary spending. Paul Ryan was on Meet the Press and said that he expects the sequestration cuts will happen.  Agencies are bracing for the cuts to happen as well.

Looks like the eminent domain idea is officially dead, at least in California.

Bites & Pieces: Easy-Peasy Crusty Artisan Bread

French Onion Soup a la Alton Brown

I always thought that making French onion soup would be difficult until I saw this episode of Good Eats (and then got the cookbook).  But this is really, really simple also.  I’ve found that I need to use an electric skillet for this, as it’s difficult to get a burner down low enough, but other than that it’s a snap.

5  lbs   onions (I like to use a mix of sweet and red, just don’t use all hot onions)

3  Tbs   butter

3  tsp   kosher salt

2  cups white wine

3 cups beef consumme or homemade beef broth (use good stuff)

2 cups chicken broth

1 bouquet garni

1 loaf  Mike’s bread (or other good, fairly dense, bread)

1 splash Cognac (optional. . . but it won’t taste the same without it)

4 oz   Fontina, Gruyere, or other melting cheese

  1. Turn electric skillet (12″ skillet) to 250, or place a 4-qt sauce pan over low heat.  Peel the onions, cut them end-to-end and then slice into thin half moons.  Melt the butter in the skillet, then add the onions in three layers, salting each layer with about 1 tsp of the salt.
  2. Sweat the onions for 15 – 20 minutes without stirring (don’t let them sizzle or brown).  Continue to cook, stirring occasionally, for about an hour, or until they’re mahogany colored and reduced to about 2 cups.
  3. Add just enough wine to cover the onions, then turn the heat up to 375 (high) and cook until the wine is reduced to a syrupy consistency.  Add the beef consumme, chicken broth, and bouquet garni, reduce the heat and simmer for 20 minutes.
  4. Set an oven rack in the top third of the oven and set the broiler to high.  Cut out rounds of bread to fit into the top of your soup crocks, place the rounds on a sheet pan and place under the broiler until they just start to brown (about 1 minute).
  5. Season the soup with salt and pepper and the cognac (if using) and ladle into the crocks.  Place the rounds, toasted side down, on top of the soup and cover with the cheese.
  6. Broil until the cheese is bubbly and golden.
  7. Enjoy!

–Michigoose


No Knead Bread (a la Mark Bitman)

This is a nice crusty bread. Since you bake it in a covered pot, there is no need to spray/brush with water to harden the crust. It takes some time to rise because there is so little yeast. If you use 1 packet of yeast (1/4 oz), you can cut the first proofing time to 4 hours.

3 cups all-purpose or bread flour, more for dusting

¼ teaspoon instant yeast

1¼ teaspoons salt

Cornmeal or wheat bran as needed.

1. In a large bowl combine flour, yeast and salt. Add 1 5/8 cups water, and stir until blended; dough will be shaggy and sticky. Cover bowl with plastic wrap. Let dough rest at least 12 hours, preferably about 18, at warm room temperature, about 70 degrees.

2. Dough is ready when its surface is dotted with bubbles. Lightly flour a work surface and place dough on it; sprinkle it with a little more flour and fold it over on itself once or twice. Cover loosely with plastic wrap and let rest about 15 minutes.

3. Using just enough flour to keep dough from sticking to work surface or to your fingers, gently and quickly shape dough into a ball. Generously coat a cotton towel (not terry cloth) with flour, wheat bran or cornmeal; put dough seam side down on towel and dust with more flour, bran or cornmeal. Cover with another cotton towel and let rise for about 2 hours. When it is ready, dough will be more than double in size and will not readily spring back when poked with a finger.

4. At least a half-hour before dough is ready, heat oven to 450 degrees. Put a 6- to 8-quart heavy covered pot (cast iron, enamel, Pyrex or ceramic) in oven as it heats. When dough is ready, carefully remove pot from oven. Slide your hand under towel and turn dough over into pot, seam side up; it may look like a mess, but that is O.K. Shake pan once or twice if dough is unevenly distributed; it will straighten out as it bakes. Cover with lid and bake 30 minutes, then remove lid and bake another 15 to 30 minutes, until loaf is beautifully browned. Cool on a rack.

Yield: One 1½-pound loaf.

–Mike

Mark’s pretty EZ and rich cream of mushroom soup.

For 8 big bowls of cream of mushroom soup, first make about a quart of clear vegetable broth.
2 carrots
1/2 red onion
3 celery stalks
3 sprigs of flat-leaf parsley
1/2 tspn thyme
1/2 tspn ginger
2 cloves of garlic
5 coriander seeds [you could use something else here or nothing if you don’t like coriander]
5 black peppercorns
1 bay leaf
1/2 tbsp sea salt
4 cups of filtered or distilled water, unless your tap water has no off flavor.

Wash and cut veggies into big chunks and place in a large pot. Add everything. Cover and bring to a full boil. Reduce the heat and gently simmer until all the vegetables are beginning to fall apart / 30 min. Strain the mess to get the clear stock. Let the stock cool.

For the cream of mushroom soup we need 2 lbs of cremini mushrooms or baby bellas, not whites.
1 Tbsp lemon juice
half a stick of unsalted butter
3 chopped green onions
1 teaspoon thyme
1 bay leaf
1 tspn salt
1/2 tspn pepper
4 cups heavy cream
4 cups veggie stock
a little tapioca flour to thicken at end
parsley for garnish

Coarse chop the mushrooms with the lemon juice in the food processor. Melt the butter in a big skillet and saute the chopped green onions until they are limp and the white parts are translucent. Dump in the mushrooms, thyme, and bay leaf and saute on low medium for 15 minutes.

Have the veggie stock and the cream slightly simmering in a big pot on the next burner. Dump the mushroom mix into the cream and stock mix. Add salt and pepper. Simmer for ten minutes, and only use the tapioca starch [or cornstarch] if you think it needs thickening. Stay away from flour here it changes the flavor, IMO.

Ladle into bowls and sprinkle with parsley.

Wonkbook’s graph of the day…

Wonkbook posted their Graph of the Day today, linking to a Mother Jones piece. Their point is that if you think Obama’s a big spender, you need to see two charts.  Here they are:


Drum [author of the Mother Jones piece] says, is that “total government spending didn’t go up much during the Clinton era, and it’s actually declined during under President Obama.”

Total Gov Spending Per Capita


[S]ome said Drum’s chart was a trick, as it looked at total government spending rather than just federal spending. So on Wednesday, he posted a second chart. This one only included federal spending and it didn’t adjust for population growth. The only thing is adjusts for is inflation.

Total Fed Spending Per Capita

[T]he sharp rise in federal spending begins in late-2009 and is largely over by 2010. It’s ridiculous to attribute all that spending to Obama, who wasn’t in office when it began, rather than to the recession, which is the clear and obvious cause.

Wonkbook Graph of the Day

Food for thought.

Morning Report – Radar Logic Outlook 01/25/13

Vital Statistics:

  Last Change Percent
S&P Futures  1496.5 4.7 0.32%
Eurostoxx Index 2741.8 18.8 0.69%
Oil (WTI) 96.22 0.3 0.28%
LIBOR 0.301 0.000 0.00%
US Dollar Index (DXY) 79.73 -0.217 -0.27%
10 Year Govt Bond Yield 1.91% 0.07%  
RPX Composite Real Estate Index 192.5 0.4  

US stock index futures are higher this morning on the back of a sell-off in bond futures. The sell-off began around 4:00 am, and I don’t see any single economic story in Europe that would explain it. German confidence was higher than expected, and the Euro banks plan on paying off the ECB loans earlier than expected.  Could be a big asset allocation switch, but why do you do it at the opening of Europe?  Strange. The 10-year now yields 1.91%, and is flirting with resistance around the 1.91 – 1.92 level. MBS are weaker this morning as well. 

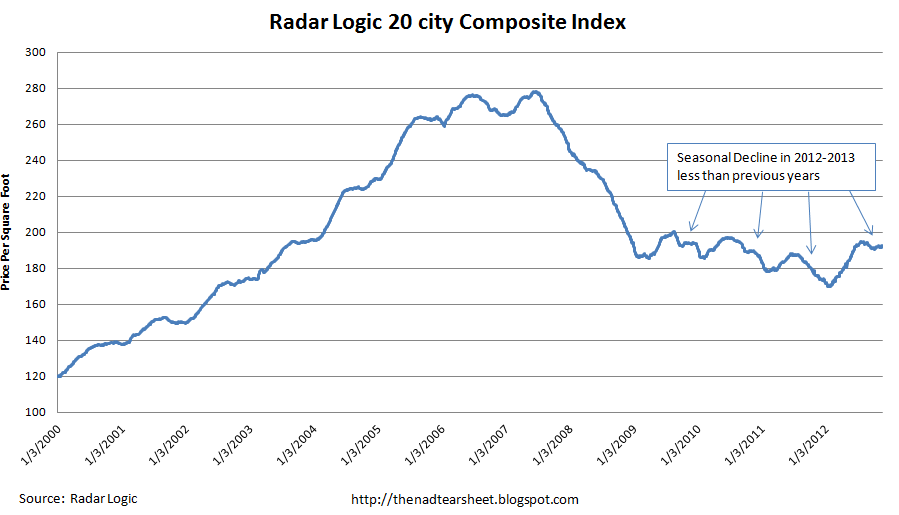
The theme of Radar Logic’s November 2012 monthly report is:  It is still too early to call a housing recovery.   Radar Logic has consistently been more bearish on the outlook for housing than Case-Schiller or the government.  In their view, the strength in 2012 was due more to easy comparables from a lousy 2011 than any true organic growth. The typical seasonal drop in prices this year has been much lower than in the past. In addition, the increase in house prices has been driven more by a drop in distressed sales than an increase in the value of individual properties. Finally, they note that housing demand has been driven primarily by institutional investors, who’s demand may be temporary.  

Chart:  Radar Logic 20 City Composite:

Another monetary milestone:  The Fed’s balance sheet breaks the $3 trillion barrier.

Its baaaack… The San Bernardino Eminent Domain debate returns with a public meeting.  The eminent domain route is fraught with legal roadblocks and will probably not work.  Yet Mortgage Resolution Partners is committed to covering the legal costs and would be willing to take the case to the Supreme Court. The payoff for them if it works is decent, but I don’t see how their limited partners are willing to accept this risk / reward.  

Is the “D” the new Phoenix?  Yes, house prices have gotten demolished, but the population of Detroit has been shrinking since the 1950s.  Completely opposite of the Southwest. I guess a $500 house is a $500 house and any investment becomes attractive if it gets cheap enough.

Will Jack Lew’s tenure at Citi cause problems for his nomination to Treasury Secretary?  Richard Cordray will undoubtedly have some opposition in the Senate.  I have not heard much in the way of opposition to Mary Jo White for SEC.

Carl Icahn has entered the Herbalife fray.  Let’s just say there is no love lost between Carl and Ackman.

Morning Report – Orders increase at KB Homes 01/24/13

Vital Statistics:

Last Change Percent
S&P Futures 1488.5 -1.8 -0.12%
Eurostoxx Index 2706.9 -1.4 -0.05%
Oil (WTI) 95.96 0.7 0.77%
LIBOR 0.301 -0.001 -0.17%
US Dollar Index (DXY) 80 0.083 0.10%
10 Year Govt Bond Yield 1.83% 0.01%
RPX Composite Real Estate Index 192.1 -0.1

Markets are lower after Apple stunk up the joint.  Initial Jobless Claims came in at 330k.  The Markit PMI came in at 56.1.  Bristol Myers and 3M beat expectations. Bonds and MBS are down small.

The IMF forecast world economic growth of 3.5% for 2013.  The US is forecast to grow 2%, with growth accelerating in 2H. The Euro area is expected to contract by .2%.

KB Homes reported that preliminary quarter-to-date net orders increased 54%.  Separately, they announced they are forming a home-loan company for its buyers with Nationstar. Concurrently, they are doing a $100MM secondary and a $200MM convertible bond issue priced at 1.375s up 50.

Obama is expected to name Mary Jo White as the new head of the SEC. A former prosecutor, she is expected to signal the importance of holding Wall Street accountable.

Bob Schiller is still cautious on housing.

The renovation boom continues.  As inventory remains small, many homeowners are choosing to upgrade current homes as opposed to buying new ones.  Are 203ks the next big thing?

Morning Report – FHFA House Price Index 01/23/13

Vital Statistics:


Last

Change

Percent

S&P Futures 

1487.3

-2.1

-0.14%

Eurostoxx Index

2711.0

-5.7

-0.21%

Oil (WTI)

96.78

0.1

0.10%

LIBOR

0.301

-0.001

-0.33%

US Dollar Index (DXY)

79.76

-0.117

-0.15%

10 Year Govt Bond Yield

1.83%

-0.02%


RPX Composite Real Estate Index

192.2

-0.6


Markets are slightly lower this morning in spite of good earnings reports out of IBM and Google.  After the close, we get Apple’s 4Q as well.  Mortgage Applications were up last week. Later on we will get the IMF world economic outlook.

The House will vote today to suspend enforcement of the debt limit through mid-May, in order to put pressure on the Democratically controlled Senate to pass a budget and to relieve the pressure on the debt ceiling crisis. Obama says he will go along with it. Which means the next subject will be the sequestration cuts.

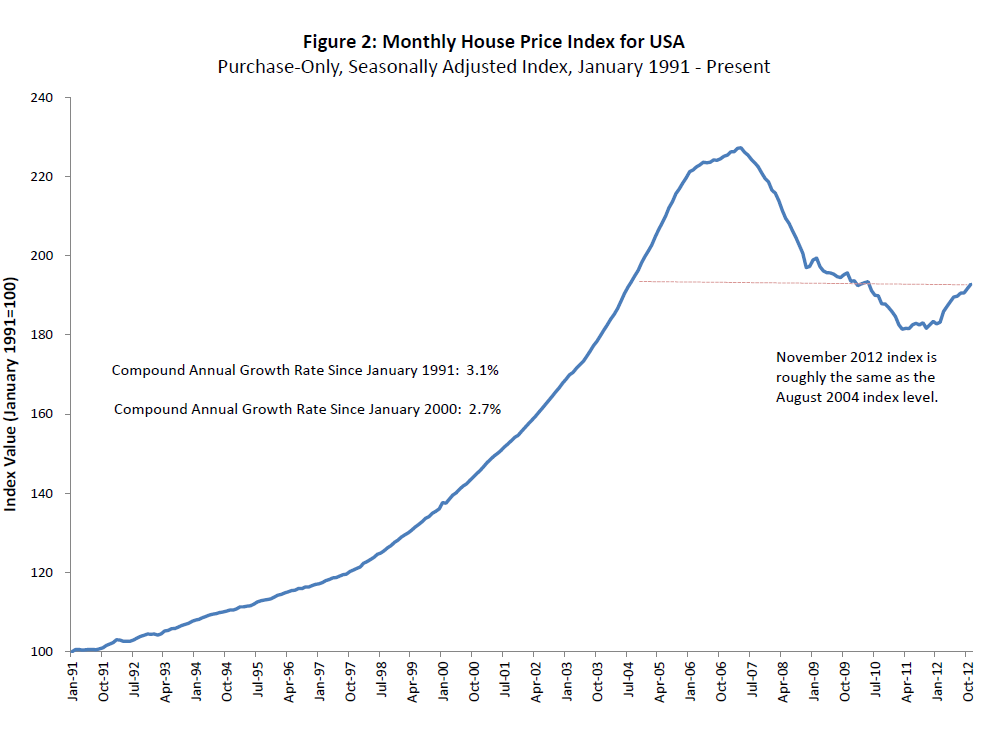
The FHFA House Price Index rose .6% in November.  On a YOY basis, prices are up 5.6%.  The FHFA index only looks at conforming mortgages, which is more stable than the broader indices.  Prices are back to August of 2004 levels.

 Is the roughly $1.7 trillion of foreign earnings stashed offshore by US companies something that is kept out of the US economy?  Turns out that a lot of it is in offshore accounts, invested in US dollar assets like Treasuries and MBS, which undermines the argument that all of this foreign cash could be circulated in the US economy if we changed the tax laws.  That said, this money is not available for expansion in the US or for distributions to shareholders.

The NAHB expects the housing upturn that started last year to pick up momentum, in spite of headwinds coming out of tight mortgage lending and potential tax changes. Using 2000-2003 as a baseline, the single-family market was running at 44% of normal production.  The NAHB forecasts 949k total housing starts in 2013.  From 1959 through 2002, 1.5 million units a year was considered “normal”

Jamie Dimon had some words for regulators at Davos. Suffice it to say that bankers loved it, and the chattering classes / political classes did not. If obama’s inauguration speech was a full-throated defense of activist government, Dimon’s speech was a defense of the private sector.

Morning Report – S&P earnings 01/22/13

Vital Statistics:

  Last Change Percent
S&P Futures  1477.5 -1.4 -0.09%
Eurostoxx Index 2715.3 -11.3 -0.42%
Oil (WTI) 95.48 -0.1 -0.08%
LIBOR 0.302 0.000 0.00%
US Dollar Index (DXY) 79.92 -0.116 -0.14%
10 Year Govt Bond Yield 1.86% 0.02%  
RPX Composite Real Estate Index 192.8 1.0  

Markets are flattish on no real news.  Japan has announced a 2% inflation target, similar to what the Fed has been doing, in an attempt to weaken the yen.  The World Economic Forum meets in Davos this week. For once, there isn’t a major crisis to deal with.  We don’t have a lot of economic data this week, with the exception of leading economic indicators on the 24th.  Bonds are down half a point and MBS are down a tick or two.

We have decent earnings reports this morning from DuPont, Travelers, Johnny John, and Freeport.  This is one of the heaviest weeks for earnings reports, and erstwhile market darling Apple reports tomorrow after the close.

The WSJ is predicting that companies will increase share buy-backs this year as companies try and figure out what to do with excess cash. This will buoy the S&P 500 and mask the effect of flat earnings. Many strategists believe that US companies have pretty much wrung out all of the excess costs they can and any further earnings growth will have to come from revenue growth.  And if you can’t get revenue growth, how do you show increasing EPS?  You guessed it – buybacks. 

Is the financial system finally back on its feet?  We will see if Silver Lake is able to obtain financing for its planned $24 billion LBO of Dell. This is one of the side effects of the Fed’s QE efforts – in an era of rock-bottom interest rates, pension funds and insurance companies are starving for yield, which makes the splashy LBO possible again.

The Chicago Fed National Activity Index came in +.02 in December, down from +.27 in November. The 3 month moving average is still negative, indicating economic activity is below its historical trend. 

The House will vote on a 4-month extension of the debt ceiling, which seems to take the default issue off the table.  All eyes will then turn to the sequestration cuts and the continuing resolution. 

The CFPB has released a summary of the new broker / LO loan comp rules.  LO comp may not be based on any of the transaction’s terms of conditions. In other words, the interest rate does not matter, and LOs cannot be comped for steering a borrower to purchase title insurance from an affiliate. Pricing concessions are out as well. 

Finally, as a child of the 70s, I note with sadness the passing of Atari.  

Bites and Pieces: West African Edition

I hosted a wine dinner on Saturday. It was a bit too ambitious in that I picked 7 fishes as the theme, from the Italian tradition, and also did dishes from 7 . I cheated a bit on Antarctica—frozen yogurt. The trickiest one for planning was Africa. I know relatively little about African cooking (except Ethiopia). Fortunately, my wife went to West Africa (Mali) for her stint in the Peace Corps and knew exactly what to do. Yassa.

Yassa is a Senegalese dish, traditionally served with chicken (Poulet en Yassa). It also works very well with grilled fish. I tried it with swordfish, which was a good finish to the meal. The key ingredients are onions, lemon juice and peanut oil. One traditionally marinades the meat in the ingredients, but I think separating it works.

Ingredients

1 – 2 pounds of swordfish, cubed*

½ cup of peanut oil


Yassa Sauce

4 – 6 yellow onions, sliced

½ cup of lemon juice

½ cup of cider vinegar

1 tablespoon minced garlic

2 tablespoons mustard

1 tablespoon soy sauce (Maggi is traditional; soy works fine)

1 minced chili pepper (optional)

Pepper and salt to taste

  1. Combine all ingredients and let rest for at least 2 hours
  2. Cube the swordfish and set aside. If you have a favored preparation, go for it. A bit of salt, pepper, cumin and turmeric works with the flavors of this dish. Have fun!
  3. Heat the peanut oil in a large, heavy bottomed pan or dutch oven. Drain the onions, setting aside the marinade, and add to the pan. Cook over medium heat until softened (and possibly browned a bit). Add the reserved marinade and bring to a boil. Cook until the onions form a sauce
  4. Cook the fish however you like. I planned to grill it, but the coals had gone mostly dark by the time I was ready to cook the fish. I heated up a couple of tablespoons of peanut oil in a pan and seared it, then added the sauce.
  5. Combine the fish and sauce. Warm to combine. Serve over rice. 

*For those who have concerns about the mercury content of swordfish, the dish is made traditionally with sea bass (Poisson Yassa). Chicken breast or pork loin would also work.