I Blame NoVA

http://www.washingtonpost.com/blogs/federal-eye/wp/2014/09/15/how-states-have-gamed-medicaid-for-hundreds-of-millions/?wpisrc=nl_fed&wpmm=1


You healthcare lobbyists should have written a law without loopholes to begin with.


I am curious as to what is the net effect of revenue matching laws.  It seems to me that revenue match for a particular program that bypasses the state’s general coffers might achieve the supposed result of more program funding, but considering how it is normally done, I think it is simply a transfer of deficit raised federal dollars to state general revenues.


We have so many revenue matching programs.  I assume that Highway funding is the largest one, followed by Medicaid.  Or perhaps vice versa.  I believe that in TX all fed revenues into both are used however the Lege desires.


Should a federal/state joint venture like highway construction even have a feature like “revenue matching”?  What purpose does it actually serve?  Assume with me that interstate highways are basically federal responsibilities.  Nevertheless, the R.O.W. impacts are all local, and state and local input are critical to managing the minimum damage to a community.  So cooperation is a legitimate goal, but does revenue matching have anything to do with that?  Is it possible states or localities were blackmailed into supporting the interstate system financially, or else the feds would have drawn the roadway to kill commerce in a town?


The article calls the gaming of Medicaid by the states “waste”.  But it seems to me the structure was established as a “game”.  If you see revenue matching as other than an invitation to increase the federal deficit in order to permit states to have the pleasure of spending money they did not have the pain of raising, explain it to me.


Happy Birthday, ATiM

Today ATiM celebrates its 3rd anniversary. Despite our much reduced daily content, and although I am more often than not disappointed to find nothing new, I must confess that ATiM remains the first website I check every morning, so on my own behalf I want to offer my sincere thanks to all of you who have stuck with it and continue to be daily contributors. I could easily provide a list, but this is supposed to be a happy occasion, so best not to make the depressingly short list too explicit.

One interesting thing worth noting: In my quest to make this anniversary post at least somewhat entertaining by taking a walk down memory lane, I was originally going to link to some of the better threads we’ve had over the last few years, but while searching I discovered that, despite the diminished number of contributors, we did manage to set a new record in 2014 for most comments on a single post. It was McWing’s President’s Day Post which was, ironically, itself devoid of literally any content whatsoever, but managed to produce an impressive 279 comments.

2014 also produced a 242 comment post by Mark, Gay Conservatives Denied ‘Official’ Spot at Texas GOP Convention, which placed in the top 5 of most comments in history.

To be fair, though, neither of these more recent posts can be said to even approach what was the longest thread in ATiM history. That distinction belongs to a memorable thread that was so epic it needed two separate posts by Mich, the first of which alone had the 3rd highest number of comments (252), and the second of which was nearly 70% as long as the first (176), combining for a total 428 comments. I believe that this thread represents the zenith of ATiM’s participation rate.

Anyway, congrats again to ATiM for surviving a 3rd tempestuous year. Here’s to one more.

(Shall we take bets on who is still commenting by September 13, 2015?)

Morning Report – The Fed thinks the labor force participation rate isn’t going to increase meaningfully9/12/14

Markets are flat as we close out a dull week. Bonds and MBS are down amidst a global bond sell-off.

Retail Sales increased .6% in August. Ex autos and gas, they increased .4%. July’s numbers were revised upwards.

Import prices fell .9% in August, driven by a drop in oil prices. Ex food and fuels, import prices were flat.

The preliminary September reading for the University of Michigan Consumer Sentiment indicator showed an increase and hit the high for the past year.

The jumbo securitization market is pretty much dormant, except for the occasional Redwood Trust deal. Only 2.3% of all jumbos originated in the first half of 2014 have been securitized. At the peak of the housing bubble, almost half of all jumbos were securitized. Banks are instead choosing to hold them on their balance sheet. Banks are subsidizing the jumbo mortgage rate in order to bring in the wealthy client and then offer all other sorts of banking services, including the lucrative wealth management business.

Another article about the lowering of the speed limit for the economy. Federal Reserve economists do not expect the labor force participation rate to increased meaningfully as the labor market improves. They argue that the number of people who aren’t working, but would work if conditions were better are relatively small. The upshot is that this paper bolsters the hawk case at the Fed and is ammo for those who want to start raising rates. Not sure dove Yellen will play along, and the voting members will take a dovish turn next year as hawks like Plosser lose their vote.

Morning Report – Another sign of a credit market top 9/11/14

Markets are higher this morning on on real news. Bonds and MBS are rallying.

Initial Jobless Claims came in at 315k, a little higher than street expectations, but still a good number.

The President talked about ISIS last night. It was a declaration of war. Or something. Here are the takeaways.

The Fannie Mae National Housing Survey is out – average home price expectations continue to fall as consumers temper their bullishness on home price appreciation. People still have a dour view on the economy but it is improving slightly. That said, it looks like incomes took a bit of a hit in August.

Bill Gross of PIMCO has been raising cash in his Total Return Fund, selling Treasuries and developed sovereigns. Mortgages as a percent stayed flat at 20%.

Twitter is doing a new convertible bond which are convertible into stock or cash at Twitter’s election. This is rare – usually the choice is the bondholder’s not the issuer’s, at least on senior unsecured paper. This isn’t a convertible pref issue. It will be interesting to see the pricing on this – essentially the holder will be short a put on Twitter stock. If Twitter’s stock craters, Twitter gets to essentially sell stock at current levels. If Twitter stock continues to rally, they can either pay cash, or sell Twitter stock in the market at higher prices, redeem the bonds and pocket the difference between the sales price and the conversion price. The bigger point is that bond issues are getting more and more lopsided in favor of the borrower, and that is a classic market top signal. Investors are reaching for yield and taking risks they are not getting adequately compensated for. Paper like this can go no-bid in a hurry. IMO, the stock market is assuming that the Fed can start raising rates without anyone blowing up. Historically that hasn’t happened.

Foreclosure activity picked up in August, according to RealtyTrac. Activity picked up in the big judicial states like New York, New Jersey, and Connecticut.

Morning Report – Mortgage Applications lowest in 14 years 9/10/14

Stocks are lower this morning on no real news. Bonds and MBS are down as European bonds sell off.

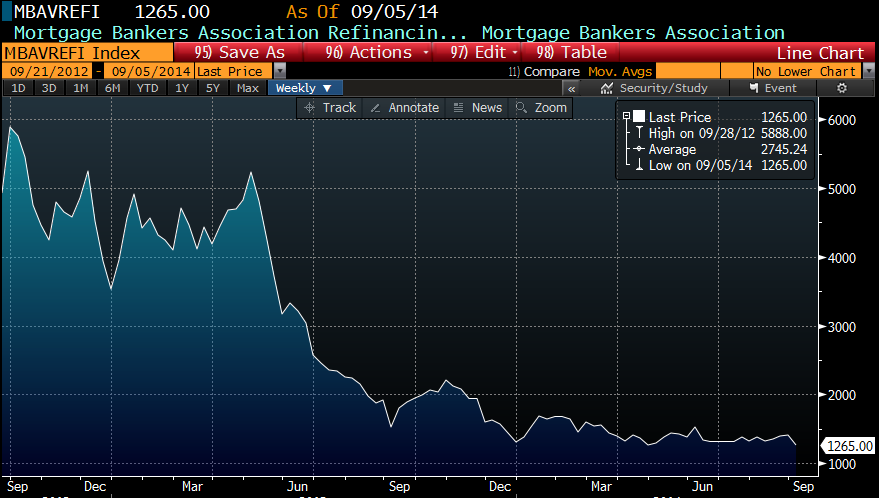
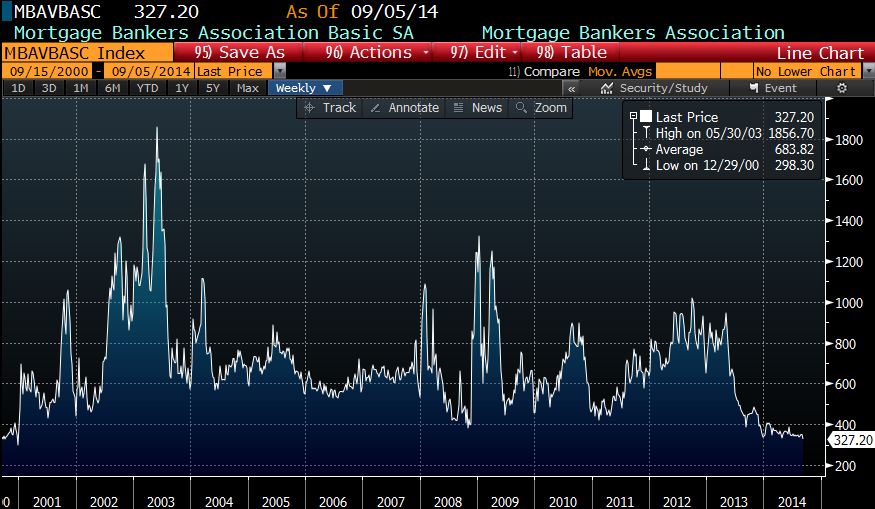
Mortgage Applications fell 7.2% last week as we had the Labor Day holiday and rates backed up. Purchases fell 2.6% while refis fell 10.7%. Refis accounted for 55.4% of all loans. The refi index just hit its lows for the year, even though rates have fallen almost 50 basis points. This effect is called prepayment burnout, and it is due to the fact that anyone that has been able to refinance already has. The driver of refis going forward will be home price appreciation, not rates.

Note that the overall mortgage application index is hitting lows not seen since 2000.

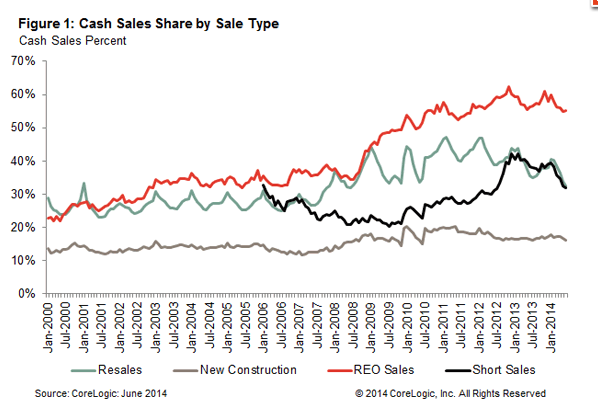
On the plus side, all-cash transactions are down to a six year low.  Cash sales fell to 33% of total home sales in June, down from 36.3% a year ago.

Rep Maxine Waters (D-CA) is introducing legislation to change what goes on credit reports. One fix being considered is eliminating medial debt, which accounts for more than half of all unpaid debt in collection, from credit scores. Other changes would remove settled debts, remove black marks after 4 years instead of 7, and remove student debt defaults if the loan performs for a set period thereafter. The idea is to open access to credit.

Think fast food workers are irreplaceable? Think again. McDonalds is expanding a test concept allowing people to order via a tablet. This makes a good juxtaposition to the “living wage” strikes and legislation being considered.

Unintended consequence of ZIRP, number 1,234,567 – LBO funds are ratcheting up the leverage to boost returns. Not only that, but credit quality and covenants have been declining in these deals. The S&P 500, sitting at record levels, is assigning a 100% probability that the Fed can stick the landing and start raising interest rates without anyone blowing up. As we saw when the Fed started raising rates in 1994, 1999, and 2004, bad things tend to happen (Orange County in 94, the end of the stock market bubble, the end of the real estate bubble). If I was fully invested in the market, I would begin to finish my drink, find my coat, and watch the door.

Morning Report – Job openings the highest since 2001 9/9/14

Stocks are flat on no real news. Bonds continue their post-ECB retreat.

Consumer credit increased 9.7% year over year in July, according to the Fed. Note this does not include mortgages. Revolving debt increased 7.4%, while non-revolving debt increased 10.6%.

Job openings remained steady at 4.7 million in July, which is the highest level since 2001. So why does the labor market stink? People don’t have the skills employers demand.

Small business optimism increased by .4 in August to reach 96.1, the second highest reading since October 2007. Expectations are still glum, however as the majority of small business owners think conditions will be worse in six months. NFIB owners increased employment by an average of 0.02 workers (basically flat), however it was the eleventh positive month in a row. Earnings trends improved 1 point to -17. This statistic shows the stark contrast between the big S&P 500 names (which have a lot of international exposure) versus Main Street Small Business. Reading the report, you wouldn’t guess the S&P 500 is at record highs.

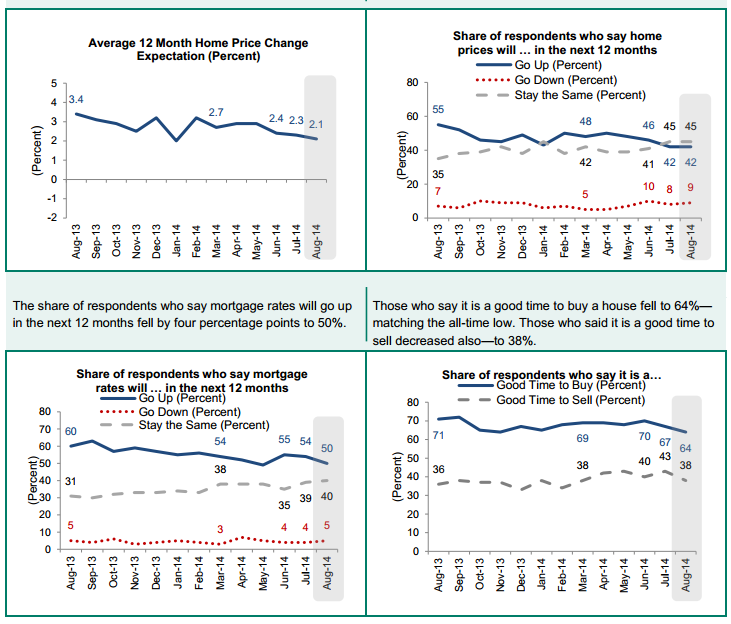
Consumers continue to temper their expectations for home price appreciation, according to the Fannie Mae National Housing Survey. Consumers expect an average 12 month appreciation of 2.1% going forward. 42% of respondents thing house prices will increase, 45% expect them to stay the same, and 9% expect them to fall. 23% said their household income was significantly higher than it was a year ago (a drop from 28% last month), while 15% said their income was significantly lower than it was a year ago (an increase from 12% last month). So regardless of what the consumer sentiment surveys say, things are not necessarily getting better for the average homeowner.

Mohammed El-Arian explains what is going on with US yields vis a vis European yields. Yields could rise in US Treasuries as f/x rates adjust to persistent European economic weakness.

The Fed is contemplating capital requirements that will be even tougher than Basel. At the margin, this would mean less mortgage lending by the big banks like Wells and JP Morgan.

Morning Report – Slow data week ahead 9/8/14

Slow news day. The week following the jobs report always has a dearth of data, so there isn’t much on the economic front to talk about.

We will get consumer credit out of the Fed sometime this afternoon.

Why is credit so tight for first time homebuyers and people with low FICOs? Ask Washington. It seems like the authorities are now forcing buybacks and fines over relatively minor errors, and as a result, lenders are refusing to extend credit to low-income / low FICO borrowers. Of course the Administration continues to exhort the industry to loosen standards at the same time it announces record settlements.

A majority of primary dealers see the first rate hike in the second quarter of 2015. The median forecast for the Fed Funds rate at the end of 2015 is 1% and 2.5% for the end of 2016.

Hawk Charles Plosser says that keeping rates near zero until the Fed’s goals are achieved is a risky strategy.

Morning Report – Lousy jobs report 9/5/14

Markets are lower after a lousy jobs report. Bonds and MBS are up.

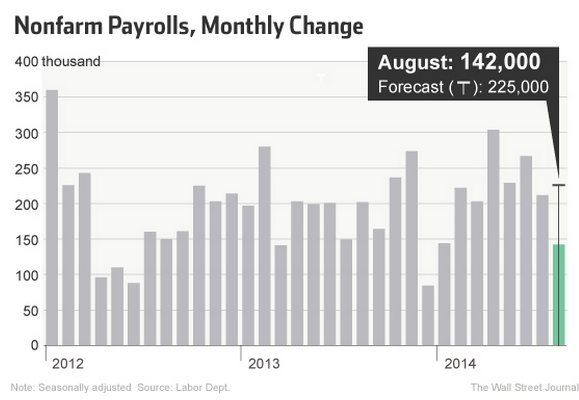
The jobs report came in surprisingly weak. Payrolls increased 142k in August, while the Street was expecting to see 230k. The two-month revision was -28k. Unemployment ticked down to 6.1%, however the labor force participation rate dropped back to its lows at 62.8%. Average Hourly Earnings rose .2% and the workweek was flat at 34.5 hours. Overall, a very disappointing report that doesn’t really comport with some of the other data we have been seeing (like the ISM which has been super strong). I wouldn’t be surprised to see this report revised upward (for the record, August reports are notorious for big revisions), but for the moment, there it is.

 nonfarm payrolls wsj

Demographically, it looks like the biggest growth was in the 25-35 year old cohort, which is what we need to see in order to bring back the first time homebuyer. Interestingly we saw a bit of growth in the 55+ age bracket.

Minneapolis Fed President Kocherlakota believes the Fed should be doing more, not less to stimulate the economy. He says that “interest rates are not low enough….Given where we are with inflation, I think that it’s challenging to know why we are removing stimulus from the economy at the rate that we are.” Note that the makeup of the Fed changes every year, and two hawkish voting members – Plosser and Fisher are being replaced by doves Evans and Lockhart. This  will mean one lone hawk, four neutral, and five doves.

Mortgage credit tightened slightly in August, according to the MBA. Credit did ease for 203k loans and construction loans, but overall credit dipped, particularly on the government side.

Morning Report – Lots of labor data 9/4/14

Markets are higher this morning after the ECB cut rates to 5 basis points and committed to start buying securitized debt and covered bonds in October. Bonds are flat as this decision had been priced in already.

Just something to think about – the “buy the rumor, sell the fact” effect. In other words, the big move for ECB QE was over the past six months, and it wouldn’t be surprising to see a sell-off in sovereigns as the announcement is out of the way and speculative players unwind their positions. Euro sovereigns are driving the US bond market at the moment.

Fun fact, 45% of global sovereign bonds yield under 1% according to Bank of America.

Denmark just cut its deposit rate to negative 5 basis points. They are in the throes of a burst real estate bubble.

The ISM Non-Manufacturing index rose to 59.6, the highest since August 2005. The manufacturing index rose to 59, and would correspond to a GDP growth rate of 5.2%. Of course manufacturing doesn’t have the impact on the US economy it used to, but still….

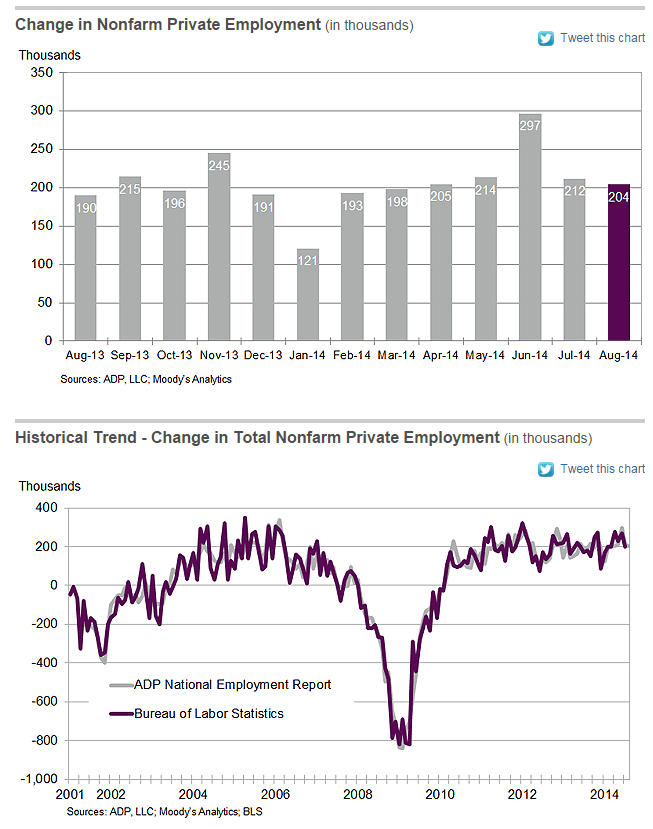
ADP is forecasting the economy will add 204,000 jobs in August. ADP has been spot-on the last couple months. The Street is forecasting 215k tomorrow.

 ADP employment

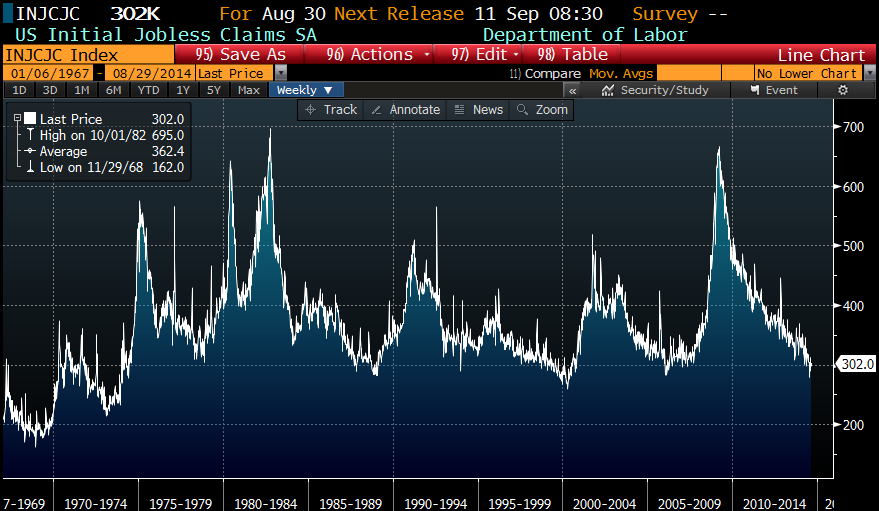
In other labor market data, announced job cuts fell 21% according to outplacement firm Challenger, Gray and Christmas. Unit Labor Costs fell .1% in the second quarter as productivity rose 2.3%. Finally, initial jobless claims ticked up slightly to 302,000. Initial Jobless Claims levels are back to boom-time levels, and as a percent of the population are back to levels not seen since the late 1960s.

 Initial Jobless Claims long term

What is holding back wage inflation? Pent-up deflation. As Keynes pointed out, during recessions wages should fall as the demand for labor falls. However, employers are loath to cut pay (a phenomenon called sticky wages) which means that by not cutting wages, employers are overpaying during a recession. As the recovery builds steam, therefore they are not feeling pressure to raise them either. Interesting theory, and one thing the researchers say is that once this runs its course, wages could rise more quickly than economic models suggest as businesses that kept wages low for too long are forced to play catch up. This may in fact be what was behind the language in the FOMC minutes about there being less slack in the labor market than people think. We will see tomorrow with the jobs report. Separately, the average weekly hours worked by a full time employee inched up to 46.7 hours.

Constitutional Authorization

A question for all….

The powers of the congress are layed out in Section 8 of Article I of the constitution, which reads as follows:

The Congress shall have Power To lay and collect Taxes, Duties, Imposts and Excises, to pay the Debts and provide for the common Defence and general Welfare of the United States; but all Duties, Imposts and Excises shall be uniform throughout the United States;

To borrow Money on the credit of the United States;

To regulate Commerce with foreign Nations, and among the several States, and with the Indian Tribes;

To establish an uniform Rule of Naturalization, and uniform Laws on the subject of Bankruptcies throughout the United States;

To coin Money, regulate the Value thereof, and of foreign Coin, and fix the Standard of Weights and Measures;

To provide for the Punishment of counterfeiting the Securities and current Coin of the United States;

To establish Post Offices and post Roads;

To promote the Progress of Science and useful Arts, by securing for limited Times to Authors and Inventors the exclusive Right to their respective Writings and Discoveries;

To constitute Tribunals inferior to the supreme Court;

To define and punish Piracies and Felonies committed on the high Seas, and Offences against the Law of Nations;

To declare War, grant Letters of Marque and Reprisal, and make Rules concerning Captures on Land and Water;

To raise and support Armies, but no Appropriation of Money to that Use shall be for a longer Term than two Years;

To provide and maintain a Navy;

To make Rules for the Government and Regulation of the land and naval Forces;

To provide for calling forth the Militia to execute the Laws of the Union, suppress Insurrections and repel Invasions;

To provide for organizing, arming, and disciplining, the Militia, and for governing such Part of them as may be employed in the Service of the United States, reserving to the States respectively, the Appointment of the Officers, and the Authority of training the Militia according to the discipline prescribed by Congress;

To exercise exclusive Legislation in all Cases whatsoever, over such District (not exceeding ten Miles square) as may, by Cession of particular States, and the Acceptance of Congress, become the Seat of the Government of the United States, and to exercise like Authority over all Places purchased by the Consent of the Legislature of the State in which the Same shall be, for the Erection of Forts, Magazines, Arsenals, dock-Yards, and other needful Buildings;—And

To make all Laws which shall be necessary and proper for carrying into Execution the foregoing Powers, and all other Powers vested by this Constitution in the Government of the United States, or in any Department or Officer thereof.

Which of these explicit powers authorizes the creation of (to take just one of many examples) the Environmental Protection Agency and the law/regulations that it promulgates?